
Market Overview
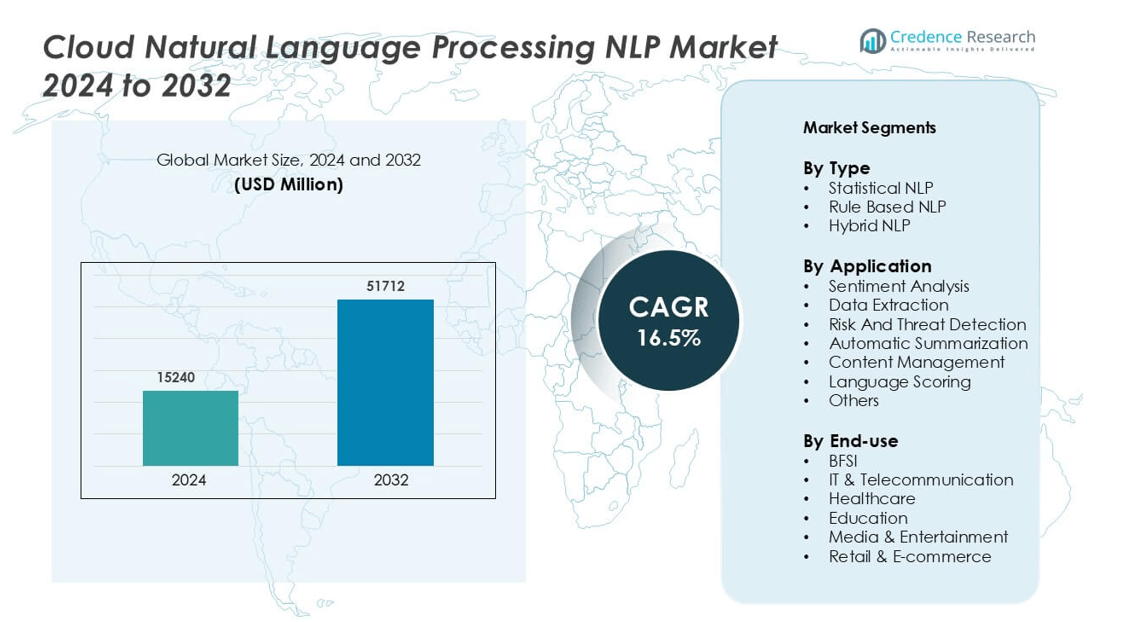
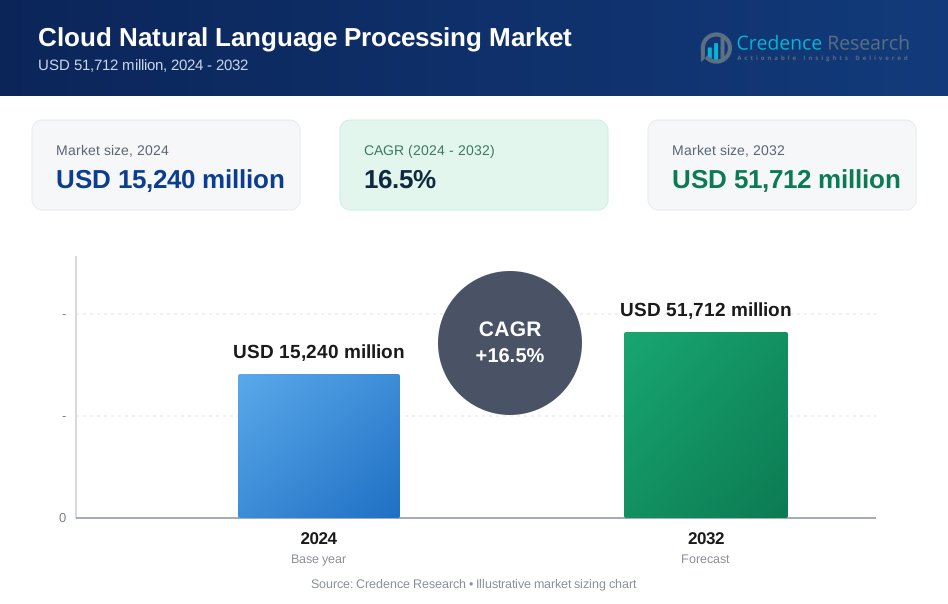
Cloud Natural Language Processing NLP Market was valued at USD 15240 million in 2024 and is anticipated to reach USD 51712 million by 2032, growing at a CAGR of 16.5% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Cloud Natural Language Processing (NLP) Market Size 2024 | USD 15240 million |
| Cloud Natural Language Processing (NLP) Market, CAGR | 16.5% |
| Cloud Natural Language Processing (NLP) Market Size 2032 | USD 51712 million |
The Cloud NLP market is highly competitive, led by major technology providers and specialized analytics companies. Key players include Amazon Web Services, Google LLC, Apple Inc., IBM Corporation, Baidu Inc., IQVIA, Inbenta, Crayon Data, Health Fidelity, and 3M. These vendors invest in advanced AI models, multilingual support, and industry-focused solutions for healthcare, BFSI, telecom, and retail. Their cloud-based NLP platforms help enterprises automate customer interactions, analyze text at scale, and improve decision-making. North America remains the dominant region with a 38% market share, driven by strong cloud adoption, high digital transformation spending, and rapid integration of generative and conversational AI into enterprise workflows.
Market Insights
- The Cloud NLP market was valued at USD 15240 million in 2024 and is projected to grow at a CAGR of 16.5 % through 2032, supported by rising enterprise adoption and cloud-based deployment models.
- Strong market drivers include increasing automation in customer service, real-time sentiment analysis, and demand for intelligent chatbots across BFSI, telecom, retail, and healthcare.
- Key trends center on multilingual NLP, generative AI integration, and industry-specific language models that improve accuracy and domain understanding for regulated sectors.
- Competition remains intense with players like Amazon Web Services, Google, IBM, Apple, Baidu, IQVIA, and 3M focusing on API-based delivery, data security, and advanced deep learning features.
- North America leads with 38% regional share, while Hybrid NLP holds the highest segment share due to superior contextual accuracy; Asia Pacific shows the fastest growth driven by e-commerce expansion and mobile usage.
Market Segmentation Analysis:
By Type
Hybrid NLP holds the largest share in this segment due to its combined strength of statistical learning and rule-based language understanding. Organizations prefer hybrid systems because they deliver higher accuracy in entity recognition, language translation, and contextual analysis. Statistical NLP supports large-scale language modeling, but hybrid frameworks reduce errors caused by ambiguity in human language. Rule-based systems remain relevant in regulated workflows where deterministic outputs are required. The shift toward hybrid NLP continues to grow as enterprises need scalable, reliable, and context-aware solutions for multilingual and domain-specific tasks.
- For instance, Google’s BERT-based multilingual model supports 104 languages and is trained on a dataset of more than 3.3 billion words.
By Application
Sentiment Analysis leads this segment with the highest market share, driven by rising adoption in e-commerce, social media analytics, and customer experience platforms. Retailers and consumer brands rely on sentiment engines to track product perception, customer satisfaction, and brand loyalty. Data Extraction and Risk & Threat Detection grow strongly due to increased digital transactions and compliance monitoring. Automatic summarization and content management gain traction with rising enterprise data volumes. Language scoring supports online learning and language testing platforms, expanding usage across EdTech companies and assessment providers.
- For instance, IBM Watson NLU is typically offered on a per-item or subscription basis, which implies varying usage levels rather than a fixed global volume. For example, a "Lite" plan offers a limit of 30,000 NLU items per month for proof-of-concept use cases.
By End-use
BFSI represents the dominant end-use segment with the largest market share, supported by strong demand for fraud detection, chatbots, regulatory compliance, and automated customer service. Banks and insurers deploy NLP engines to analyze claims, monitor transactions, and reduce operational workload. IT & Telecom and Healthcare follow due to their heavy data processing needs, while Education benefits from language assessment and learning analytics. Media & Entertainment and Retail & E-commerce adopt NLP to improve recommendation engines, search relevance, and personalized content delivery.
Key Growth Drivers
Rising Cloud Adoption and Enterprise Digital Transformation
Enterprises are shifting workloads from on-premise systems to cloud infrastructure to improve scalability, speed, and cost efficiency. This transition increases demand for cloud-based NLP, as organizations want language processing tools that run quickly without heavy hardware investment. Cloud NLP platforms offer on-demand computing power, real-time analytics, and easy integration with CRM, helpdesks, chatbots, and data warehouses. Businesses use these tools to automate customer support, extract insights from text, and analyze feedback across emails, chats, and social media. As companies expand remote work and digital customer interactions, cloud NLP provides faster deployment, pay-as-you-go pricing, and global access. These factors strongly push market growth.
- For instance, IBM Watson Discovery enables NLP-based search over enterprise datasets and can analyze over 10 million documents with automated relevance ranking and semantic search features.
Increasing Use of NLP in Customer Experience and Automation
Companies in banking, telecom, retail, and healthcare now handle large volumes of customer conversations. Cloud NLP enables automated call transcripts, real-time sentiment scoring, intent detection, and knowledge-based responses. Brands rely on NLP-powered chatbots and virtual assistants to reduce waiting time and offer 24/7 support. Customer service platforms use text classification and entity extraction to route requests more accurately. These tools improve customer experience and lower operating costs. Cloud deployment makes updates faster and supports multi-language processing, helping global businesses handle large customer bases. As organizations focus on customer retention and service quality, NLP adoption keeps rising.
- For instance, Google Dialogflow (both ES and CX) has default quotas for API requests per minute per project, typically in the hundreds or low thousands, which can be increased upon request to Google Cloud Support.
Growth of AI-Driven Analytics Across Unstructured Data Sources
Enterprises generate massive unstructured text from documents, medical notes, email, research papers, compliance reports, and user reviews. Cloud NLP applies machine learning to extract meaning from this data at scale, turning text into actionable information. Companies use NLP to detect risks, summarize information, and classify sensitive content for compliance. In healthcare, NLP assists in clinical decision support and electronic health records. In finance, it helps detect fraud patterns and analyze regulatory documents. Cloud platforms handle sudden data spikes, store large datasets, and deliver faster query processing. As more industries shift from manual text review to automated analytics, cloud NLP becomes essential.
Key Trends & Opportunities
Multilingual and Cross-Language NLP Expansion
Global commerce, cross-border e-commerce, and multicultural user bases increase demand for NLP tools that support many languages. Cloud NLP vendors are adding regional language models for Asian, Middle Eastern, and European markets. This creates a major opportunity in customer service, media platforms, and government services where translation, sentiment, and voice recognition are required. Enterprises also want localized chatbots and voice assistants that understand cultural context, slang, and dialects. Countries with fast digital adoption, such as India and Southeast Asia, drive growth for multilingual NLP. The market benefits from expanding internet penetration and rising digital payments, creating large volumes of multilingual text.
- For instance, Microsoft Translator provides neural models for more than 125 languages and dialects, including Hindi, Tamil, Arabic, and Turkish. Baidu’s speech recognition system handles over 7.5 billion voice queries per day in Mandarin and regional Chinese dialects, supporting e-commerce and smart devices.
Adoption of Generative AI and Large Language Models
Cloud providers now integrate large language models and generative AI into NLP tools for text creation, summarization, automated reporting, and code suggestions. Enterprises see value in faster content production, automated knowledge extraction, and smarter search functions. Generative NLP improves productivity in marketing, customer support, healthcare documentation, and education content. Vendors offer API-based services, so companies can run advanced NLP without training their own models. As businesses adopt AI policies and data governance frameworks, the use of generative NLP becomes more mainstream. This shift opens opportunities in content automation, enterprise knowledge management, and advanced text analytics.
- For instance, Microsoft's Azure AI Foundry provides access to more than 11,000 models from various partners, including OpenAI, Cohere, and Meta.
Key Challenges
Data Privacy, Compliance, and Security Concerns
Cloud NLP processes sensitive data such as customer identities, financial information, and medical records. Many organizations remain concerned about storing and analyzing such data on external cloud servers. Industries like banking and healthcare face strict compliance rules, which demand data encryption, access control, and audit trails. Any gaps in security can lead to legal risks and trust issues. Enterprises also worry about exposure of proprietary information when sending documents through cloud APIs. Vendors must offer strong security certifications, on-premise deployment options, private cloud support, and regional data centers to overcome these concerns.
Accuracy Limits in Complex and Domain-Specific Language
While NLP has advanced, it still struggles with sarcasm, slang, informal text, and mixed languages. Industries like healthcare, legal, and finance use specialized vocabulary that general NLP models may interpret incorrectly. Errors in sentiment analysis or document classification can lead to misinformation or poor decision-making. Training domain-specific NLP models requires large, labeled datasets, which many companies do not have. Multilingual accuracy is also uneven across languages. To overcome this, vendors must improve model training, add supervised learning options, and allow custom models tailored to industry-specific needs.
Regional Analysis
North America
North America holds 38% of the Cloud NLP market, driven by high cloud adoption, strong AI investments, and advanced digital infrastructure. U.S. enterprises lead in deploying NLP for chatbots, customer analytics, regulatory compliance, and fraud detection. Major cloud providers and NLP innovators headquartered in the region accelerate technology maturity and enterprise adoption. Banks, telecom operators, hospitals, and e-commerce platforms rely on cloud NLP to improve service quality and automate text-heavy workflows. Rapid integration of generative AI, multilingual models, and real-time analytics sustains market dominance and keeps North America the primary revenue hub.
Europe
Europe accounts for 27% of the Cloud NLP market, supported by fast digital transformation across finance, healthcare, manufacturing, and government sectors. Strict GDPR regulations increase demand for secure NLP platforms with strong data governance. Banks and insurers deploy NLP for risk modeling, document screening, and customer engagement. Healthcare providers use clinical text mining and EHR analytics for decision support. Multilingual support is a major driver, as NLP tools must handle English, French, German, Spanish, and regional languages. Expanding AI innovation centers, strong enterprise cloud spending, and public-sector modernization help Europe maintain a leading share.
Asia Pacific
Asia Pacific holds 24% of the market and records the highest growth rate due to rapid cloud adoption, booming e-commerce, and strong mobile penetration. China, India, Japan, and South Korea are major contributors, with enterprises using NLP for sentiment monitoring, voice assistants, smart customer care, and real-time translation. Telecom, retail, e-learning, and payments platforms generate huge volumes of unstructured data, increasing reliance on cloud-based analytics. Local language support drives adoption across diverse linguistic markets. Government investments in AI education and smart city programs, along with cloud expansion by global hyperscalers, boost regional momentum.
Latin America
Latin America captures 7% of the Cloud NLP market as organizations shift from legacy systems to cloud-based analytics and customer automation. Banks and fintech platforms use NLP for fraud detection, credit analytics, and customer chatbots. Retailers and telecom companies deploy sentiment monitoring to track customer feedback on social platforms. Brazil and Mexico lead with strong digital transformation and growing start-up ecosystems. Cloud subscription models reduce infrastructure costs for small and mid-sized enterprises. Expanding regional data centers and improved NLP support for Spanish and Portuguese help Latin America accelerate adoption and expand its market share.
Middle East & Africa
The Middle East & Africa region accounts for 4% of the market, with steady growth led by BFSI, telecom, government services, and energy sectors. Gulf countries deploy NLP in smart city initiatives, digital identity verification, and AI-based public services. Banks use cloud NLP for compliance, customer onboarding, and multilingual chatbots. Africa’s growth comes from mobile banking, e-learning, and social commerce platforms adopting text analytics. Expanding cloud data centers, rising internet penetration, and localized models for Arabic and African languages support long-term market development. The region shows high future potential as digital infrastructure strengthens
Market Segmentations:
By Type
- Statistical NLP
- Rule Based NLP
- Hybrid NLP
By Application
- Sentiment Analysis
- Data Extraction
- Risk And Threat Detection
- Automatic Summarization
- Content Management
- Language Scoring
- Others
By End-use
- BFSI
- IT & Telecommunication
- Healthcare
- Education
- Media & Entertainment
- Retail & E-commerce
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Cloud Natural Language Processing (NLP) market features strong competition among global cloud providers, AI platform companies, and specialized language technology vendors. Major players like Amazon Web Services, Google, Apple, IBM, Baidu, and IQVIA invest heavily in deep learning models, multilingual processing, generative AI, and real-time text analytics to strengthen their portfolios. These companies offer NLP through cloud APIs, enabling enterprises to deploy chatbots, voice assistants, translation tools, and sentiment engines without building models from scratch. Vendors also focus on industry-specific solutions for banking, telecom, healthcare, and e-commerce to increase adoption. Partnerships, acquisitions, and AI research collaborations help accelerate innovation and expand data processing capabilities. Pricing models, data security features, and language coverage remain key differentiators in the competitive space. Leading providers are also integrating explainable AI and domain-trained models to improve accuracy and meet compliance requirements, keeping competition intense and innovation continuous.
Key Player Analysis
- IQVIA
- Crayon Data
- Amazon Web Services, Inc.
- Health Fidelity
- Inbenta
- IBM Corporation
- Baidu Inc.
- Google LLC
- 3M
- Apple Inc.
Recent Developments
- In 2025, IQVIA NVIDIA’s GTC Paris keynote highlighted IQVIA’s AI agent work. The collaboration advances agentic AI for life sciences workflows. It supports large-scale NLP on cloud GPUs.
- In April 2025, Amazon Web Services (AWS) WBD Sports Europe launched Cycling Central Intelligence on AWS. It uses Amazon Bedrock, Comprehend, Textract, and Translate for natural-language queries. The system powers real-time insights for live broadcasts.
Report Coverage
The research report offers an in-depth analysis based on Type, Application, End-Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Cloud NLP adoption will increase as enterprises automate customer support and digital communication.
- Multilingual language models will expand, improving accuracy for regional languages and dialects.
- Generative AI will enhance summarization, content creation, and intelligent virtual assistant performance.
- Industry-specific NLP models will gain traction in healthcare, banking, legal, and education.
- Real-time sentiment and intent analysis will strengthen brand monitoring and customer experience.
- Speech-to-text and voice recognition tools will integrate deeper with smart devices and call centers.
- Privacy-focused NLP solutions will rise due to stricter compliance and data security needs.
- Low-code and API-based platforms will make NLP accessible to small and midsize businesses.
- Edge computing will support faster, localized NLP processing for telecom and IoT applications.
- Continuous advances in deep learning will reduce errors and improve contextual understanding across complex language tasks.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Cloud Natural Language Processing NLP Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Cloud Natural Language Processing NLP Market projected to grow between 2025 and 2032?
Which segment held the largest share in 2024?
What are the primary factors fueling the growth of the Cloud Natural Language Processing NLP Market?
Who are the leading companies in the Cloud Natural Language Processing NLP Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 15,240 million → 2032: USD 51,712 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Cloud Natural Language Processing Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Cloud Natural Language Processing Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Cloud Natural Language Processing Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Cloud Natural Language Processing Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Cloud Natural Language Processing Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Cloud Natural Language Processing Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Cloud Natural Language Processing Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Cloud Natural Language Processing Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 15,240 million → 2032: USD 51,712 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Cloud Natural Language Processing Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Cloud Natural Language Processing Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Cloud Natural Language Processing Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Cloud Natural Language Processing Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

