
Market Overview
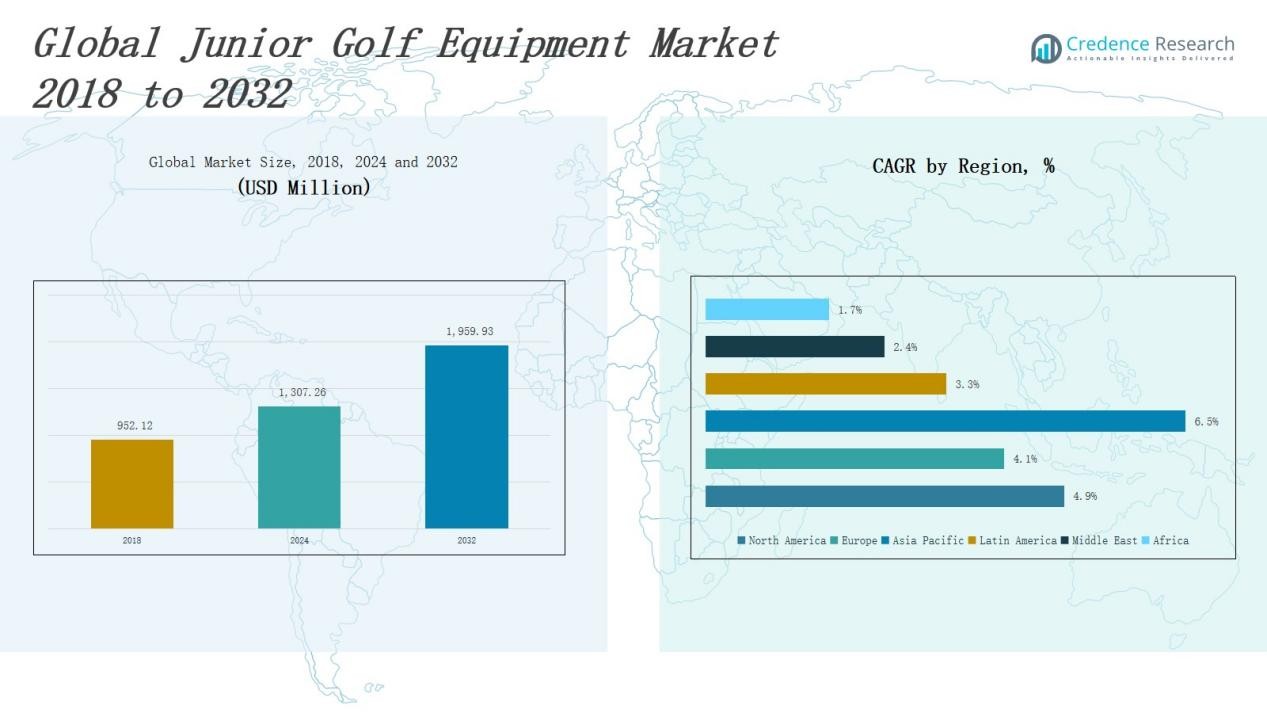
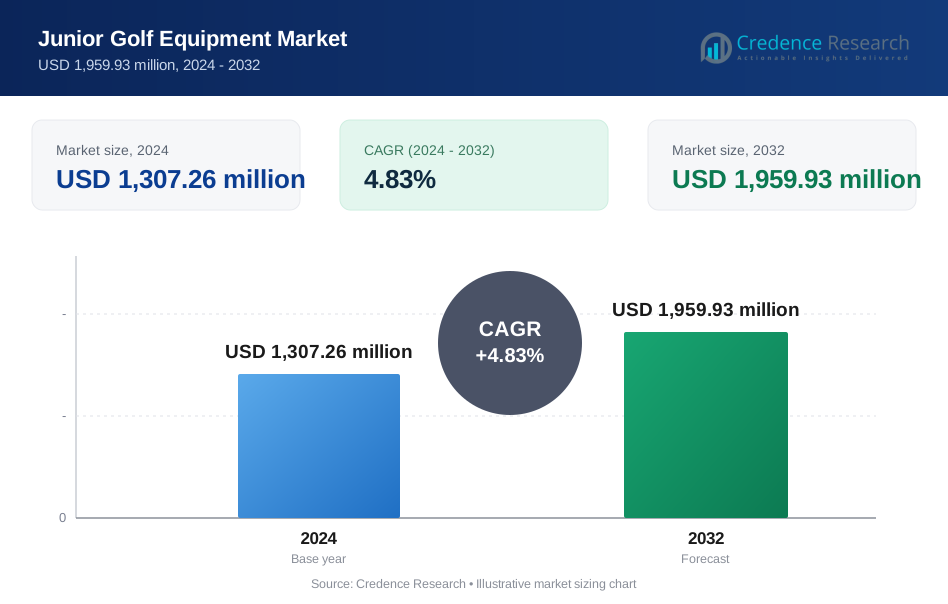
Junior Golf Equipment Market size was valued at USD 952.12 million in 2018 to USD 1,307.26 million in 2024 and is anticipated to reach USD 1,959.93 million by 2032, at a CAGR of 4.83% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Junior Golf Equipment Market Size 2024 | USD 1,307.26 Million |
| Junior Golf Equipment Market, CAGR | 4.83% |
| Junior Golf Equipment Market Size 2032 | USD 1,959.93 Million |
The Junior Golf Equipment Market features several prominent players driving innovation and growth, including Callaway Golf Company, TaylorMade Golf Company, Titleist, Ping, Cobra Golf, and Wilson Sporting Goods. These companies differentiate themselves through extensive product portfolios tailored for young golfers, advanced technology integration, and strong brand recognition. North America leads the market, commanding a dominant share of approximately 42.5%, supported by a well-established golfing culture, widespread junior golf programs, and significant investments in youth sports development. This regional leadership reinforces the competitive positioning of key players focusing on junior-specific equipment and accessories.
Market Insights
- The Junior Golf Equipment Market grew from USD 952.12 million in 2018 to USD 1,307.26 million in 2024 and is expected to reach USD 1,959.93 million by 2032, expanding steadily at a CAGR of 4.83%.
- Key players such as Callaway, TaylorMade, Titleist, Ping, Cobra Golf, and Wilson Sporting Goods drive growth through innovative, age-specific products and strong brand presence.
- Rising participation in junior golf programs, technological improvements in equipment design, and increasing awareness of outdoor activities propel demand for junior golf gear.
- The market faces challenges like the high cost of quality equipment, seasonal demand fluctuations, and limited awareness in emerging regions, which impact growth pace.
- North America leads with a 42.5% market share, supported by a strong golfing culture, widespread junior programs, and youth sports investments, followed by steady growth in Europe and rapid expansion in Asia Pacific.
Market Segment Insights
By Product Type:
Golf clubs dominate the junior golf equipment market, accounting for the largest share due to their critical role in player performance and customization options tailored for different age groups and skill levels. Golf balls follow, driven by demand for specialized balls designed for junior players’ swing speeds and distances. Golf bags, shoes, and apparel also contribute significantly, supported by increasing awareness of comfort, style, and functionality among young golfers. The ‘Others’ segment, including accessories such as gloves and training aids, holds a smaller yet growing share fueled by rising interest in comprehensive junior golf kits.
- For instance, Callaway Golf has developed lightweight, junior-friendly clubs with adjustable shafts to accommodate growing players and enhance usability.
By Age Group:
The 9-12 years age group holds the dominant market share, reflecting increased participation in golf programs and skill development activities during these formative years. This segment benefits from rising parental investment in quality equipment to support progression from beginner to intermediate levels. The 13-17 years segment follows closely, driven by competitive junior leagues and scholastic golf events. The younger age groups, under 5 years and 5-8 years, show steady growth as introductory programs expand, but they contribute a smaller portion due to simpler equipment needs and lower participation rates.
- PING offers the Prodi G Junior Clubs, a custom-engineered set with 11 clubs, designed using a unique fitting chart based on height and wrist-to-floor measurements. The brand also runs the “Get Golf Growing” program to provide no-cost adjustments, addressing growth challenges for junior players.
By Distribution Channel:
Sports retail stores lead the market in volume share, leveraging extensive physical presence and the ability to provide hands-on fitting and expert advice. Online stores have rapidly expanded their revenue share, supported by increased e-commerce adoption, convenience, and a wider variety of junior golf products. Golf academies and pro shops serve as important niche channels, offering tailored equipment and professional recommendations during training. Specialty stores and other channels maintain a modest share, driven by regional demand variations and exclusive product offerings.
Key Growth Driver
Rising Participation in Junior Golf Programs
Increased enrollment in junior golf academies, school leagues, and youth sports initiatives significantly fuels demand for junior golf equipment. Parents and coaches increasingly invest in age-appropriate, high-quality gear to nurture skills and encourage competitive play. This trend is especially strong in regions with established golfing cultures and growing youth sports infrastructure, driving volume growth across clubs, balls, and apparel specifically designed for juniors. The expanding grassroots programs ensure a steady influx of young players needing customized equipment, sustaining market momentum.
- For instance, Callaway Golf has expanded its junior club line with lightweight, ergonomically designed models that support skill development in young players.
Technological Advancements in Equipment Design
Innovations in materials and design tailored for juniors enhance performance, safety, and comfort, boosting market growth. Manufacturers increasingly integrate lightweight composites, ergonomic grips, and adjustable club features to accommodate varied skill levels and physical development stages. Enhanced customization options improve user experience, leading to higher adoption rates. These technological improvements also appeal to parents seeking durable and effective equipment, further expanding market demand and driving brand competition centered on innovation.
- For instance, Callaway offers adjustable hosel technology in their junior clubs, allowing customization of loft and lie angles to match skill progression and physical development.
Rising Awareness of Health and Outdoor Activities
Growing global emphasis on physical fitness and outdoor recreation motivates parents to encourage sports participation from an early age. Golf, perceived as a lifelong sport promoting discipline, focus, and social interaction, benefits from this shift. This awareness propels demand for junior golf equipment as families prioritize engaging children in healthy, structured activities. Campaigns promoting junior golf as a safe, low-impact sport contribute to market expansion, creating new opportunities for equipment manufacturers targeting health-conscious consumers.
Key Trend
Expansion of E-commerce and Digital Sales Channels
The junior golf equipment market witnesses rapid growth in online sales due to increasing internet penetration and consumer preference for convenient shopping. Digital platforms offer extensive product selections, competitive pricing, and detailed product information, attracting tech-savvy parents and young buyers. Virtual fitting tools and augmented reality apps enhance online purchasing confidence. This trend encourages manufacturers and retailers to strengthen digital presence and omnichannel strategies, accelerating market penetration and broadening geographic reach beyond traditional retail boundaries.
- For instance, Golfgarage.com, founded by pro golfer Rahul Bajaj, innovates with a trade-in policy for pre-owned golf clubs, enabling young golfers to trade in old equipment online to upgrade their sets conveniently.
Growing Focus on Sustainable and Eco-Friendly Products
Environmental concerns drive demand for sustainable junior golf equipment made from recycled or biodegradable materials. Brands adopting eco-friendly manufacturing processes and packaging gain competitive advantage among environmentally conscious consumers. This trend aligns with broader societal moves towards sustainability, creating opportunities for innovation in product design and material sourcing. Increasing transparency regarding product lifecycle impacts influences purchasing decisions, prompting market players to integrate sustainability as a core element of their growth and branding strategies.
- For instance, biodegradable golf balls like the AlbusGolf EcoBioball fully degrade in about 48 hours in water without leaving toxic residues, reducing pollution on courses and in water bodies.
Key Challenge
High Cost of Quality Junior Golf Equipment
Premium junior golf equipment often comes with high price points, limiting affordability for many consumers. This cost barrier affects adoption, especially in developing regions where disposable income is lower. Families may opt for cheaper alternatives, impacting market revenue potential for higher-end brands. Balancing quality, innovation, and cost remains a challenge for manufacturers aiming to broaden market accessibility while maintaining product standards. Price sensitivity necessitates diverse product portfolios and flexible pricing strategies to capture a wider consumer base.
Seasonal Demand Fluctuations and Regional Variability
The junior golf equipment market experiences significant seasonal and geographic demand variations due to weather conditions and regional popularity of golf. Cold climates and off-seasons reduce equipment purchases, creating inventory and sales planning challenges. Additionally, regions with limited golfing infrastructure or cultural interest show slower market growth. These fluctuations complicate supply chain management and revenue forecasting, requiring manufacturers and retailers to adopt adaptive strategies, diversify markets, and develop year-round engagement programs to stabilize demand.
Limited Awareness in Emerging Markets
In many emerging markets, lack of awareness about junior golf and its benefits constrains equipment demand. Limited access to training facilities and golf courses reduces participation, restricting market growth potential. Manufacturers face difficulties educating consumers and building brand recognition in these regions. Overcoming cultural barriers and investing in grassroots development programs are essential to expanding market reach. Companies must collaborate with local stakeholders and customize marketing strategies to increase visibility and adoption in untapped or underdeveloped markets.
Regional Analysis
North America:
North America holds a dominant position in the Junior Golf Equipment Market, with a market size growing from USD 417.36 million in 2018 to USD 567.10 million in 2024, and an expected increase to USD 852.59 million by 2032. The region’s CAGR of 4.9% reflects steady growth driven by a strong golfing culture, extensive junior programs, and significant investments in youth sports development. North America’s well-established infrastructure and widespread participation contribute to its leading market share, making it a key focus area for major manufacturers and distributors targeting junior golfers.
Europe:
Europe commands a substantial share of the Junior Golf Equipment Market, expanding from USD 273.59 million in 2018 to USD 362.26 million in 2024, with projections reaching USD 511.77 million by 2032. The region’s CAGR of 4.1% indicates consistent growth fueled by rising interest in junior golf, expanding academies, and increasing awareness of golf’s health benefits. Countries such as the UK, Germany, and France lead demand, supported by strong golfing traditions and government-backed youth sports initiatives, making Europe a critical market for industry players.
Asia Pacific:
Asia Pacific demonstrates the fastest growth among regions, with a CAGR of 6.5%, increasing its market size from USD 176.37 million in 2018 to USD 263.24 million in 2024 and projected to reach USD 448.84 million by 2032. This rapid expansion stems from growing urbanization, rising disposable incomes, and increased adoption of golf as a recreational sport. Emerging markets like China, India, and Southeast Asia are driving demand through growing junior golf programs and expanding golf course infrastructure, presenting significant opportunities for manufacturers and retailers.
Latin America:
Latin America’s Junior Golf Equipment Market shows moderate growth with a CAGR of 3.3%, increasing from USD 45.92 million in 2018 to USD 62.29 million in 2024 and expected to reach USD 82.88 million by 2032. Growth is supported by expanding golf participation in countries like Brazil and Argentina, along with increasing investments in youth sports. However, limited infrastructure and economic variability pose challenges, constraining rapid market expansion compared to more mature regions.
Middle East:
The Middle East maintains steady growth in the Junior Golf Equipment Market, with its size rising from USD 24.98 million in 2018 to USD 31.15 million in 2024 and forecasted to reach USD 38.86 million by 2032. The region’s CAGR of 2.4% reflects gradual adoption driven by investments in luxury golf resorts, junior golf academies, and increasing interest in sports tourism. Countries like the UAE and Saudi Arabia spearhead demand, although market growth remains slower due to relatively smaller golfing populations.
Africa:
Africa holds a small but gradually growing share of the Junior Golf Equipment Market, expanding from USD 13.91 million in 2018 to USD 21.22 million in 2024, with projections reaching USD 24.99 million by 2032. The region’s CAGR of 1.7% indicates slow but steady progress, driven by increased awareness and development of golf facilities in South Africa and Egypt. Limited infrastructure and economic challenges restrict rapid growth, but ongoing grassroots initiatives and emerging interest among youth provide a foundation for future expansion.
Market Segmentations:
By Product Type
- Golf Clubs
- Golf Balls
- Golf Bags
- Shoes
- Apparel
- Others
By Age Group
- Under 5 years
- 5-8 years
- 9-12 years
- 13-17 years
By Distribution Channel
- Sports Retail Stores
- Online Stores
- Golf Academies/Pro Shops
- Specialty Stores
- Others
By Region
- North America (U.S., Canada, Mexico)
- Europe (UK, France, Germany, Italy, Spain, Russia, Rest of Europe)
- Asia Pacific (China, Japan, South Korea, India, Australia, Southeast Asia, Rest of Asia Pacific)
- Latin America (Brazil, Argentina, Rest of Latin America)
- Middle East (GCC Countries, Israel, Turkey, Rest of Middle East)
- Africa (South Africa, Egypt, Rest of Africa)
Competitive Landscape
The Junior Golf Equipment Market features a competitive landscape driven by established global brands and emerging specialized players focusing on innovation and youth-specific product offerings. Leading companies such as Callaway Golf Company, TaylorMade Golf Company, Titleist, PING, Cobra Puma Golf, Wilson Sporting Goods, and U.S. Kids Golf dominate through extensive product portfolios, advanced technology integration, and strong distribution networks. These players invest heavily in research and development to design lightweight, ergonomic equipment tailored to different junior age groups and skill levels. They also leverage strategic partnerships with junior golf academies, professional tours, and retail channels to enhance brand visibility and consumer engagement. Additionally, increasing e-commerce adoption prompts companies to strengthen their digital presence and omnichannel strategies. Market entrants focus on niche segments, offering customizable and affordable alternatives to capture price-sensitive customers. Overall, competition centers on product innovation, brand loyalty, and expanding access to junior golfers globally, driving continuous market growth and diversification.
Key Players
- U.S. Kids Golf
- Callaway Golf Company
- TaylorMade Golf Company
- PING
- Tour Edge
- Wilson Sporting Goods
- Cobra Puma Golf
- Titleist
- Cleveland Golf
- Paragon
Recent Developments
- On January 17, 2025, PowerBilt Holdings announced a global licensing agreement with HEAD Sport. This partnership aims to introduce a comprehensive lineup of golf products, including adult and junior sets, golf balls, accessories, and premium golf bags.
- In July 2024, Ping introduced the next-generation Prodi G junior golf clubs. These clubs are designed specifically for young golfers, featuring lightweight materials and a comprehensive set that includes a titanium driver, fairway wood, hybrid, perimeter-weighted irons (6-9, PW), specialty wedges (54° S & 58° H), and tour-proven putter models (Anser and Tyne H).
- In May 2025, MGI Golf became the official electric caddy partner of the Hurricane Junior Golf Tour, providing advanced electric caddies to assist junior golfers during tournaments and enhance their on-course experience.
- On September 4, 2024, Topgolf Callaway Brands, the parent company formed after Callaway Golf Company's acquisition of Topgolf, announced plans to split into two separate publicly traded companies by late 2025.
- On June 3, 2019, OnCore Golf partnered with EPEC Golf to provide optimized golf equipment designed specifically for junior golfers.
Market Concentration & Characteristics
The Junior Golf Equipment Market exhibits a moderately concentrated structure dominated by a few key players with significant market shares. Leading companies maintain strong brand recognition and extensive distribution networks, enabling them to control major portions of the market. It features a blend of well-established global brands and smaller niche manufacturers focusing on specialized junior products. The market demands high-quality, customizable equipment tailored to various age groups and skill levels, encouraging innovation and product differentiation. Barriers to entry remain moderate due to the need for technological expertise and brand credibility. Regional variations influence market characteristics, with mature markets showing high competition and emerging regions presenting growth opportunities. It requires companies to balance product innovation, cost efficiency, and accessibility to capture diverse customer segments. The evolving preferences of young golfers and their guardians continue to shape competitive dynamics and market concentration patterns.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Age Group, Distribution Channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Junior Golf Equipment Market will experience steady growth driven by increasing youth participation in golf worldwide.
- Manufacturers will focus on developing lightweight and ergonomic equipment to meet the specific needs of junior players.
- Digital sales channels will expand, making junior golf equipment more accessible globally.
- Brands will invest in sustainable materials to address rising environmental concerns among consumers.
- Customized and adjustable products will gain popularity to accommodate different age groups and skill levels.
- Partnerships with golf academies and youth programs will strengthen brand loyalty and market penetration.
- Emerging markets will offer new growth opportunities as golf gains popularity in these regions.
- Technological innovation will enhance product performance and user experience for junior golfers.
- Price-sensitive consumers will drive demand for affordable yet quality junior golf equipment options.
- Marketing efforts will increasingly target parents and coaches to influence purchasing decisions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Junior Golf Equipment Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Junior Golf Equipment Market projected to grow between 2025 and 2032?
Which Junior Golf Equipment Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Junior Golf Equipment Market?
Who are the leading companies in the Junior Golf Equipment Market?
Which region commanded the largest share of the Junior Golf Equipment Market market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Junior Golf Equipment Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Junior Golf Equipment Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1,307.26 million → 2032: USD 1,959.93 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Junior Golf Equipment Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Junior Golf Equipment Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Junior Golf Equipment Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Junior Golf Equipment Market Drivers
- 3.3 Junior Golf Equipment Market Restraints & Challenges
- 3.4 Junior Golf Equipment Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Junior Golf Equipment Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Junior Golf Equipment Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Junior Golf Equipment category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Junior Golf Equipment Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Junior Golf Equipment Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Junior Golf Equipment. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Junior Golf Equipment Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – the historical period vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Junior Golf Equipment Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution (the historical period vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Junior Golf Equipment Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Junior Golf Equipment (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Junior Golf Equipment
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Junior Golf Equipment Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Junior Golf Equipment Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Junior Golf Equipment Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Junior Golf Equipment Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Junior Golf Equipment Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Junior Golf Equipment Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Junior Golf Equipment Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Junior Golf Equipment Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
