
Market Overview:
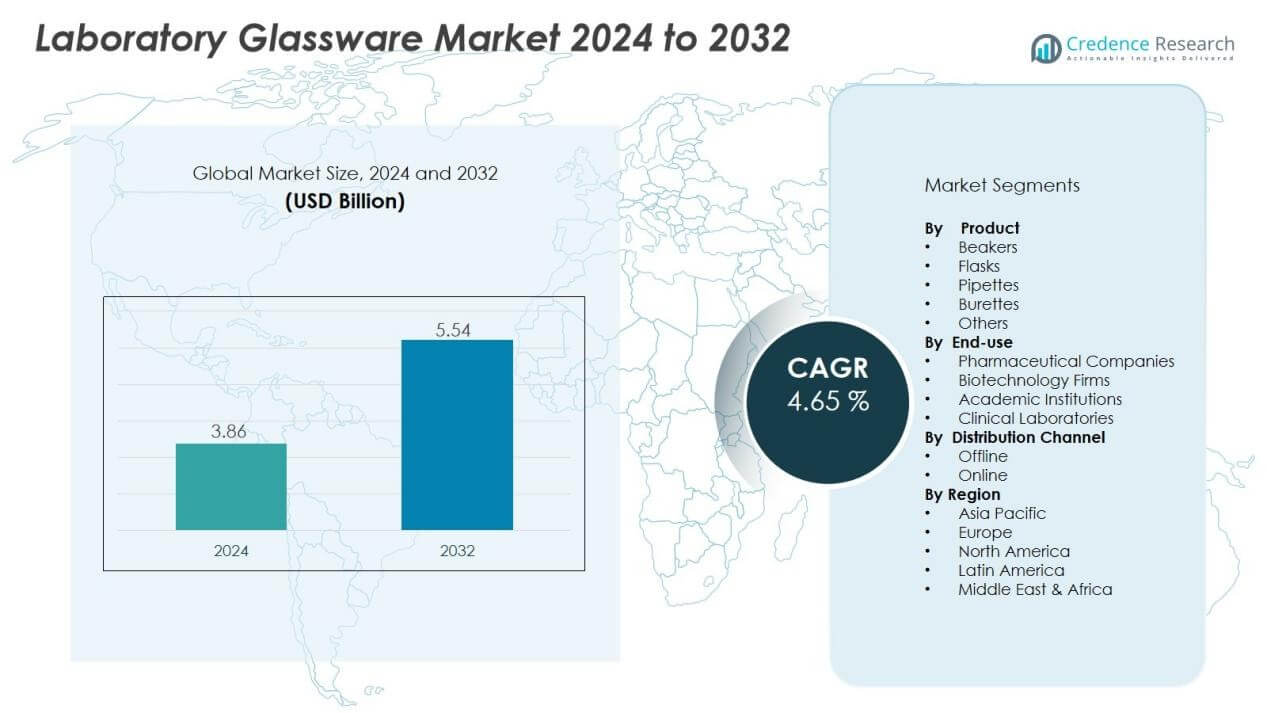
The laboratory glassware market size was valued at USD 3.86 billion in 2024 and is anticipated to reach USD 5.54 billion by 2032, at a CAGR of 4.65% during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Laboratory Glassware Market Size 2024 | USD 3.86 Billion |
| Laboratory Glassware Market, CAGR | 4.65% |
| Laboratory Glassware Market Size 2032 | USD 5.54 Billion |
Growth in this market is mainly fueled by increasing investments in R&D, rising demand for advanced healthcare infrastructure, and expansion of pharmaceutical drug discovery. The growing use of customized and reusable glassware, coupled with stricter quality standards in laboratory operations, strengthens adoption across industries. Furthermore, the shift toward eco-friendly and sustainable materials supports demand, as laboratories seek alternatives to single-use plastics. The strong role of education and research institutions further contributes to consistent market expansion.
Regionally, North America leads the laboratory glassware market due to robust healthcare and research infrastructure, supported by significant funding for scientific studies. Europe follows closely, driven by strict regulatory standards and strong university research networks. Asia-Pacific is emerging rapidly, propelled by increased investments in healthcare, pharmaceuticals, and academic research, particularly in countries like China and India. Latin America and the Middle East & Africa show gradual growth, supported by expanding healthcare and research capabilities.
Market Insights:
- The laboratory glassware market was valued at USD 3.86 billion in 2024 and is expected to reach USD 5.54 billion by 2032, growing at a CAGR of 4.65%.
- Rising demand from pharmaceutical and biotechnology industries is driving adoption, with glassware essential for drug discovery, vaccine development, and diagnostic advancements.
- Academic and research institutions continue to play a major role in consumption, using glassware extensively for experiments, demonstrations, and scientific training.
- Stricter quality standards and regulatory compliance requirements fuel replacement demand, as laboratories seek glassware with superior durability and chemical resistance.
- Sustainability trends are creating opportunities, with laboratories shifting from plastics toward eco-friendly, reusable, and long-lasting glassware solutions.
- Challenges include fragility, higher maintenance costs, competition from alternative materials like plastics, and rising raw material prices impacting profitability.
- Regionally, North America leads with 38% market share, Europe follows with 29% supported by strong regulations, and Asia-Pacific holds 24% with rapid growth in healthcare and education sectors.
Market Drivers:
Rising Demand from Pharmaceutical and Biotechnology Research:
The laboratory glassware market benefits from the continuous growth of pharmaceutical and biotechnology research. Drug discovery, vaccine development, and diagnostic advancements require precise and durable glassware for experimentation. It plays a critical role in ensuring accuracy during chemical reactions and biological testing. The sector’s rising R&D budgets directly increase glassware consumption across global laboratories.
- For Instance, Pfizer utilized billions of Type I borosilicate glass vials to support the unprecedented initial scale-up and global distribution of its COVID-19 mRNA vaccine, COMIRNATY, starting in 2020 and 2021.
Expanding Role of Academic and Research Institutions in Scientific Studies:
Academic and research institutions significantly drive the laboratory glassware market by using glassware for experiments, demonstrations, and applied research. Universities and colleges remain key consumers, supporting consistent demand across regions. It provides essential tools for practical learning in chemistry, biology, and physics. Growth in global higher education and research funding further strengthens this segment’s contribution.
- For instance, Benguet State University in the Philippines allocated ₱885,190 for laboratory glassware procurement in 2024, ensuring delivery of hundreds of glassware items within fifteen calendar days for student and faculty research projects.
Increasing Focus on Quality Standards and Regulatory Compliance in Laboratories:
The laboratory glassware market is influenced by rising quality standards and strict regulatory requirements in clinical and industrial labs. High precision in experiments demands glassware with superior chemical resistance and clarity. It supports compliance with safety protocols, ensuring reliability in research outcomes. This factor motivates laboratories to upgrade equipment regularly, creating steady replacement demand.
Shift Toward Eco-Friendly, Reusable, and Durable Laboratory Solutions:
Sustainability trends are reshaping the laboratory glassware market, encouraging the use of eco-friendly and reusable products. Laboratories are shifting away from plastics to reduce waste and align with environmental goals. It offers long-term durability, lowering operational costs while supporting green initiatives. Manufacturers are innovating with advanced glass formulations to meet both performance and sustainability needs.
Market Trends:
Adoption of Advanced Materials and Technology Integration in Laboratory Glassware:
The laboratory glassware market is witnessing a strong trend toward advanced materials and technology integration. Manufacturers are introducing glassware with higher chemical resistance, improved heat tolerance, and better durability to meet modern laboratory requirements. It is increasingly being paired with digital tools such as smart sensors and automated systems, enabling accurate measurements and reducing human error. Research laboratories prefer glassware with enhanced coatings that resist scratches and contamination. The trend also reflects rising demand for specialized glassware in high-end pharmaceutical and biotechnology applications. This shift highlights how innovation in material science is driving long-term adoption across industries.
- For instance, in July 2023, DWK Life Sciences launched its DURAN® YOUTILITY laboratory bottle series with enhanced chemical-resistant borosilicate 3.3 glass, which withstands thermal shocks up to 160°C and features RFID-enabled digital tracking for inventory management.
Growing Emphasis on Sustainability, Customization, and Global Research Expansion:
The laboratory glassware market is also shaped by sustainability and customization trends. Laboratories are prioritizing reusable and recyclable glassware to align with environmental goals and reduce reliance on plastics. It is also moving toward customized designs that fit specific experimental requirements, enhancing efficiency in both academic and industrial research. Global expansion of healthcare, biotech, and academic institutions, particularly in emerging economies, is creating fresh opportunities for glassware suppliers. Manufacturers are responding by offering flexible production capabilities and region-specific product designs. This reflects a broader trend where sustainability, tailored solutions, and global research growth intersect to influence future market dynamics.
- For instance, Corning Incorporated achieved an 87% landfill diversion rate by diverting 403,330 metric tons of waste in 2024, while also being named ENERGY STAR Partner of the Year for the 11th consecutive year by the U.S. Environmental Protection Agency.
Market Challenges Analysis:
High Fragility, Maintenance Costs, and Competition from Alternative Materials:
The laboratory glassware market faces significant challenges due to the fragile nature of glass products. Breakage during handling, transportation, and regular use increases replacement costs for laboratories. It limits adoption in facilities seeking cost-efficient and durable alternatives. Plastics and composite materials, which offer lower cost and higher resistance to damage, present strong competition. Rising expenses for cleaning and sterilization also add to overall maintenance costs. These factors collectively restrict market growth and force manufacturers to innovate more durable solutions.
Regulatory Barriers, Supply Chain Issues, and Rising Raw Material Costs:
The laboratory glassware market is also challenged by strict regulatory standards and fluctuating raw material prices. Compliance with safety and quality regulations requires continuous investment in manufacturing processes. It faces added strain from supply chain disruptions that delay delivery schedules and increase procurement costs. Rising prices of raw materials such as silica and borosilicate glass affect profit margins for producers. Smaller manufacturers struggle to remain competitive under these pressures, leading to market consolidation. Global instability in trade policies further compounds these challenges, limiting smooth operations for suppliers.
Market Opportunities:
Rising Investments in Research, Healthcare, and Biotechnology Sectors:
The laboratory glassware market holds strong opportunities through rising global investments in research and healthcare. Governments and private organizations are expanding budgets for pharmaceutical development, academic research, and biotechnology. It benefits directly from this surge, as laboratories require high-precision glassware for advanced testing and analysis. The growing demand for vaccines, diagnostics, and drug discovery strengthens the need for durable and accurate equipment. Expansion of clinical research organizations also contributes to higher adoption. This creates a steady pipeline of demand across multiple industries.
Innovation in Sustainable Designs and Emerging Market Expansion:
The laboratory glassware market also gains opportunities from sustainable designs and emerging economies. Manufacturers focusing on eco-friendly, reusable, and customized glassware can meet rising demand from laboratories with strict environmental goals. It benefits from growing adoption of specialized glassware in Asia-Pacific, Latin America, and the Middle East, where healthcare and education sectors are rapidly expanding. Customization in product design allows suppliers to target niche requirements across industries. Growth of smart laboratory solutions further opens avenues for integrating glassware with digital tools. These opportunities highlight the importance of innovation and regional expansion for long-term success.
Market Segmentation Analysis:
By Product:
The laboratory glassware market by product is divided into beakers, flasks, pipettes, burettes, and others. Beakers and flasks dominate due to their wide usage in chemical, pharmaceutical, and academic research. It supports critical tasks such as mixing, heating, and storage of samples. Pipettes and burettes maintain steady demand from laboratories requiring accurate measurement and titration processes. Specialty glassware is also gaining importance in biotechnology and advanced pharmaceutical research.
- For instance, Sartorius AG launched the Picus 2 electronic pipette in September 2023, which features a digital readout for precise liquid handling and a multichannel capability-processing up to 12 samples simultaneously, improving workflow efficiency for research labs.
By End-use:
The laboratory glassware market by end-use covers pharmaceutical companies, biotechnology firms, academic institutions, and clinical laboratories. Pharmaceutical and biotechnology firms lead demand due to extensive drug discovery and testing requirements. It plays a key role in supporting research accuracy and safety standards. Academic institutions remain important consumers, ensuring consistent demand for teaching and experimental activities. Clinical laboratories are expanding usage due to rising diagnostic applications and healthcare advancements.
- For instance, Nalgene polypropylene labware can be autoclaved for 20 minutes at 121 °C without compromising performance. 20.
By Distribution Channel:
The laboratory glassware market by distribution channel is segmented into offline and online sales. Offline distribution through specialty stores and authorized dealers continues to dominate, ensuring quality assurance and reliability. It is complemented by online platforms, which are growing due to convenience and wider product availability. Laboratories prefer digital channels for bulk procurement and competitive pricing. Global suppliers are strengthening both offline and online networks to expand reach.
Segmentations:
By Product:
- Beakers
- Flasks
- Pipettes
- Burettes
- Others
By End-use:
- Pharmaceutical Companies
- Biotechnology Firms
- Academic Institutions
- Clinical Laboratories
By Distribution Channel:
- Offline
- Online
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis:
North America:
North America held 38% market share of the laboratory glassware market in 2024, supported by strong research infrastructure. The region benefits from advanced healthcare facilities, pharmaceutical giants, and extensive biotechnology investments. It witnesses consistent demand from universities, clinical laboratories, and R&D centers that require high-quality glassware for testing and experiments. Government funding and private sector research programs sustain steady adoption across applications. Manufacturers in the region focus on premium, durable glassware that meets strict regulatory standards. Strong supply chains and innovative product development further secure North America’s leadership in this sector.
Europe:
Europe accounted for 29% market share of the laboratory glassware market in 2024, driven by strict regulatory frameworks. The region emphasizes compliance with quality and safety standards in pharmaceutical and clinical laboratories, creating sustained demand for glassware. It is further supported by strong academic networks and leading universities conducting advanced research in life sciences. Germany, France, and the U.K. remain the key contributors to regional growth. Glassware manufacturers in Europe focus on sustainable and eco-friendly designs to align with environmental targets. The presence of established laboratory suppliers strengthens regional competitiveness.
Asia-Pacific :
Asia-Pacific held 24% market share of the laboratory glassware market in 2024, reflecting rapid expansion in healthcare and education. Rising government investments in medical research and the growing number of universities drive consumption. It benefits from the expansion of pharmaceutical and biotechnology industries in China, India, and Japan. Increasing awareness of quality standards motivates laboratories to shift from low-cost plastics to durable glassware. Local manufacturers are scaling up production to meet rising demand while global suppliers expand operations in the region. Asia-Pacific’s large population and growing research capacity position it as a key growth hub.
Key Player Analysis:
- Astraglass Innovations
- Borosil Limited
- Bellco Glass
- Corning Incorporated
- DWK Life Sciences
- Crystalgen, Inc.
- Eppendorf AG
- Hamilton Glass
- Gerresheimer AG
- Merck KGaA
- METTLER TOLEDO
Competitive Analysis:
The laboratory glassware market is characterized by strong competition among global and regional players. Key participants include Astraglass Innovations, Borosil Limited, Bellco Glass, Corning Incorporated, DWK Life Sciences, Crystalgen, Inc., and Eppendorf AG. These companies focus on product innovation, durability, and precision to meet evolving laboratory requirements. It is shaped by manufacturers investing in advanced materials and coatings to enhance performance and longevity. Partnerships with research institutions and healthcare organizations strengthen market positioning and expand product reach. Companies also emphasize sustainable designs and reusable solutions to align with rising environmental standards. Competitive strategies include global expansion, digital sales growth, and portfolio diversification to serve pharmaceutical, biotechnology, and academic institutions effectively.
Recent Developments:
- In December 2023, Astraglass Innovations was launched following the merger of Andrews Glass and Quark Glass, establishing a new brand identity focused on innovation in scientific glassware.
- In December 2023, Borosil Limited completed a composite Scheme of Arrangement, demerging its Scientific and Industrial Products business into Borosil Scientific Limited, which subsequently became a publicly listed entity.
- In April 2025, Borosil Limited incorporated Stylenest India Limited as a wholly-owned subsidiary, targeting growth in the consumer products market.
Report Coverage:
The research report offers an in-depth analysis based on Product, End-use, Distribution Channel and Region. It details leading Market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current Market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven Market expansion in recent years. The report also explores Market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on Market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the Market.
Future Outlook:
- The laboratory glassware market will experience steady demand from pharmaceutical, biotechnology, and clinical research sectors.
- It will benefit from rising investments in healthcare infrastructure and global drug discovery initiatives.
- Sustainability goals will drive laboratories to adopt reusable and eco-friendly glassware products.
- Manufacturers will focus on innovative coatings and advanced formulations to enhance durability and precision.
- It will see increased integration with digital systems and smart laboratory solutions for improved efficiency.
- Academic and research institutions will remain consistent consumers, supporting long-term market stability.
- Growth in Asia-Pacific and Latin America will expand supplier opportunities in emerging economies.
- Regulatory standards will push laboratories to upgrade equipment, ensuring compliance and quality control.
- It will face ongoing competition from alternative materials, but high precision will sustain demand for glassware.
- Collaborations between manufacturers and research organizations will accelerate product development and adoption worldwide.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expansion of Pharmaceutical and Biotechnology Research
Ongoing growth in pharmaceutical and biotechnology R&D, including drug discovery and vaccine development, requires precise and durable laboratory glassware for experimentation and testing, directly increasing market demand.
Rising Investments in Healthcare Infrastructure
Governments and private organizations are boosting funding for healthcare facilities and research centers, leading to higher procurement of laboratory glassware to support advanced diagnostics and clinical research.
Stricter Quality Standards and Regulatory Compliance
Increasingly rigorous quality and safety regulations in laboratories drive the need for high-quality, chemically resistant glassware, prompting regular upgrades and replacement cycles.
Shift Toward Eco-Friendly and Reusable Solutions
Sustainability initiatives are encouraging laboratories to transition from single-use plastics to reusable and eco-friendly glassware, supporting long-term market growth as institutions align with environmental goals.
Growth of Academic and Research Institutions
The expansion of higher education and research funding globally ensures steady demand for laboratory glassware, as universities and research centers require reliable equipment for teaching, experimentation, and scientific training.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Laboratory Glassware Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Laboratory Glassware Market projected to grow between 2024 and 2032?
Which Laboratory Glassware Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Laboratory Glassware Market?
Who are the leading companies in the Laboratory Glassware Market?
Which region commanded the largest share of the Laboratory Glassware Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-use
- 1.2.1 Pharmaceutical Companies
- 1.2.2 Biotechnology Firms
- 1.2.3 Academic Institutions
- 1.2.4 Clinical Laboratories
- 1.3 By Product
- 1.3.1 Beakers
- 1.3.2 Flasks
- 1.3.3 Pipettes
- 1.3.4 Burettes
- 1.3.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 3.86 billion → 2032: USD 5.54 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Laboratory Glassware Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Laboratory Glassware Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Laboratory Glassware Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Laboratory Glassware Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Laboratory Glassware Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Laboratory Glassware Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Laboratory Glassware Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Laboratory Glassware Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 3.86 billion → 2032: USD 5.54 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Laboratory Glassware Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-use - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Pharmaceutical Companies
- 12.3.7.2 Biotechnology Firms
- 12.3.7.3 Academic Institutions
- 12.3.7.4 Clinical Laboratories
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Beakers
- 12.4.7.2 Flasks
- 12.4.7.3 Pipettes
- 12.4.7.4 Burettes
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Laboratory Glassware End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Laboratory Glassware Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Laboratory Glassware Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Laboratory Glassware Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Astraglass Innovations
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Borosil Limited
- 18.4 Bellco Glass
- 18.5 Corning Incorporated
- 18.6 DWK Life Sciences
- 18.7 Crystalgen, Inc.
- 18.8 Eppendorf AG
- 18.9 Hamilton Glass
- 18.10 Gerresheimer AG
- 18.11 Merck KGaA
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

