
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
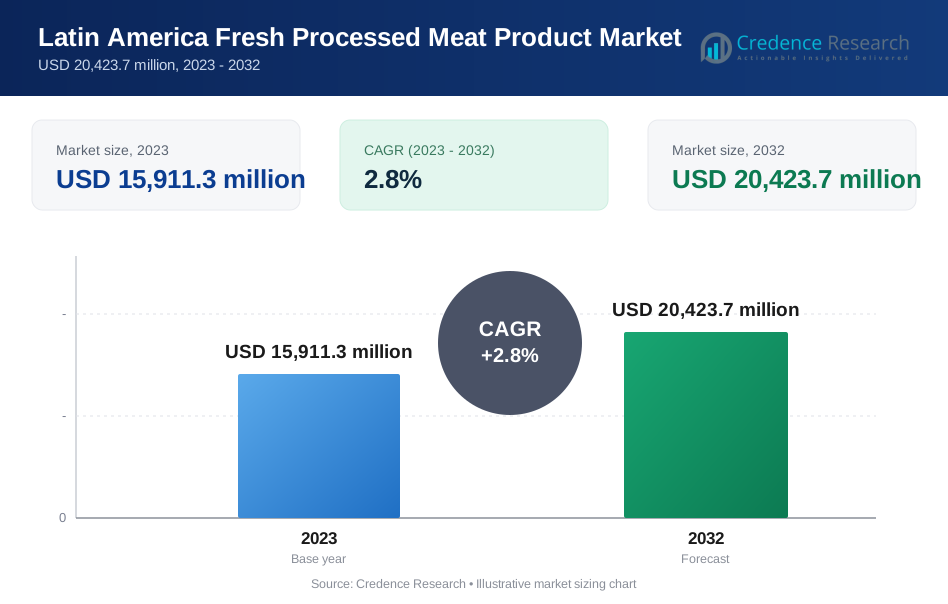
| Latin America Fresh Processed Meat Product Market Size 2023 | USD 15,911.3 million |
| Latin America Fresh Processed Meat Product Market, CAGR | 2.8% |
| Latin America Fresh Processed Meat Product Market Size 2032 | USD 20,423.7 million |
Market Overview
The Latin America Fresh Processed Meat Product Market is projected to grow from USD 15,911.3 million in 2023 to an estimated USD 20,423.7 million by 2032, with a compound annual growth rate (CAGR) of 2.8% from 2024 to 2032. This growth is driven by rising consumer demand for convenient and ready-to-cook food options, along with an increasing focus on processed meat products that maintain freshness while offering extended shelf life.
Key drivers of this market include the growing trend of urbanization, which increases the demand for ready-to-eat foods, and an expanding middle class with higher disposable incomes. Additionally, consumer preferences are shifting toward protein-rich diets, driving demand for meat products. Innovations in processing technologies and packaging, aimed at enhancing product quality and shelf life, are also fueling growth in the market. However, concerns related to health and the environmental impact of meat production may restrain the market to some extent.
Geographically, Brazil holds a dominant position in the Latin American market, followed by Mexico and other South American countries. The region's strong agricultural base and established meat industry play a significant role in supporting market growth. Key players in this market include BRF S.A., JBS S.A., and Tyson Foods, among others, who are focusing on expanding their product portfolios and enhancing distribution channels to meet the rising demand for fresh processed meat products.
Market Insights
- The Latin America Fresh Processed Meat Product Market is projected to grow from USD 15,911.3 million in 2023 to USD 20,423.7 million by 2032, at a CAGR of 2.8% from 2024 to 2032.
- Key drivers include urbanization, rising disposable incomes, and growing consumer preference for convenient, ready-to-eat, and protein-rich meat products.
- Health concerns and the environmental impact of meat production are restraints, potentially limiting market growth despite increasing demand for processed meat products.
- Brazil leads the market, followed by Mexico and other South American countries, benefiting from strong agricultural sectors and high meat consumption.
- Innovations in processing technologies and packaging are improving product shelf life and quality, enhancing market prospects.
- The rising trend of clean-label and organic meat products is gaining momentum, responding to consumer preferences for healthier and more natural options.
- The foodservice and home cooking applications dominate the market, with significant growth in ready-to-eat meals driven by busy lifestyles across Latin America
Market Drivers
Rising Demand for Health-Conscious Processed Meat Options
In recent years, the Latin America Fresh Processed Meat Product Market has witnessed a significant shift driven by increasing health consciousness. Consumers are becoming more aware of the potential health risks associated with traditional processed meats, such as high sodium, fat, and preservative content, resulting in a growing demand for healthier alternatives like low-fat, low-sodium, and organic options. For instance, there has been a notable increase in the consumption of poultry products, particularly chicken and turkey, which are often perceived as healthier options compared to red meats like beef. Data indicates that chicken is now the most consumed protein across several Latin American countries, such as Brazil and Colombia, largely due to its affordability and versatility in various culinary preparations. Lean cuts of pork are also gaining traction as consumers seek lower-fat options that still provide high protein content without the associated health risks linked to beef. Manufacturers are responding by offering products with reduced levels of sodium, fat, and additives, catering to the health-conscious consumer.
Convenience and Ready-to-Eat Products
Convenience remains a pivotal trend in the Latin America Fresh Processed Meat Product Market, propelled by the region's growing urban population and fast-paced lifestyles. The demand for easy-to-prepare food options is rising, making fresh processed meats, which offer convenience through pre-packaged and ready-to-eat or ready-to-cook products, increasingly popular. For instance, pre-cooked sausages, deli meats, marinated meats, and vacuum-sealed portions save consumers time while still providing nutritious meals. This is especially prevalent in urban centers where work schedules and active lifestyles limit meal preparation time. As disposable incomes rise in countries like Brazil and Mexico, consumers are more willing to invest in high-quality, ready-to-eat processed meat products, often available in modern retail formats and online platforms.
Sustainability and Ethical Sourcing
Sustainability and ethical sourcing are becoming increasingly important trends in the Latin America Fresh Processed Meat Product Market. Consumers are more concerned about the environmental impact of meat production, including deforestation, greenhouse gas emissions, and water usage, driving demand for sustainably sourced meat products from companies committed to reducing their environmental footprint. Ethical sourcing is another key consideration, with consumers seeking meat products from animals raised under humane conditions, such as free-range, grass-fed, and certified organic meats. For instance, Brazil has made significant strides in promoting sustainable beef production, with numerous initiatives aimed at reducing deforestation in the Amazon and improving cattle ranching practices. As sustainability becomes a more prominent issue in the region, the fresh processed meat market is likely to see a rise in the adoption of sustainable production methods, catering to the growing demand for eco-conscious and ethically produced meat products.
Expansion of E-Commerce and Online Grocery Channels
The expansion of e-commerce and online grocery platforms is significantly shaping the Latin America Fresh Processed Meat Product Market. With increased internet penetration and smartphone usage across the region, more consumers are turning to online channels to purchase food, including fresh processed meat products, a trend accelerated by the COVID-19 pandemic. For instance, online retailers and supermarkets now offer a wide range of fresh processed meat products that can be ordered and delivered directly to consumers’ homes, creating new opportunities for meat producers to reach consumers who may not have easy access to traditional brick-and-mortar stores. Many online platforms offer flexible delivery options, including same-day or next-day delivery, contributing to market growth. Meat producers and retailers are investing in e-commerce platforms and digital marketing strategies to engage with consumers and expand their customer base, further solidifying e-commerce as a key distribution channel in Latin America.
Market Trends
Rising Demand for Health-Conscious Processed Meat Options
In recent years, the Latin America Fresh Processed Meat Product Market has witnessed a significant shift driven by increasing health consciousness. Consumers are becoming more aware of the potential health risks associated with traditional processed meats, such as high sodium, fat, and preservative content, resulting in a growing demand for healthier alternatives like low-fat, low-sodium, and organic options. For instance, there has been a notable increase in the consumption of poultry products, particularly chicken and turkey, which are often perceived as healthier options compared to red meats like beef. Data indicates that chicken is now the most consumed protein across several Latin American countries, such as Brazil and Colombia, largely due to its affordability and versatility in various culinary preparations. Lean cuts of pork are also gaining traction as consumers seek lower-fat options that still provide high protein content without the associated health risks linked to beef. Manufacturers are responding by offering products with reduced levels of sodium, fat, and additives, catering to the health-conscious consumer.
Convenience and Ready-to-Eat Products
Convenience remains a pivotal trend in the Latin America Fresh Processed Meat Product Market, propelled by the region's growing urban population and fast-paced lifestyles. The demand for easy-to-prepare food options is rising, making fresh processed meats, which offer convenience through pre-packaged and ready-to-eat or ready-to-cook products, increasingly popular. For instance, pre-cooked sausages, deli meats, marinated meats, and vacuum-sealed portions save consumers time while still providing nutritious meals. This is especially prevalent in urban centers where work schedules and active lifestyles limit meal preparation time. As disposable incomes rise in countries like Brazil and Mexico, consumers are more willing to invest in high-quality, ready-to-eat processed meat products, often available in modern retail formats and online platforms.
Sustainability and Ethical Sourcing
Sustainability and ethical sourcing are becoming increasingly important trends in the Latin America Fresh Processed Meat Product Market. Consumers are more concerned about the environmental impact of meat production, including deforestation, greenhouse gas emissions, and water usage, driving demand for sustainably sourced meat products from companies committed to reducing their environmental footprint. Ethical sourcing is another key consideration, with consumers seeking meat products from animals raised under humane conditions, such as free-range, grass-fed, and certified organic meats. For instance, Brazil has made significant strides in promoting sustainable beef production, with numerous initiatives aimed at reducing deforestation in the Amazon and improving cattle ranching practices. As sustainability becomes a more prominent issue in the region, the fresh processed meat market is likely to see a rise in the adoption of sustainable production methods, catering to the growing demand for eco-conscious and ethically produced meat products.
Expansion of E-Commerce and Online Grocery Channels
The expansion of e-commerce and online grocery platforms is significantly shaping the Latin America Fresh Processed Meat Product Market. With increased internet penetration and smartphone usage across the region, more consumers are turning to online channels to purchase food, including fresh processed meat products, a trend accelerated by the COVID-19 pandemic. For instance, online retailers and supermarkets now offer a wide range of fresh processed meat products that can be ordered and delivered directly to consumers’ homes, creating new opportunities for meat producers to reach consumers who may not have easy access to traditional brick-and-mortar stores. Many online platforms offer flexible delivery options, including same-day or next-day delivery, contributing to market growth. Meat producers and retailers are investing in e-commerce platforms and digital marketing strategies to engage with consumers and expand their customer base, further solidifying e-commerce as a key distribution channel in Latin America.
Market Challenges
Health Concerns and Changing Dietary Preferences
One of the most significant challenges facing the Latin America Fresh Processed Meat Product Market is the growing health concerns surrounding the consumption of processed meats. Research linking the high consumption of processed meats with increased risks of chronic diseases, such as heart disease, high blood pressure, and certain types of cancer, has caused many consumers to reevaluate their dietary choices. As awareness of the health risks associated with processed meats continues to rise, more consumers are shifting towards plant-based alternatives and leaner, fresher protein sources. This trend is particularly strong among younger generations, such as millennials and Gen Z, who are more likely to follow plant-based or flexitarian diets, further decreasing the demand for traditional processed meat products. These changing dietary preferences put pressure on producers to innovate and diversify their product offerings, creating healthier alternatives that still appeal to health-conscious consumers. While there is a growing demand for low-sodium, low-fat, and organic options, these products often require significant adjustments to production processes, which can be costly. As a result, meat processors must balance consumer demand for healthier options with maintaining product quality, taste, and affordability, all of which present significant challenges for the industry.
Supply Chain and Raw Material Costs
Another challenge facing the Latin America Fresh Processed Meat Product Market is the volatility in the supply chain and rising costs of raw materials. Latin American countries rely heavily on both domestic and international supply chains for sourcing raw materials like meat, feed, and packaging. Disruptions caused by factors such as climate change, political instability, inflation, and fluctuating demand for meat exports can significantly impact the availability and cost of these materials. For instance, severe weather conditions, such as droughts or floods, can negatively affect livestock farming, leading to supply shortages and price hikes. The rising cost of raw materials can, in turn, lead to higher production costs, which may be passed on to consumers through increased product prices. This, in turn, can reduce the affordability and competitiveness of fresh processed meat products, particularly in countries with high levels of price sensitivity. Moreover, manufacturers may face challenges in ensuring a consistent supply of quality meat, as well as adhering to increasingly strict regulations related to food safety and sustainability, which require additional investments in sourcing and production practices. Consequently, managing supply chain risks and controlling raw material costs remains a key challenge for producers operating in the region.
Market Opportunities
Expansion of Healthier Product Offerings
One of the most significant opportunities in the Latin America Fresh Processed Meat Product Market lies in the development of healthier and more sustainable meat options. As consumer demand shifts towards products with reduced sodium, fat, and preservatives, there is a growing market for processed meat products that align with healthier dietary trends. This includes the introduction of low-fat, low-sodium, organic, and clean-label processed meats. By focusing on these healthier alternatives, manufacturers can capture the attention of health-conscious consumers who seek convenient, protein-rich products without compromising on nutritional value. Additionally, the growing popularity of plant-based meat substitutes presents an opportunity for meat processors to diversify their product lines and explore hybrid options that combine both plant-based and animal-based ingredients, offering consumers a broader selection of healthier, eco-friendly choices.
E-commerce and Online Retail Expansion
With the increasing adoption of e-commerce and online grocery shopping in Latin America, there is a significant opportunity for fresh processed meat producers to tap into the expanding digital marketplace. The growing trend of consumers purchasing food products online, especially in urban areas, allows meat processors to expand their reach and target a broader consumer base. E-commerce platforms offer convenience, flexibility, and direct-to-consumer delivery, all of which are highly valued by today's busy consumers. By strengthening their online presence and establishing partnerships with e-retailers, fresh processed meat companies can leverage this growing distribution channel to increase sales and enhance consumer loyalty.
Market Segmentation Analysis
By Product Type:
The market is divided into four main product categories: Fresh Meat, Poultry, Seafood, and Others. Among these, Fresh Meat holds the largest share due to its widespread use in daily meals and the increasing demand for protein-rich diets. Poultry products, including chicken, turkey, and duck, are also highly popular due to their affordability and versatility. Seafood, though a smaller segment, is growing steadily as consumers seek healthier alternatives to red meat. The Others category includes specialty meats such as game meat and processed products made from blends of different animal proteins.
By Application:
The market is further segmented based on application into Home Cooking, Foodservice, Ready-to-Eat Meals, Pet Food, and Others. Home Cooking remains a dominant segment as more consumers are cooking at home, often looking for fresh, high-quality meats. Foodservice, encompassing restaurants and catering services, is another significant sector, driven by the demand for processed meat in various cuisines. The Ready-to-Eat Meals segment is expanding rapidly due to increasing consumer preference for convenience foods. Pet Food is a growing application segment as pet owners look for high-protein, nutritious food options for their pets.
Segments
Based on Product Type
- Fresh Meat
- Poultry
- Seafood
- Others
Based on Application
- Home Cooking
- Foodservice
- Ready-to-Eat Meals
- Pet Food
- Others
Based on Packaging type
- Modified Atmosphere Packaging
- Vacuum Packaging
- Tray Packaging
- Others
Based on Certification
- Organic
- Halal
- Kosher
- BRC
- Others
Based on Distribution channel
- Supermarkets/Hypermarkets
- Convenience Stores
- Online Retailers
- Butcher Shops
- Others
Based on Region
- Brazil
- Mexico
- Argentin
Regional Analysis
Brazil (40%)
Brazil holds the largest market share in the Latin American fresh processed meat product market, accounting for approximately 40% of the total market. The country’s large agricultural sector and strong meat production industry support its dominant position. Beef and poultry are particularly popular in Brazil, with beef consumption being deeply rooted in the country’s culinary traditions. The demand for processed meat products, including sausages, bacon, and pre-marinated cuts, is increasing due to urbanization, higher disposable incomes, and changing consumer preferences toward convenience foods. Brazil’s strong export market also contributes to the growth of its processed meat industry, positioning it as a leading supplier in the region.
Mexico (30%)
Mexico is the second-largest market, with an estimated share of 30% of the total market. The demand for processed meats, such as sausages and deli products, is high due to the country’s growing middle class and urbanization. The increasing preference for convenience foods, particularly in metropolitan areas, has led to a rise in demand for ready-to-eat and ready-to-cook processed meat products. The popularity of processed meat in Mexican cuisine, such as chorizo and tacos al pastor, also plays a key role in driving the market’s expansion. Furthermore, Mexico’s proximity to the United States allows for significant imports and trade in processed meat products, contributing to the overall market size.
Key players
- BRF S.A.
- Grupo Bafar
- JBS S.A.
- Alsea
- BRF Group
- Cargill
- Hormel Foods Corporation
- Smithfield Foods
- Maple Leaf Foods
- ConAgra Brands
- Johnsonville
- Farmland Foods
Competitive Analysis
The Latin America Fresh Processed Meat Product Market is highly competitive, with several global and regional players striving for market share. Companies like BRF S.A., JBS S.A., and Grupo Bafar dominate the region due to their strong presence in meat production and distribution, leveraging extensive supply chains and established brand recognition. These key players differentiate themselves through product diversification, including ready-to-eat meals and healthier processed meat options to cater to changing consumer preferences. International players like Hormel Foods Corporation and Cargill further intensify the competition by introducing innovative products, advanced packaging solutions, and sustainability practices. To maintain a competitive edge, players are focusing on expanding their portfolios with organic, low-fat, and clean-label products while investing in e-commerce platforms to reach a broader consumer base. Additionally, market leaders are continuously exploring opportunities in emerging South American markets, contributing to the overall growth of the industry.
Recent Developments
- In January 2025, BRF S.A. reported record export volumes, significantly enhancing its presence in international markets. The company has focused on expanding its operations and product offerings, particularly in the poultry segment, to meet rising global demand for high-quality processed meats. This strategic move aims to capitalize on the growing health-conscious consumer base seeking lean protein options.
- On October 28, 2024, Grupo Bafar announced a remarkable 14.8% increase in net sales for the third quarter of 2024. The company's growth is attributed to its innovative product lines and strong market positioning within Mexico. Grupo Bafar continues to invest in expanding its distribution channels and enhancing product quality to cater to the evolving preferences of consumers seeking convenience and health-focused options.
- In December 2024, JBS S.A. launched a new line of organic processed meat products aimed at health-conscious consumers. This initiative reflects the company’s commitment to sustainability and ethical sourcing practices, aligning with the increasing consumer demand for cleaner labels and responsibly produced foods. The launch is expected to strengthen JBS's market share in the organic segment of processed meats.
- On August 28, 2024, Fitch Ratings affirmed Alsea's IDR at 'BB' with a stable outlook, highlighting the company's robust revenue growth of 10.8% for the year ending 2023. Alsea's diverse portfolio includes processed meat products, which have gained popularity among consumers seeking convenient meal solutions. The company is focusing on
- In February 2025 Cargill announced plans to enhance its meat processing capabilities in Brazil by investing in state-of-the-art technology aimed at improving efficiency and product quality. This development aligns with the company's strategy to meet the growing demand for processed meats while ensuring sustainability in its operations.
- In March 2024, Maple Leaf Foods introduced a new line of plant-based protein products alongside its traditional processed meats, catering to the growing flexitarian consumer base in Latin America. This expansion reflects the company's commitment to innovation and sustainability in response to changing dietary preferences.
- In December 2024, Johnsonville expanded its product offerings by introducing new flavors and formats of sausages tailored for the Latin American market. This move aims to capture a larger share of the growing demand for convenient and flavorful meal solutions among urban consumers.
- In January 2025, Farmland Foods announced an investment in sustainable practices focusing on ethical sourcing and environmentally friendly packaging solutions for its processed meat products. This initiative aligns with consumer preferences for transparency and sustainability in food production.
Market Concentration and Characteristics
The Latin America Fresh Processed Meat Product Market is moderately concentrated, with a few large players dominating the industry, including BRF S.A., JBS S.A., and Grupo Bafar. These companies control a significant share of the market due to their strong production capabilities, extensive distribution networks, and well-established brand recognition. However, the market also features several regional and smaller players that cater to niche segments, particularly in emerging markets where local preferences and lower-price points are crucial. The industry is characterized by a high level of competition, with companies focusing on product innovation, such as healthier and organic processed meats, as well as sustainability and clean-label offerings. The market is further shaped by the growing demand for convenience and ready-to-eat meals, increasing the need for efficient production and packaging solutions. Despite the dominance of large corporations, the presence of smaller players and regional differences in consumer preferences creates a dynamic and evolving market landscape.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Application, Packaging type, Certification, Distribution channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- As urban populations in Latin America expand, the demand for convenient, ready-to-eat processed meats will continue to rise, driving market growth.
- Rising awareness of health risks associated with traditional processed meats will lead to a growing demand for healthier, low-fat, and organic alternatives.
- Sustainability concerns will prompt meat producers to adopt eco-friendly sourcing and production practices, aligning with consumer preferences for ethically produced foods.
- The growing popularity of plant-based diets and hybrid meat products will create new opportunities in the processed meat sector, particularly among health-conscious consumers.
- E-commerce and online grocery platforms will become an essential channel for distributing fresh processed meats, offering consumers greater convenience and broader product options.
- Advances in packaging technology, such as vacuum sealing and modified atmosphere packaging (MAP), will help extend product shelf life and reduce food waste.
- Manufacturers will increasingly diversify their product lines to include more premium, value-added options, such as gourmet sausages and marinated meats, to cater to evolving consumer tastes.
- Emerging markets like Colombia, Peru, and Chile will experience significant growth due to rising disposable incomes and changing dietary habits in these regions.
- As food safety and traceability concerns increase, producers will need to comply with stricter government regulations and certifications, such as organic, halal, and kosher labels, to maintain consumer trust.
- The integration of advanced technologies like AI and automation in meat processing will improve efficiency, product consistency, and cost-effectiveness, shaping the future of the industry.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the Latin America Fresh Processed Meat Product Market in 2023 and 2032?
What are the key drivers of growth in this market?
How are consumer health concerns affecting the market?
What are the key players in the Latin America Fresh Processed Meat Product Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Latin America Fresh Processed Meat Product Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Latin America Fresh Processed Meat Product Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 15,911.3 million → 2032: USD 20,423.7 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Latin America Fresh Processed Meat Product Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Latin America Fresh Processed Meat Product Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Latin America Fresh Processed Meat Product Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Latin America Fresh Processed Meat Product Market Drivers
- 3.3 Latin America Fresh Processed Meat Product Market Restraints & Challenges
- 3.4 Latin America Fresh Processed Meat Product Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Latin America Fresh Processed Meat Product Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Latin America Fresh Processed Meat Product Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Latin America Fresh Processed Meat Product category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Latin America Fresh Processed Meat Product Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Latin America Fresh Processed Meat Product Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Latin America Fresh Processed Meat Product market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Latin America Fresh Processed Meat Product Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Latin America Fresh Processed Meat Product Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Latin America Fresh Processed Meat Product Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Latin America Fresh Processed Meat Product (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Latin America Fresh Processed Meat Product Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Latin America Fresh Processed Meat Product Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Latin America Fresh Processed Meat Product Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Latin America Fresh Processed Meat Product Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Latin America Fresh Processed Meat Product Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Latin America Fresh Processed Meat Product Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Latin America Fresh Processed Meat Product Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Latin America Fresh Processed Meat Product Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Latin America Fresh Processed Meat Product Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
