
Market Overview:
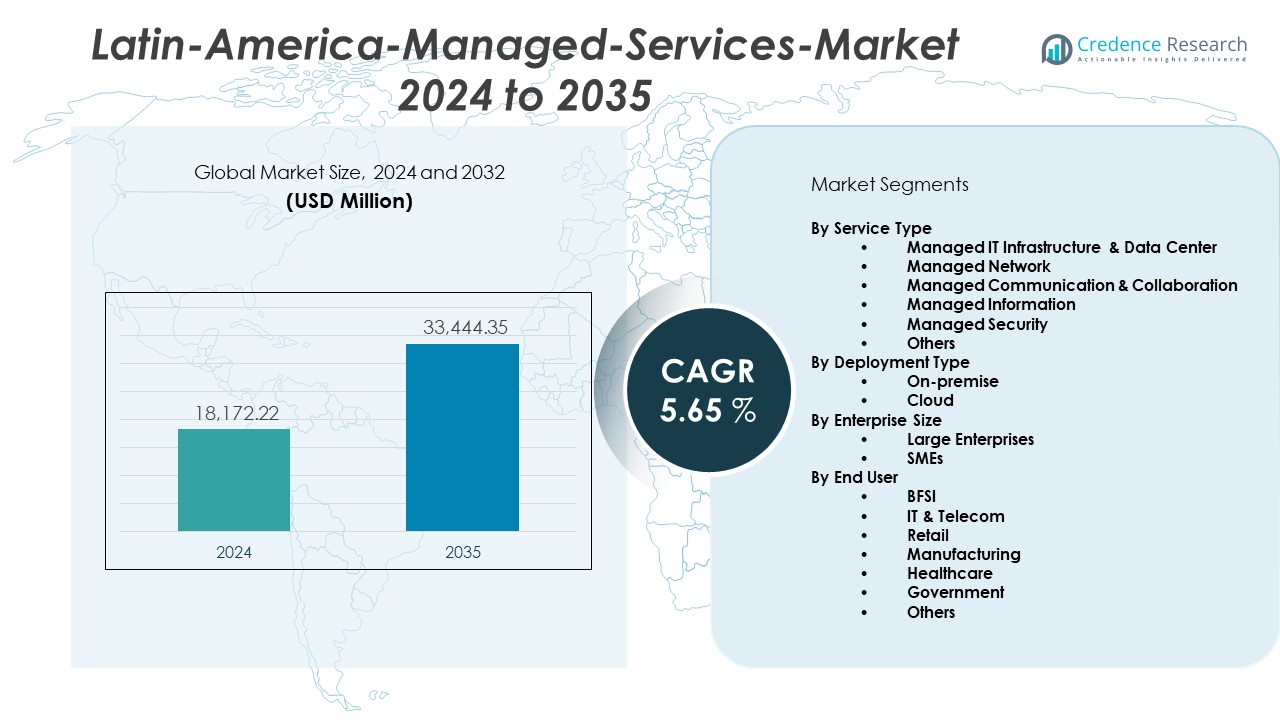
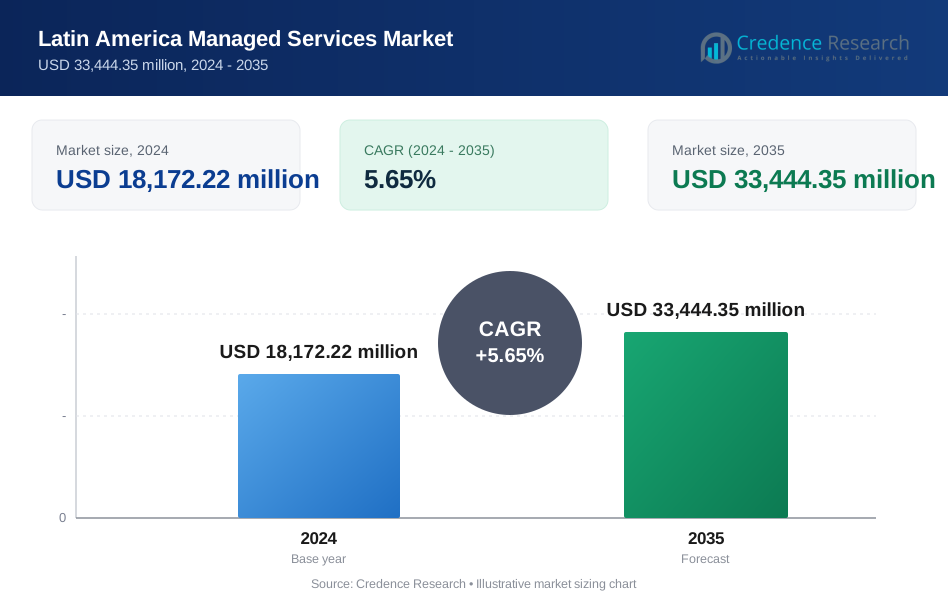
The Latin America Managed Services Market is experiencing robust growth due to the rapid digital transformation and heightened demand for advanced IT infrastructure across various sectors. Valued at approximately USD 18,172.22 Million in 2024, the market is projected to reach around USD 33,444.35 Million by 2035, exhibiting a CAGR of 5.65% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2035 |
| Latin America Managed Services Market Size 2024 | USD 18,172.22 million |
| Latin America Managed Services Market, CAGR | 5.65% |
| Latin America Managed Services Market Size 2035 | USD 33,444.35 million |
Cloud-based managed services, cybersecurity, and managed data center solutions are gaining traction as enterprises increasingly outsource their IT operations to streamline costs and improve operational efficiency. Small and medium-sized enterprises (SMEs), in particular, are turning to managed service providers (MSPs) to access advanced technology without the burden of significant capital investment.
Several factors are driving demand in the Latin American Managed Services Market. The surge in cloud adoption, acceleration of remote work models, and rising need for enhanced data protection are key contributors. Organizations are investing in managed security services as cyber threats escalate in frequency and complexity. Additionally, the integration of AI and automation into managed services is enabling providers to deliver predictive maintenance, optimized network performance, and improved service reliability. Industry verticals such as BFSI, healthcare, retail, and government are leading adopters as they seek to enhance agility, ensure compliance, and modernize their IT infrastructure. The growing focus on digital customer experience and operational resilience further fuels market expansion across the region.
From a regional perspective, Brazil dominates the Latin American managed services landscape, owing to its large enterprise base, high cloud adoption rate, and growing digital services sector. Mexico and Colombia are emerging as significant markets, driven by increased technology investments and government-led digital transformation initiatives. Chile and Argentina also present strong growth potential, especially in sectors like banking and telecommunications. While opportunities abound, challenges such as uneven digital infrastructure and budget constraints in certain markets may impact adoption. However, ongoing public and private sector initiatives to enhance connectivity and cybersecurity readiness are expected to bolster market growth throughout Latin America.
Market Insights:
- The Latin America Managed Services Market is valued at approximately USD 18,172.22 million in 2024 and is projected to reach USD 33,444.35 million by 2035, growing at a CAGR of 5.65%.
- Cloud-based managed services, cybersecurity, and managed data center solutions are key drivers of market growth, as businesses increasingly outsource IT operations to improve efficiency and reduce costs.
- Small and medium-sized enterprises (SMEs) are increasingly adopting managed services to access advanced technologies without heavy capital investment, helping them scale their IT capabilities.
- The demand for managed security services is growing as businesses face increasing cyber threats and the need for data protection, especially in sectors like BFSI and healthcare.
- AI and automation are being integrated into managed services to provide predictive maintenance, optimize network performance, and enhance service reliability.
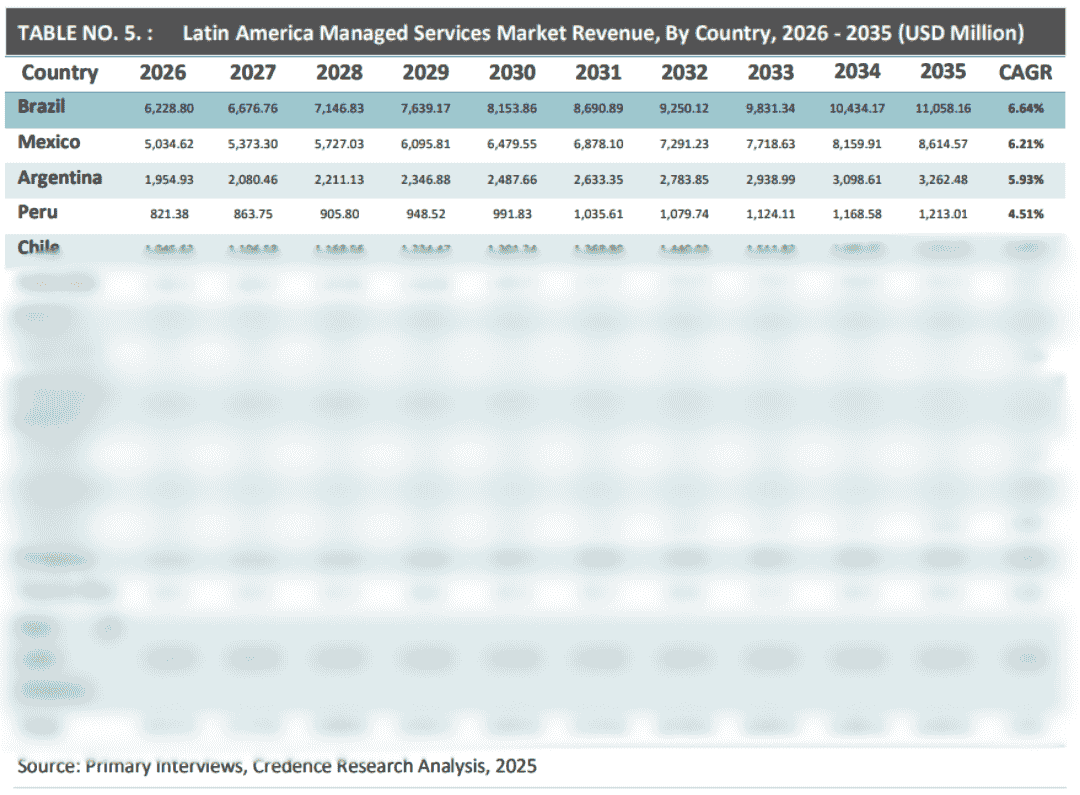
- Brazil dominates the region with 40% market share, driven by its large enterprise base, strong digital transformation efforts, and increasing investments in cloud and cybersecurity services.
- Mexico holds the second-largest share at 25%, benefiting from its proximity to the U.S. and its expanding digital infrastructure, with rising demand for cloud, data center, and cybersecurity services.
Market Drivers:
Accelerated Digital Transformation & Cloud Migration
Digital transformation is reshaping business models across Latin America, as enterprises adopt modern IT architectures, including those supported by over 2,000 startups accelerated through Chile's Start-Up Chile program, to improve agility and cost efficiency. Industries such as banking, retail, healthcare, and telecommunications are rapidly transitioning to hybrid and multi-cloud environments, with hyperscalers like AWS, Microsoft Azure, Google Cloud, and Oracle establishing availability zones in Mexico, Brazil, Chile, and Colombia, to support scalable applications and distributed teams.
Managed service providers (MSPs) are vital partners in this transformation journey, led by Brazil as the frontrunner in investments, offering cloud migration, deployment, and management services tailored to businesses lacking in-house cloud expertise. The growing need for real-time analytics, customer engagement solutions, and AI-driven platforms, as evidenced by Colombia's Vive Digital initiative placing over 2 million computers in schools, further incentivizes organizations to outsource IT management to experienced MSPs.
Increasing Complexity of IT Environments & Rising Cybersecurity Demands
With the proliferation of connected devices, remote access tools, and digital interfaces, IT environments in Latin America have become significantly more complex, as organizations face an average of 2,716 cyberattacks per week. This increased complexity, combined with a surge in cyberattacks averaging 2,640 weekly attacks per organization, is driving demand for managed security services that provide round-the-clock monitoring, incident response, identity management, and compliance with data privacy regulations.
As cyber threats evolve and regulations tighten, businesses in countries like Brazil and Mexico are turning to MSPs for scalable, cost-effective security solutions that ensure both protection and regulatory compliance. Managed Security Service Providers (MSSPs) are delivering advanced tools, such as threat intelligence and AI-based detection, to mitigate risks for enterprises of all sizes, including over 237,000 blocked ransomware attempts in Mexico.
Strategic Adoption of IT Outsourcing by Enterprises and Governments
Organizations across Latin America are adopting IT outsourcing as a strategic move to streamline operations, overcome talent shortages, and enhance competitiveness, supported by Colombia's pool of over 62,000 software developers. Government agencies and large enterprises are increasingly teaming up with MSPs to support national digital transformation agendas, modernize public services, and reduce the burden of legacy infrastructure, as in Brazil serving 210 million citizens through biometric digital ID systems.
Outsourcing IT functions allows businesses and institutions to focus on core competencies while leveraging MSPs’ specialized expertise in infrastructure management, application support, and service delivery. This trend is especially pronounced in Brazil, Mexico, and Colombia, where digital government initiatives like Mexico's Llave MX digital identity and Brazil's AI Plan 2024-2028 are accelerating the adoption of managed services.
Market Trends
Integration of AI, Automation and Edge Solutions
In Latin America, managed service providers (MSPs) are increasingly embedding artificial intelligence (AI) and automation into their service delivery models, underpinned by national initiatives such as Brazil’s ENIA mobilizing over USD 500 million since 2022 and region-wide enterprise deployments documented by policy and industry trackers. This shift supports predictive maintenance, real-time monitoring and automated incident resolution, enabling faster response times and improved operational efficiency, as reflected in multi-country surveys of 2,450 business leaders and corporate rollouts across Brazil and Mexico.
Hybrid architectures-combining on-premises systems, public clouds and edge computing nodes-are becoming standard for enterprises operating across Brazil, Mexico and Colombia, with at least four major hyperscalers running cloud regions anchored in hubs such as São Paulo, Querétaro and Bogotá to support distributed workloads. In parallel, the rise of edge computing is influencing MSP offerings, as more data-intensive workloads migrate closer to users and endpoints supported by newly announced local zones and edge sites in 2025 and national connectivity programs that deployed over 2 million devices into Colombian schools.
Growing Demand for Industry-specific and Outcome-based Models
Another trend shaping the region is the shift from generic IT outsourcing to industry-specific, outcome-based managed services. MSPs are aligning their offerings with vertical-specific needs - such as BFSI, healthcare and retail - to deliver tailored performance SLAs, regulatory compliance support and digital customer experience enhancements. As enterprises mature, they require service models that go beyond infrastructure maintenance to drive business outcomes such as improved time-to-market, agility and customer satisfaction.
Focus on Cybersecurity and Multi-Cloud Governance
Cybersecurity continues to gain prominence as a critical managed service. With the expanding complexity of IT environments and the growing threat surface, organizations are demanding robust managed security services including threat detection, incident response, identity and access management, and regulatory compliance. Concurrently, as enterprises adopt hybrid and multi-cloud environments, governance and risk management frameworks become essential. MSPs in Latin America are responding by offering integrated portfolios that combine infrastructure, cloud and security management. This trend is strongly aligned with global managed services developments, where hybrid IT and cybersecurity are among the top growth drivers.
Expansion of Regional Delivery and Near-shoring Opportunities
A further trend is the growth of regional delivery centres and the near-shoring of managed services in Latin America. As international service providers seek to expand beyond North America and Europe, Latin American countries are emerging as favourable locations due to Spanish- and Portuguese-language capabilities, time-zone alignment with North America, and improving digital infrastructure. This regional expansion enables providers to offer localized service models, optimize cost structures and scale delivery expertise. At the same time, enterprises in the region are increasingly relying on local MSPs and partnerships to navigate country-specific regulatory landscapes and infrastructure constraints. Combined with national digitalisation initiatives, the near-shoring trend enhances the maturity of managed services ecosystems across Latin America.
Market Restraints
Data Privacy & Regulatory Compliance Challenges
The Latin America Managed Services Market faces significant challenges tied to data privacy and regulatory compliance. Countries across the region, including Brazil with its Lei Geral de Proteção de Dados (LGPD) and Mexico with its Federal Data Protection Law, have enacted strict regulations governing data storage, processing, and cross-border transfers. Managed Service Providers (MSPs) must comply with varying national regulations, which complicates the delivery of standardized services across multiple borders. This fragmented regulatory environment increases operational complexity, legal risk, and compliance costs-particularly for MSPs offering cloud, cybersecurity, and data management services. Additionally, clients from regulated sectors such as BFSI and healthcare often require localized data hosting and strong data sovereignty assurance, pushing MSPs to invest in region-specific data infrastructure and compliance expertise.
Infrastructure Gaps & IT Talent Shortage
While digital transformation is accelerating across Latin America, uneven connectivity and limited IT infrastructure remain barriers, particularly in less-developed regions. Rural areas in countries like Peru, Ecuador, and Colombia suffer from low broadband penetration and unreliable networks, which hampers the adoption of cloud-based managed services and remote IT support. These infrastructure gaps not only limit market reach but also hinder the scalability of sophisticated MSP offerings such as hybrid cloud, edge computing, and real-time monitoring. Additionally, the region’s dependency on skilled IT talent presents another challenge. Latin America faces a shortage of specialized professionals in areas such as cybersecurity, cloud engineering, and AI-driven operations. Competition for talent among MSPs and enterprise IT teams has resulted in elevated labor costs and slower project delivery. This talent shortage creates significant pressure on service quality and scalability, compelling providers to invest in training programs, automation tools, and strategic partnerships to bridge the skills gap and ensure continuity in service delivery.
Market Opportunities
The Latin America Managed Services Market is poised for significant growth due to the rapid digital transformation taking place across various sectors. As businesses continue to migrate towards cloud-based infrastructures, there is an increasing demand for managed services that can facilitate this transition. MSPs have a unique opportunity to support enterprises in managing their hybrid cloud environments, optimizing network performance, and providing enhanced security solutions. Additionally, the growing adoption of IoT, AI, and edge computing in sectors such as manufacturing, healthcare, and retail further expands the market. With the rise of smart cities and the rollout of 5G networks, MSPs can tap into opportunities by offering advanced solutions that enable real-time data processing and scalable applications. This opens up significant growth prospects for MSPs with specialized expertise in emerging technologies.
Another key opportunity in the market lies within the small and medium enterprise (SME) segment. SMEs, particularly in emerging markets, often lack the resources to develop and manage sophisticated IT systems. MSPs can address this gap by offering cost-effective, scalable solutions that allow SMEs to benefit from enterprise-grade IT infrastructure, cybersecurity, and cloud services without the need for heavy capital investment. Furthermore, the increasing emphasis on data privacy and regulatory compliance across the region presents a growing demand for managed security services. As regulatory frameworks such as Brazil’s LGPD (General Data Protection Law) become more stringent, MSPs offering compliance-focused managed services will be well-positioned to capture market share, especially in sectors that require strict adherence to data protection regulations.
Market Segmentation Analysis:
By Service Type
The Latin America Managed Services Market is divided into several key service types, with Managed IT services at the forefront. These services provide comprehensive management of IT operations, including infrastructure, applications, and helpdesk support. Infrastructure & Data Center services are crucial for enterprises modernizing their IT environments, as they enable businesses to scale and manage critical workloads efficiently. Managed Network services are also growing as organizations seek reliable, high-performance connectivity to support business operations. Managed Communication & Collaboration services are becoming more prevalent due to the rise in remote and hybrid work models. Managed Security services are expanding rapidly as businesses face increasing cyber threats, while Managed Information services help organizations manage data, analytics, and compliance requirements. Other specialized services cater to specific business needs, such as backup solutions, disaster recovery, and compliance management.
By Deployment Type
In terms of deployment, the cloud-based managed services segment is experiencing rapid growth. The cloud offers flexibility, scalability, and cost-efficiency, making it the preferred choice for businesses looking to reduce capital expenditure while enhancing operational capabilities. The demand for on-premise deployment, however, remains significant, particularly in sectors like banking, government, and healthcare, where data sovereignty and regulatory requirements are critical. As businesses in these industries require more control over their IT infrastructure, on-premise solutions continue to play a key role.
By Enterprise Size
Large enterprises dominate the market due to their complex IT environments and higher adoption of managed services. These organizations require robust, scalable solutions to manage their vast IT infrastructure and operations. However, small and medium enterprises (SMEs) are increasingly turning to managed services to address resource constraints, reduce IT costs, and accelerate their digital transformation. As cloud adoption grows, SMEs are tapping into cost-effective, scalable solutions that were once out of their reach.
By End User
In terms of end users, the BFSI (Banking, Financial Services, and Insurance) and IT & Telecom sectors are the leading adopters of managed services due to their need for secure, reliable, and high-performance IT systems. Retail and manufacturing sectors are also leveraging managed services to improve supply chain management, customer experience, and operational efficiency. The healthcare industry is increasingly adopting managed services for secure data handling and the implementation of e-health solutions, while government agencies are embracing digitalization through e-governance initiatives. Other industries are also adopting managed services to modernize their IT infrastructure, improve efficiency, and ensure regulatory compliance.
Segmentations:
By Service Type
- Managed IT
- Infrastructure & Data
- Center
- Managed Network
- Managed
- Communication &
- Collaboration
- Managed Information
- Managed Security
- Others
By Deployment Type
- On-premise
- Cloud
By Enterprise Size
- Large Enterprises
- SME's
By End User
- BFSI
- IT & Telecom
- Retail
- Manufacturing
- Healthcare
- Government
- Others
Based on the Geography:
- North America
- Asia Pacific
- South America
- Europe
- Middle East & Africa
 LATIN AMERICA MANAGED SERVICES MARKET, 2018 – 2035[/caption]
Regional Analysis:
Brazil
Brazil is the largest market for managed services in Latin America, accounting for approximately 40% of the region’s total market share in 2024. The country’s dominance stems from its large economy, advanced telecom infrastructure, and increasing investments in digital transformation initiatives. Brazil’s managed services demand is driven by large enterprises, particularly in sectors such as banking, retail, healthcare, and government, where there is a strong push to modernize IT systems, enhance cybersecurity, and migrate to cloud platforms. The presence of hyperscale data centers, bolstered by global operators like Equinix, is further fueling cloud adoption and managed services expansion. As Brazil continues to invest in AI, edge computing, and hybrid cloud solutions, the demand for managed infrastructure and security services is set to rise, reinforcing Brazil’s role as a key managed services hub for the region.
Mexico
Mexico holds the second-largest share of the market, accounting for approximately 25% of the Latin America Managed Services Market. The country’s proximity to the United States and its strong integration into North American supply chains position it as an ideal destination for nearshoring and IT outsourcing. The demand for managed services in Mexico is growing rapidly due to the expansion of cloud computing, data centers, and cybersecurity services. The Mexican government’s focus on digital initiatives, such as electronic governance and data protection laws, is further spurring the adoption of managed services. Additionally, the increasing digitalization of industries like manufacturing, retail, and finance has led to greater reliance on managed network services, IT infrastructure, and cloud-based solutions.
Rest of Latin America
The remaining 35% of the market is distributed across the rest of Latin America, including countries like Argentina, Chile, Colombia, Peru, and the Caribbean. While the market in these regions is more fragmented, there is significant growth potential. Countries such as Colombia and Chile are seeing rising investments in cloud services, data centers, and IT infrastructure, driven by the increasing need for digital transformation and e-commerce growth. Managed services are becoming essential in these markets to bridge gaps in IT infrastructure and address the shortage of skilled talent. As regional regulations around data protection and privacy continue to evolve, countries in the Rest of Latin America are expected to experience growing demand for managed security, compliance, and cloud services. The adoption of managed services is also gaining traction among SMEs and public sector organizations, particularly those requiring affordable, scalable IT solutions.
Key Player Analysis:
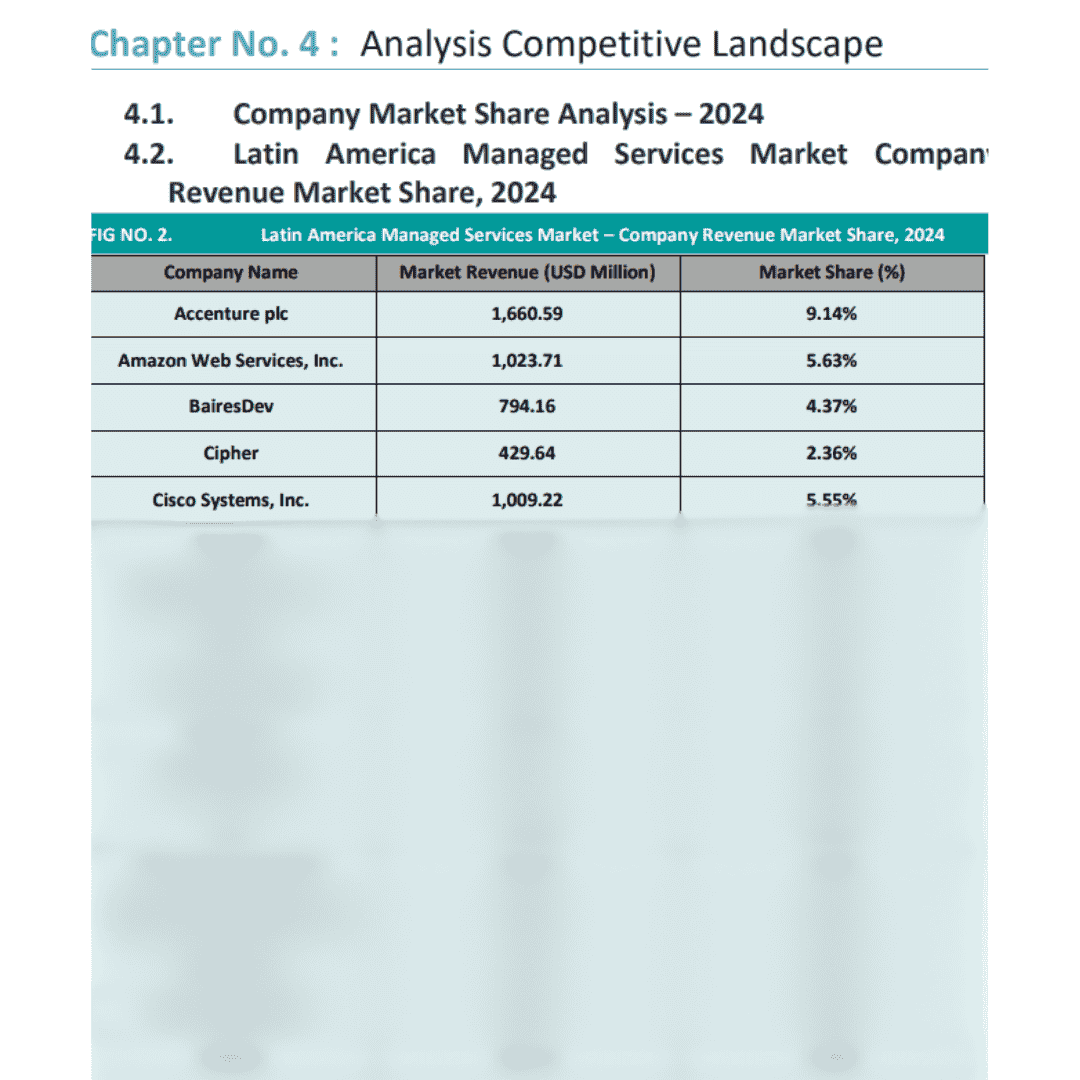
- Accenture plc
- Amazon Web Services, Inc.
- BairesDev
- Cipher
- Cisco Systems, Inc.
- Deloitte
- Digital Realty Trust, Inc.
- EVEO SA
- EY (Ernst & Young)
- Google LLC
- IBM Corporation
- KIO
- Microsoft Corporation
- Módulo Security Solutions S.A.
- NetSecurity
- Oracle Corporation
- Softtek
- Summit
- Tempest Computer Services SA
- Alestra
- Business Support Services (BSS)
- Espacios de Mexico
- GRUPO SICTE
- iCorps
- OpenService
- Tiba IT Services
- Baufest
- Globant
- Huenei IT Services
- 10Pearls
- Business IT (Group Business)
- DIMA
- Andes Digital
- Palo Alto Networks
- Thoughtworks, Inc.
- Ceragon
- EPAM Systems, Inc.
- sa.global
- Digital Innovations
- Astrix Inc. Costa Rica
- CRG SOLUTIONS
- Impulsa IT Solutions
- Navégalo, S.A.
- Novacomp
- Oxford Computer Group
- Bluebox Solutions
- Corporacion Solve
- Digital Business Group
- Comware SA
- EdgeUno
- SERTECHMA
- SYNERGY Ecuador
- Akros
- Bicorp Group
- IT Advisors
- Netsos
- Endava
- BetterWorld Technology
- Informasi
- IT Resources Innovation (IRI)
- Manage IT LLC
- ONUVO
- Others
Competitive Analysis:
The competitive landscape of the Latin America Managed Services Market is shaped by both global IT service providers and regional specialised players. Global firms such as Accenture PLC, IBM Corporation and Microsoft Corporation dominate through their extensive portfolios in cloud migration, managed security, and large‑scale outsourcing, leveraging their scale and global delivery frameworks to serve multinational clients in Latin America.
In parallel, strong regional players such as Softtek (Mexico) and CI&T (Brazil) focus on agile local service delivery, industry‑specific solutions and nearshore cost advantages, enabling them to cater effectively to SMEs and smaller enterprises.
As competition intensifies, providers differentiate through vertical specialisation, value‑added managed security services and hybrid‑cloud orchestration capabilities. Providers able to localise services while maintaining global standards are gaining market share.
Recent Developments:
- November 2025: Ceragon Networks secured a $2.7 million managed services contract with a leading Colombian mobile operator, utilizing its advanced Network Digital Twin technology to optimize network performance.
- November 2025: SentinelOne unveiled its Wayfinder Threat Detection & Response managed services suite, developed in collaboration with Google Cloud. This new offering provides organizations with 24/7, AI-powered detection, investigation, and response capabilities across endpoints, cloud workloads, identities, and more.
- October 2025: Endava signed a framework agreement with Romania’s Authority for Digitalisation (ADR) to support the migration of government applications to the Romanian Government Private Cloud, as part of a key initiative funded under the National Recovery and Resilience Plan (PNRR).
- September 2025: Cisco announced significant enhancements to its Webex Customer Experience portfolio, including the launch of an AI-powered tool for supervisors, set to debut in early 2026, designed to unify quality management across contact centers.
Market Concentration & Characteristics:
The Latin America Managed Services Market exhibits a moderately consolidated structure: a small number of global service providers command substantial share, while numerous regional and local providers serve niche segments. According to market estimates, the region generated about USD 31.8 billion in 2024 and accounted for approximately 9.5 % of the global managed services market.
Major players bring global delivery models, broad service portfolios, and economies of scale, placing pressure on smaller MSPs to differentiate through vertical specialization or localised service models.
Characteristic features of this market include significant domination by Brazil and Mexico, leading innovation in cloud and cybersecurity, and slower maturation in other countries. Brazil, for instance, holds the largest regional share, while cloud‑based offerings continue to outpace on‑premise deployment, reflecting a shift in demand structure.
The market also features high entry barriers in terms of regulatory compliance, data‑sovereignty demands, and the need for skilled talent-factors that limit volatility and support established vendors in retaining market share. Smaller niche players, meanwhile, focus on SMEs, local language support, and country‑specific compliance, which helps maintain a diverse provider ecosystem despite the dominance of larger firms.
Report Coverage:
The research report offers an in-depth analysis based on By Service Type, By Deployment Type, By Enterprise Size, and By End User. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Managed service providers (MSPs) will increasingly adopt artificial intelligence (AI) and machine learning (ML) capabilities to deliver predictive maintenance, automated incident resolution and enhanced operational insights.
- Adoption of managed edge‑computing services will accelerate as enterprises deploy data processing closer to end users and IoT devices, especially in manufacturing, retail and smart‑city contexts.
- Cloud‑native managed services will outpace on‑premise models as enterprises shift workloads to hybrid and multi‑cloud environments, enabling greater agility and cost control.
- Demand for managed security services will grow sharply due to rising cyber threats and regulatory requirements, making managed security a core offering for most MSPs.
- SMEs will emerge as a key growth segment for managed services as they seek outsourced IT capabilities to support digitalization, offering MSPs scalable, modular service models.
- Nearshoring and regional delivery hubs in Latin America will expand, enabling global MSPs to leverage cost and time‑zone advantages while serving both local and international clients.
- Vertical‑specific managed service offerings (e.g., for healthcare, BFSI, manufacturing) will gain traction as providers tailor solutions to industry‑specific compliance, workflow and performance demands.
- Data‑sovereignty and local‑compliance requirements will encourage MSPs to invest in local data centres and regional partnerships to meet country‑specific regulations and client expectations.
- As 5G and connectivity infrastructures improve across Latin America, managed network services (including NaaS) will become more prominent and integrated within comprehensive MSP portfolios.
- Consolidation may increase within the MSP market as acquisitions, alliances and strategic partnerships accelerate smaller niche providers will align with larger global players to scale offerings and geographic coverage.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Latin America Managed Services Market?
What factors are driving the growth of the Latin America Managed Services Market?
What are the key segments within the Latin America Managed Services Market?
What are some challenges faced by the Latin America Managed Services Market?
Who are the major players in the Latin America Managed Services Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 18,172.22 million → 2035: USD 33,444.35 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Latin America Managed Services Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Latin America Managed Services Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2035
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Latin America Managed Services Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2035
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Latin America Managed Services Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Latin America Managed Services Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Latin America Managed Services Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Latin America Managed Services Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Latin America Managed Services Market Outlook, 2024-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 18,172.22 million → 2035: USD 33,444.35 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Latin America Managed Services Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Latin America Managed Services Geographic Market Outlook, 2024-2035
- 13.1 Regional Market Size and Country-Level Shares, 2024
- 13.2 Country Market Size Comparison, 2024
- 13.3 Country Market Forecasts, 2024-2035
- 13.4 Subregional Industrial and Demand Clusters
- 13.5 Intra-Regional Pricing and Cost Differences
- 13.6 Cross-Border Trade and Supply Networks
- 13.7 Regional Supply and Demand Balances
- 13.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 14 Latin America Managed Services Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Energy Efficiency and Resource Management
- 14.7 Sustainability, Recycling and Circularity
- 14.8 Technology Roadmap, 2024-2035
- 14.9 Risks of Obsolescence and Technology Substitution
Chapter 15 Latin America Managed Services Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2035
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Financial Performance and Investment
- 17.2.6 Market Share and Competitive Position
- 17.2.7 Technology and Innovation Capabilities
- 17.2.8 Strategic Alliances or Partnerships
- 17.2.9 Recent Developments
- 17.2.10 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

