
Market Overview
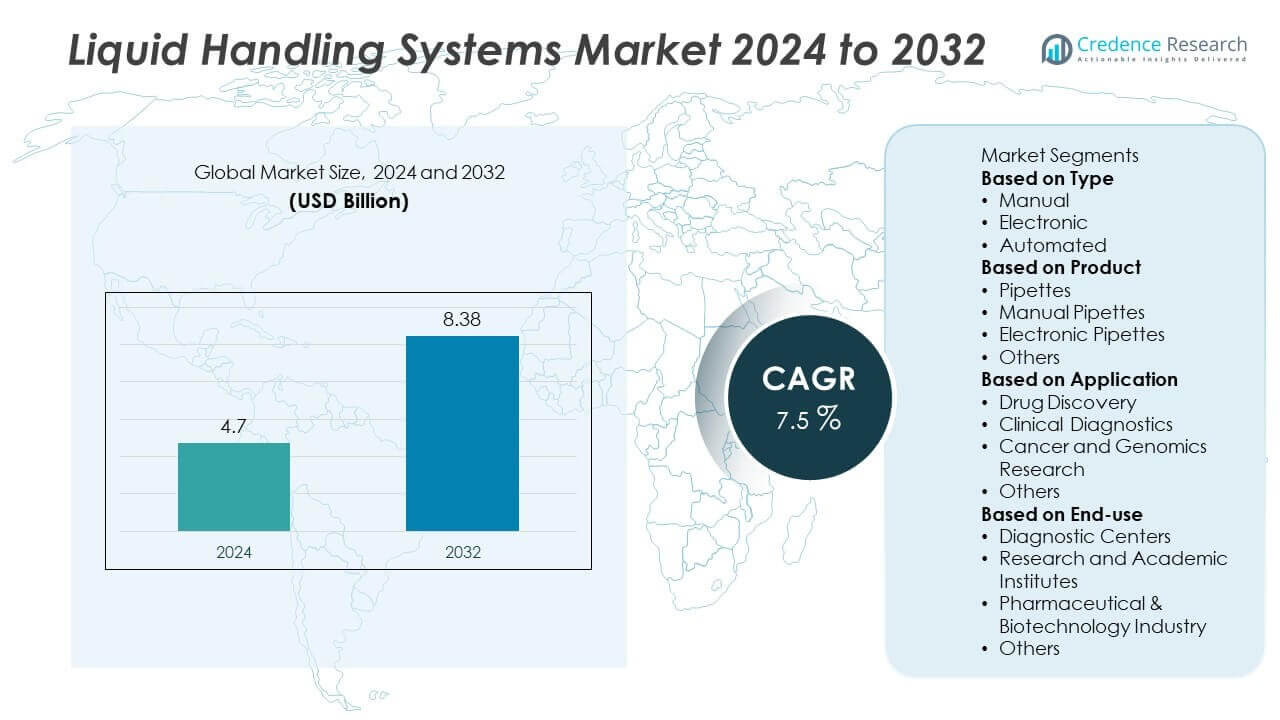
The global Liquid Handling Systems market was valued at USD 4.7 billion in 2024. It is projected to reach USD 8.38 billion by 2032, expanding at a CAGR of 7.5% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Liquid Handling Systems Market Size 2024 | USD 4.7 Billion |
| Liquid Handling Systems Market, CAGR | 7.5% |
| Liquid Handling Systems Market Size 2032 | USD 8.38 Billion |
The liquid handling systems market is driven by top players including Thermo Fisher Scientific, Beckman Coulter, Agilent Technologies, Sartorius AG, Aurora Biomed Ltd, Gilson Inc., Hamilton Company, Eppendorf AG, Tecan Group Ltd., and PerkinElmer Inc. These companies lead through automation, robotics integration, and advanced pipetting solutions tailored for pharmaceutical research, genomics, and diagnostics. North America emerged as the leading region in 2024 with 38% market share, supported by strong R&D infrastructure and high adoption of automated systems. Europe followed with 30% share, driven by robust clinical diagnostics and genomics research, while Asia Pacific accounted for 22% share, fueled by growing pharmaceutical investment and expanding healthcare infrastructure.
 Market Insights
- The global liquid handling systems market was valued at USD 4.7 billion in 2024 and is projected to reach USD 8.38 billion by 2032, growing at a CAGR of 7.5% during the forecast period.
- Key drivers include rising demand for high-throughput screening in drug discovery and the growing adoption of automation in genomics and cancer research, boosting the automated segment that accounted for over 50% share in 2024.
- Trends highlight increasing integration of robotics and AI, along with miniaturization and microfluidics, enabling higher accuracy and reduced reagent use across pharmaceutical and diagnostic applications.
- The market is highly competitive with players such as Thermo Fisher Scientific, Beckman Coulter, Agilent Technologies, Sartorius AG, Aurora Biomed Ltd, and Gilson Inc., focusing on product innovation, collaborations, and regional expansion.
- Regionally, North America led with 38% share, followed by Europe at 30% and Asia Pacific at 22%, supported by strong R&D infrastructure and expanding healthcare investments.
Market Segmentation Analysis:
By Type
The automated segment dominated the liquid handling systems market in 2024 with over 50% share. Demand is driven by high throughput needs in laboratories, rising adoption of robotics, and growing precision requirements in pharmaceutical and biotech workflows. Automated systems reduce manual errors, enhance reproducibility, and streamline processes such as next-generation sequencing and high-throughput screening. Electronic systems followed with notable growth due to their ergonomic design and accuracy in routine tasks. Manual systems maintained a smaller share, largely used in academic labs and cost-sensitive settings.
- For instance, The Gilson PIPETMAN Classic, a durable and highly reliable manual air-displacement pipette, offers a range of volumes up to 10 mL. Its accuracy and robust construction make it a trusted, economical choice for many teaching and research laboratories. In educational settings, it is a staple for demonstrating fundamental liquid handling techniques.
By Product
Pipettes accounted for the largest share in 2024, holding nearly 45% of the market. Within this category, electronic pipettes gained traction due to superior accuracy, reduced hand strain, and suitability for repetitive laboratory tasks. Manual pipettes continued to see widespread use in research institutes and teaching labs where affordability and simplicity are key. The "others" segment, including burettes and dispensers, captured a smaller portion but is expanding steadily. The pipette market’s dominance is supported by consistent demand across life sciences, drug discovery, and clinical applications.
- For instance, Beckman Coulter integrates automated pipetting modules into its Biomek i-Series, capable of handling 96- and 384-well plates for drug screening.
By Application
Drug discovery emerged as the leading application in 2024, representing around 40% market share. Growth is fueled by increased R&D spending from pharmaceutical and biotech companies, alongside the expansion of high-throughput screening platforms. Clinical diagnostics followed as the second-largest segment, benefiting from rising demand for infectious disease testing and automation in clinical labs. Cancer and genomics research contributed a strong share, supported by precision medicine initiatives and sequencing advancements. Other applications, including food safety and forensics, showed steady uptake but remain relatively niche compared to drug discovery.
Key Growth Drivers
Rising Demand for High-Throughput Screening
The growing need for high-throughput screening in drug discovery is a major driver for liquid handling systems. Automated systems allow rapid testing of thousands of compounds, reducing development timelines and increasing efficiency. Pharmaceutical and biotech companies are investing heavily in automation to improve accuracy and productivity. The expansion of clinical trials and personalized medicine programs also supports adoption. As laboratories prioritize throughput and reproducibility, automated liquid handling platforms become critical to accelerate innovation and meet regulatory standards.
- For instance, Beckman Coulter’s Biomek i7 Automated Workstation can process 1,536-well plates in under 10 minutes, supporting compound libraries exceeding 100,000 samples for high-throughput screening programs.
Expansion of Genomics and Cancer Research
Increasing research in genomics and cancer is fueling demand for precision liquid handling solutions. Applications such as PCR, next-generation sequencing, and gene expression analysis require highly accurate pipetting and sample preparation. Laboratories are investing in advanced liquid handling systems to ensure reproducibility and reduce human error. Rising cancer prevalence and government-funded genomics initiatives further drive adoption. These systems support the handling of large sample volumes in oncology studies, enabling breakthroughs in precision medicine, biomarker discovery, and targeted therapies.
- For instance, Tecan’s DreamPrep NGS system automates library preparation for next-generation sequencing, processing up to 96 genomic samples in a single run with high pipetting accuracy and precision, enabling large-scale genomics workflows like cancer genomics.
Growth in Clinical Diagnostics and Personalized Medicine
The clinical diagnostics sector contributes significantly to liquid handling system demand. Automated pipetting and dispensing tools are widely used in infectious disease testing, genetic screening, and molecular diagnostics. The shift toward personalized medicine has created demand for reliable sample preparation in molecular assays. Hospitals and diagnostic centers seek faster turnaround times and reduced error rates, driving adoption of electronic and automated platforms. Rising healthcare spending, coupled with the adoption of automation in clinical labs, continues to strengthen the market growth outlook.
Key Trends & Opportunities
Integration of Robotics and Artificial Intelligence
Robotics and AI are emerging as key trends in liquid handling systems. AI-powered platforms enable predictive maintenance, adaptive workflows, and improved sample tracking. Robotics integration enhances efficiency and supports fully automated labs. The opportunity lies in reducing manual errors, increasing throughput, and enabling advanced workflows in genomics and proteomics. As smart laboratories evolve, companies that offer AI-driven liquid handling systems are well-positioned to capture demand from research organizations, pharmaceutical firms, and diagnostics providers seeking scalable automation solutions.
- For instance, Hamilton Company’s Microlab STAR platform integrates AI-based scheduling and robotic arms capable of handling up to 1,000 samples per day, while maintaining pipetting precision within ±0.5% at volumes as low as 0.5 µL.
Miniaturization and Microfluidics Adoption
The trend toward miniaturization and use of microfluidics is creating new opportunities. Microfluidics allows laboratories to perform assays with minimal reagent volumes, reducing costs and environmental impact. Liquid handling systems that integrate microfluidic technology support point-of-care testing, personalized healthcare, and lab-on-chip applications. This trend benefits industries requiring high sensitivity and precision in sample analysis, such as genomics, proteomics, and diagnostic testing. As microfluidic-based systems advance, they open opportunities for compact, portable, and cost-effective solutions in both research and clinical applications.
- For instance, PerkinElmer’s LabChip GXII Touch system uses microfluidic channels to analyze DNA, RNA, and protein samples with volumes as low as 5 nL, delivering results in under 30 seconds per sample for oncology and genomics applications.
Key Challenges
High Cost of Advanced Systems
The high initial cost of advanced liquid handling systems is a major challenge. Automated platforms require significant investment in hardware, software, and maintenance, limiting adoption among small research laboratories and academic institutions. Budget constraints often drive organizations to continue using manual or semi-automated solutions. The return on investment can be long, especially for labs with limited throughput requirements. Addressing cost barriers through affordable, scalable solutions remains essential for expanding market penetration across diverse research and clinical settings.
Complexity of System Integration and Maintenance
Integrating advanced liquid handling systems into existing laboratory workflows presents another challenge. Compatibility with laboratory information systems, reagent kits, and other instruments can create operational hurdles. Additionally, maintaining calibration, ensuring system reliability, and training staff add to complexity. Downtime from technical issues can disrupt critical workflows in diagnostics and research. Vendors must focus on user-friendly designs, seamless integration, and reliable support services to address these challenges. Overcoming integration and maintenance barriers is vital to fully realizing the benefits of automation.
Regional Analysis
North America
North America held the largest share of the liquid handling systems market in 2024 with 38% share. The region’s leadership is driven by advanced pharmaceutical and biotechnology sectors, strong presence of key market players, and significant investment in drug discovery and clinical research. The United States dominates regional demand, supported by high adoption of automation in laboratories and government funding for genomics and cancer research. Canada also contributes through expanding clinical diagnostic facilities and rising demand for personalized medicine. Continued technological advancements and a mature healthcare infrastructure sustain North America’s leading position in the market.
Europe
Europe accounted for 30% share of the liquid handling systems market in 2024. The region benefits from strong academic research institutions, government-backed genomics programs, and well-established pharmaceutical companies. Countries such as Germany, the United Kingdom, and France lead adoption, supported by initiatives promoting personalized medicine and advanced clinical diagnostics. Demand is further fueled by the integration of automation in drug development and clinical laboratories. Europe’s regulatory framework emphasizes precision and accuracy, encouraging investment in automated systems. Ongoing advancements in cancer research and molecular diagnostics contribute significantly to the region’s steady growth trajectory.
Asia Pacific
Asia Pacific captured 22% share of the liquid handling systems market in 2024. Growth is driven by rising pharmaceutical R&D investment, expanding healthcare infrastructure, and increasing prevalence of cancer and infectious diseases. China, Japan, and India lead regional adoption due to government initiatives supporting genomics and biotechnology research. The region is also witnessing higher adoption of automated liquid handling systems in diagnostic laboratories to improve testing accuracy and efficiency. Expanding clinical trials, cost advantages in manufacturing, and growing demand for precision medicine strengthen Asia Pacific’s role as a high-growth region in the global market.
Latin America
Latin America represented 6% share of the liquid handling systems market in 2024. The region’s growth is supported by increasing adoption of automated diagnostic tools in Brazil, Mexico, and Argentina. Expanding biotechnology research and rising healthcare expenditure contribute to demand. Drug discovery initiatives and efforts to improve clinical diagnostic capabilities also encourage investment in liquid handling systems. However, budget constraints in public healthcare facilities and slower adoption of advanced technologies limit market expansion. Despite these challenges, the region is expected to grow steadily, driven by rising demand for precision diagnostics and pharmaceutical development.
Middle East & Africa
The Middle East & Africa accounted for 4% share of the liquid handling systems market in 2024. Growth is mainly driven by the expansion of healthcare infrastructure in Gulf countries such as Saudi Arabia and the United Arab Emirates. Increasing investments in advanced diagnostic laboratories and biotechnology research initiatives support adoption. South Africa also contributes through growing demand for clinical diagnostics and infectious disease testing. However, limited research budgets and lower penetration of automation present challenges. Despite these hurdles, rising healthcare modernization efforts are expected to create long-term opportunities for liquid handling system providers.
Market Segmentations:
By Type
- Manual
- Electronic
- Automated
By Product
- Pipettes
- Manual Pipettes
- Electronic Pipettes
- Others
By Application
- Drug Discovery
- Clinical Diagnostics
- Cancer and Genomics Research
- Others
By End-use
- Diagnostic Centers
- Research and Academic Institutes
- Pharmaceutical & Biotechnology Industry
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Competitive Landscape
The competitive landscape of the liquid handling systems market is shaped by leading players such as Thermo Fisher Scientific, Aurora Biomed Ltd, Sartorius AG, Gilson Inc., Beckman Coulter, Agilent Technologies, Hamilton Company, Eppendorf AG, Tecan Group Ltd., and PerkinElmer Inc. These companies focus on technological innovation, portfolio expansion, and strategic collaborations to strengthen their market presence. Automation, robotics integration, and AI-driven platforms remain central to their R&D investments, catering to high-throughput screening, genomics, and diagnostics applications. Partnerships with pharmaceutical firms, diagnostic centers, and academic institutions support product adoption and global expansion. North America and Europe serve as strongholds for established players, while Asia Pacific is emerging as a key growth region, attracting investment and localized manufacturing. Intense competition drives continuous product upgrades, emphasizing precision, scalability, and cost-effectiveness. Companies also adopt mergers, acquisitions, and strategic alliances to expand their capabilities and meet rising demand across drug discovery, clinical diagnostics, and cancer research.
Key Player Analysis
- Thermo Fisher Scientific
- Aurora Biomed Ltd
- Sartorius AG
- Gilson Inc.
- Beckman Coulter
- Agilent Technologies
- Hamilton Company
- Eppendorf AG
- Tecan Group Ltd.
- PerkinElmer Inc.
Recent Developments
- In June 2025, Ingersoll Rand acquired Lead Fluid, boosting its life science fluid handling capacity.
- In March 2025, HighRes Biosolutions acquired Let’s Go Robotics, enhancing its low-volume dispensing capabilities.
- In 2025, Merck KGaA is also highlighted in reports as a major participant in liquid handling systems markets.
- In 2025, Eppendorf’s presence in liquid handling remains strong, with its broad portfolio of automated pipetting and handling systems.
Report Coverage
The research report offers an in-depth analysis based on Type, Product, Application, End-use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Automated liquid handling systems will see wider adoption across pharmaceutical and biotechnology research.
- Integration of robotics and AI will improve accuracy, efficiency, and workflow scalability in laboratories.
- Growth in genomics and cancer research will boost demand for high-precision liquid handling tools.
- Clinical diagnostics will remain a strong application area, driven by molecular and genetic testing needs.
- Miniaturization and microfluidic innovations will lower reagent costs and enable portable solutions.
- Asia Pacific will emerge as the fastest-growing region with expanding healthcare and research investments.
- North America will maintain leadership due to strong R&D funding and advanced infrastructure.
- Key players will focus on partnerships, acquisitions, and product innovations to strengthen presence.
- High equipment cost and integration complexity will remain challenges for smaller laboratories.
- Sustainable and energy-efficient designs will gain traction as laboratories adopt greener practices.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
High-Throughput Screening in Drug Discovery
The need to rapidly test thousands of compounds in pharmaceutical R&D is driving adoption of automated liquid handling systems, which increase efficiency and reduce development timelines for new drugs.
Automation in Genomics and Cancer Research
Expanding genomics and cancer research requires highly precise and reproducible liquid handling for applications like next-generation sequencing and PCR, fueling demand for advanced automated systems.
Growth in Clinical Diagnostics and Personalized Medicine
Rising demand for molecular and genetic testing in clinical diagnostics is boosting the use of automated and electronic liquid handling platforms, as laboratories seek faster turnaround and reduced error rates.
Integration of Robotics and Artificial Intelligence
The adoption of robotics and AI in liquid handling systems is enabling predictive maintenance, adaptive workflows, and higher throughput, making laboratories more efficient and scalable.
Miniaturization and Microfluidics
The trend toward miniaturized and microfluidic-based liquid handling systems is reducing reagent costs and enabling new applications in point-of-care diagnostics and portable laboratory solutions.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Liquid Handling Systems market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Liquid Handling Systems market projected to grow between 2025 and 2032?
Which Liquid Handling Systems market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Liquid Handling Systems market?
Who are the leading companies in the Liquid Handling Systems market?
Which region commanded the largest share of the Liquid Handling Systems market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Manual
- 1.2.2 Electronic
- 1.2.3 Automated
- 1.3 By End-use
- 1.3.1 Diagnostic Centers
- 1.3.2 Research and Academic Institutes
- 1.3.3 Pharmaceutical & Biotechnology Industry
- 1.3.4 Others
- 1.4 By Product
- 1.4.1 Pipettes
- 1.4.2 Manual Pipettes
- 1.4.3 Electronic Pipettes
- 1.4.4 Others
- 1.5 By Application
- 1.5.1 Drug Discovery
- 1.5.2 Clinical Diagnostics
- 1.5.3 Cancer and Genomics Research
- 1.5.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 4.7 billion → 2032: USD 8.38 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Liquid Handling Systems Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Liquid Handling Systems Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Liquid Handling Systems Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Liquid Handling Systems Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Liquid Handling Systems Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Liquid Handling Systems Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Liquid Handling Systems Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Liquid Handling Systems Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 4.7 billion → 2032: USD 8.38 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Liquid Handling Systems Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Manual
- 12.3.7.2 Electronic
- 12.3.7.3 Automated
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End-use - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Diagnostic Centers
- 12.4.7.2 Research and Academic Institutes
- 12.4.7.3 Pharmaceutical & Biotechnology Industry
- 12.4.7.4 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Pipettes
- 12.5.7.2 Manual Pipettes
- 12.5.7.3 Electronic Pipettes
- 12.5.7.4 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Application - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Drug Discovery
- 12.6.7.2 Clinical Diagnostics
- 12.6.7.3 Cancer and Genomics Research
- 12.6.7.4 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Liquid Handling Systems End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Liquid Handling Systems Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Liquid Handling Systems Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Liquid Handling Systems Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Thermo Fisher Scientific
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Beckman Coulter
- 18.4 Agilent Technologies
- 18.5 Sartorius AG
- 18.6 Aurora Biomed Ltd
- 18.7 Gilson Inc.
- 18.8 Hamilton Company
- 18.9 Eppendorf AG
- 18.10 Tecan Group Ltd.
- 18.11 PerkinElmer Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

