
Market Overview:
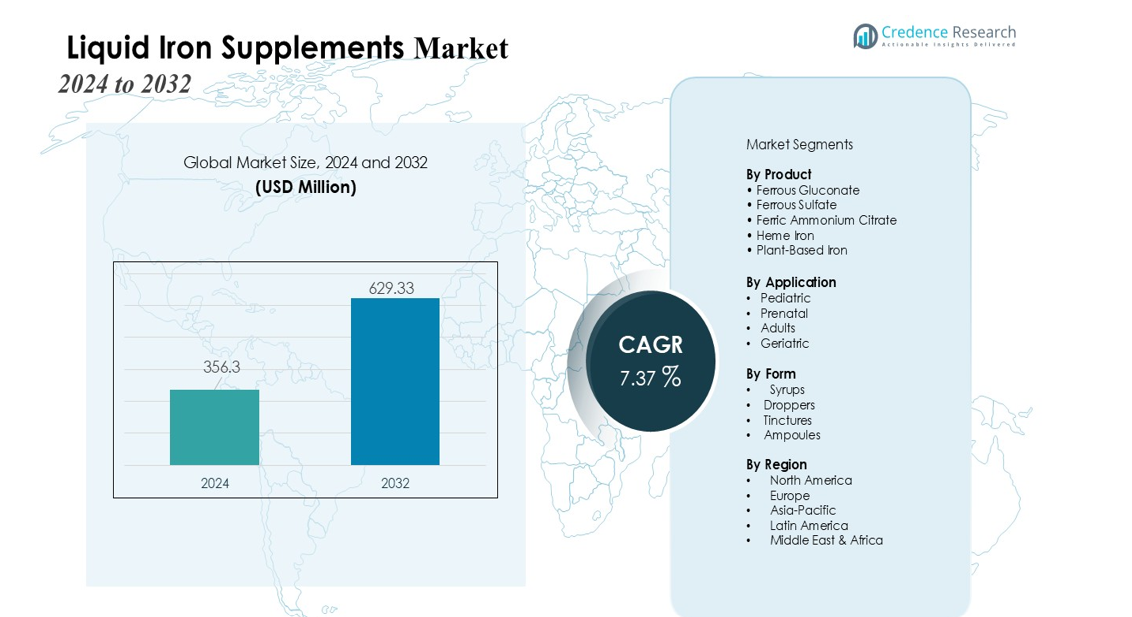
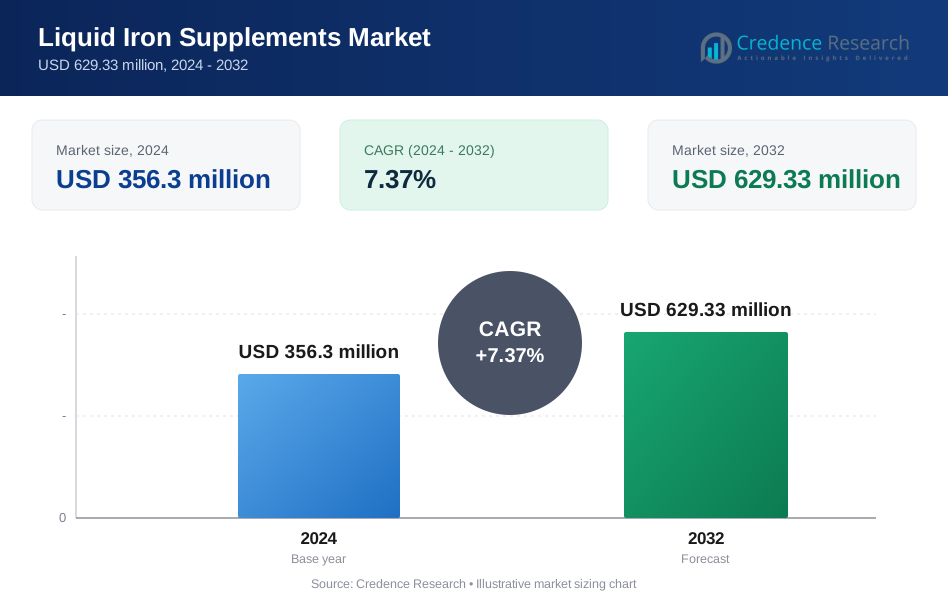
The Liquid Iron Supplements Market size was valued at USD 356.3 million in 2024 and is anticipated to reach USD 629.33 million by 2032, at a CAGR of 7.37% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Liquid Iron Supplements Market Size 2024 | USD 356.3 million |
| Liquid Iron Supplements Market, CAGR | 7.37% |
| Liquid Iron Supplements Market Size 2032 | USD 629.33 million |
Rising global prevalence of iron-deficiency anemia (IDA) acts as a key catalyst for market expansion. Healthcare professionals recommend liquid iron supplements to improve hemoglobin levels, support maternal health, and address nutritional gaps among individuals with malabsorption disorders. The shift toward preventive healthcare, coupled with growing awareness of micronutrient insufficiency, further drives adoption. Expanding retail penetration through pharmacies, online platforms, and wellness stores also enhances product accessibility.
Regionally, North America leads the market due to strong healthcare awareness, high supplement consumption rates, and robust clinical recommendations for iron intake among pregnant women and children. Europe follows with rising demand for plant-based and clean-label formulations. Asia-Pacific is the fastest-growing region, supported by high IDA prevalence, improving healthcare infrastructure, and increasing adoption of nutritional supplements across India, China, and Southeast Asia.
Market Insights:
- The USD 356.3 million Liquid Iron Supplements Market is set to reach USD 629.33 million by 2032, driven by a strong rise in global iron-deficiency anemia cases.
- Increasing clinical preference for liquid formulations enhances demand due to faster absorption and better tolerance among children, pregnant women, and individuals with malabsorption issues.
- Growing preventive healthcare awareness encourages proactive iron intake, supported by physician recommendations and rising consumer focus on immunity and energy.
- Product accessibility improves through expanding retail channels, including pharmacies, e-commerce, and specialty nutrition stores, boosting overall adoption.
- Innovation in high-absorption, flavored, sugar-free, and gentle-on-stomach formulations enhances user compliance and market differentiation.
- Despite growth, concerns over gastrointestinal side effects, inconsistent absorption, and misconceptions about iron safety pose barriers to consistent usage.
- North America leads market share due to strong healthcare awareness, while Asia-Pacific emerges as the fastest-growing region with rising anemia prevalence and expanding healthcare infrastructure.
Market Drivers:
Growing Preference for High-Absorption and Easy-to-Consume Formulations Enhances Adoption
Consumers prefer liquid formats because they offer superior bioavailability compared with traditional tablets or capsules. The Liquid Iron Supplements Market benefits from high demand among children, older adults, and individuals with swallowing difficulties. It enables flexible dosing, which supports personalized nutrition plans. Product manufacturers introduce flavored, sugar-free, and gentle-on-stomach variants that improve adherence.
- For instance, Ferretts IPS liquid iron supplement is clinically proven to have high bioavailability and a gentle formula suitable for sensitive stomachs, with absorption rates optimized for faster iron replenishment.
Expansion of Preventive Healthcare and Nutrition Awareness Drives Consumption
Preventive healthcare trends encourage individuals to address micronutrient gaps before symptoms appear. The Liquid Iron Supplements Market grows as consumers follow physician guidance, wellness recommendations, and digital health insights highlighting iron’s role in energy and immunity. It appeals to fitness-oriented users and women in reproductive age groups who require consistent iron intake. Retail education initiatives and health campaigns expand general awareness.
- For Instance, Active Iron rebranded and updated its existing capsule iron supplement range for pregnant women, including the release of higher-dose products like Active Iron Advance (25mg) and the comprehensive Active Iron Pregnancy Plus.
Wider Retail Availability and Product Diversification Improves Market Penetration
E-commerce platforms, pharmacies, and specialty nutrition stores increase access to liquid iron products. The Liquid Iron Supplements Market advances as brands invest in clean-label, plant-based, and organic ingredient profiles. It benefits from rapid home-delivery systems and subscription-based supplement programs that support consistent use. Companies strengthen distribution networks to reach underserved regions and high-need demographics.
Market Trends:
Shift Toward Clean-Label, Plant-Based, and Gentle Formulations Shapes Product Innovation
Consumers seek iron supplements that align with natural, vegan, and allergen-free expectations, which guides product development across the Liquid Iron Supplements Market. Brands reformulate products with plant-derived iron sources, minimal additives, and bioactive enhancers that support efficient absorption. It appeals to health-conscious users who prioritize transparency, sustainability, and digestive comfort. Companies introduce sugar-free, gluten-free, and preservative-free variants that meet diverse dietary preferences. Flavored liquid formats gain traction because they mask metallic taste concerns that reduce adherence in traditional iron supplements. Digital reviews and wellness influencers elevate demand for clean-label offerings. Manufacturers expand R&D investment to strengthen product appeal across multiple consumer profiles.
- For instance, Floradix® Iron + Herbs Liquid Herbal Supplement delivers 10 mg of iron from ferrous gluconate combined with essential B vitamins and vitamin C, enabling gentle digestion and enhanced bioavailability without artificial additives.
Integration of Personalized Nutrition, Digital Adoption, and Omni-Channel Retail Boosts Market Expansion
Personalized nutrition platforms recommend liquid iron formulations based on biomarker results, lifestyle assessments, and dietary patterns, which elevates precision in supplementation. The Liquid Iron Supplements Market benefits from rising demand for tailored health solutions supported by AI-driven nutrition apps and at-home diagnostic kits. It gains stronger visibility through online pharmacies, D2C brands, and subscription-based services that ensure consistent product use. Omni-channel retail strengthens user engagement by connecting physical stores with digital ecosystems. Health practitioners rely on telehealth consultations to guide dosage selection and product choice with higher accuracy. Brands increase consumer education through digital campaigns that highlight benefits, safety profiles, and usage convenience. E-commerce analytics support faster product optimization and targeted outreach.
- For instance, Lubrizol Life Science Health developed a prototype of iron-fortified, plant-based gummies featuring 10mg elemental iron per serving using LIPOFER™ microencapsulation technology, addressing bioavailability and side effect concerns effectively.
Market Challenges Analysis:
Concerns Over Gastrointestinal Side Effects and Variable Absorption Limit Consistent Usage
Many consumers report nausea, constipation, or metallic taste with certain iron formulations, which reduces long-term adherence and creates hesitation toward supplementation. The Liquid Iron Supplements Market faces challenges when users experience discomfort despite improved bioavailability claims. It requires continuous innovation to develop gentler formulations that maintain therapeutic effectiveness. Healthcare providers emphasize proper dosing, yet inconsistent usage patterns affect treatment outcomes. Competition from fortified foods and alternative iron delivery systems reduces reliance on liquid formats. Some consumers avoid iron supplements altogether due to misconceptions about safety and overconsumption risks.
Regulatory Compliance, Quality Control, and Pricing Pressure Affect Market Stability
Stringent labeling norms and varying global regulatory standards require brands to maintain high product transparency and consistent testing practices. The Liquid Iron Supplements Market must navigate complex stability requirements because liquid products face higher contamination and degradation risks. It demands investment in packaging technology, which increases production costs and impacts pricing strategies. Smaller manufacturers struggle to compete with established brands that dominate distribution channels. Fluctuating raw material costs influence profitability and limit innovation budgets. Supply-chain delays and limited access to high-quality iron sources disrupt product availability across certain regions.
Market Opportunities:
Expansion of Preventive Health, Maternal Nutrition, and Pediatric Supplementation Creates Strong Growth Potential
Preventive health awareness increases demand for iron products that support immunity, energy, and developmental needs across multiple age groups. The Liquid Iron Supplements Market gains opportunities through rising focus on maternal nutrition and early-life micronutrient interventions. It aligns with national health programs that prioritize anemia reduction and prenatal care. Pediatric-friendly liquid formats attract parents who require safe, gentle, and easy-to-dose solutions. Growing interest in women’s wellness further broadens the consumer base. Healthcare professionals recommend routine supplementation, which expands long-term usage potential.
Innovation in Clean-Label, Personalized, and Digital-First Solutions Strengthens Market Expansion
Clean-label and plant-based formulations open new avenues for brands targeting health-conscious consumers seeking transparency and minimal additives. The Liquid Iron Supplements Market can capitalize on personalized nutrition platforms that guide dosing through biomarker insights and lifestyle analytics. It benefits from digital retail environments where subscription-based supply and telehealth guidance improve adherence. Opportunities arise from sugar-free, allergen-free, and bioactive-enhanced variants that meet evolving dietary expectations. Emerging markets experience strong demand due to rising healthcare access and anemia prevalence. Companies that expand distribution into underserved regions gain significant competitive advantage.
Market Segmentation Analysis:
By Product
The Liquid Iron Supplements Market includes ferrous gluconate, ferrous sulfate, ferric ammonium citrate, heme iron, and plant-based iron variants. Ferrous gluconate leads due to its favorable tolerance profile and strong clinician preference for general anemia management. It appeals to users who require gentle formulations that reduce gastrointestinal discomfort. Heme iron gains traction among consumers seeking higher absorption and fewer dietary interactions. Plant-based products attract vegan and clean-label buyers who prioritize natural ingredients. The category benefits from continuous innovation in taste-masking and flavor enhancement.
- For instance, ferrous gluconate is recognized for its high bioavailability and reduced gastrointestinal side effects; clinical studies have demonstrated significant improvement in hemoglobin levels within 12 weeks of supplementation with ferrous gluconate, supporting its use in iron deficiency anemia treatment with an increase in hemoglobin concentration by approximately 1.0 g/dL over the treatment period.
By Application
Key applications cover pediatric care, prenatal nutrition, adult supplementation, and geriatric support. Pediatric usage grows rapidly because liquid formats allow precise dosing and easy ingestion. The Liquid Iron Supplements Market records strong demand in prenatal care where physicians emphasize consistent iron intake for maternal and fetal health. It supports adult users dealing with fatigue, low hemoglobin, or restricted diets. Geriatric adoption rises due to the need for highly absorbable iron that suits individuals with compromised digestion. Healthcare providers influence consumption patterns through structured supplementation protocols.
- For instance, Active Iron offers a clinically proven 25mg iron supplement in capsule form that increases iron and energy levels while being gentle on the stomach, utilizing a patented whey protein formulation to optimize nutrient absorption in adult users
By Form
Primary forms include droppers, syrups, tinctures, and ampoules. Syrups dominate due to wide availability, improved palatability, and suitability for all age groups. Droppers attract parents and caregivers who need controlled dosing for infants and children. It creates opportunities for brands to introduce sugar-free and flavored versions tailored to sensitive users. Tinctures appeal to consumers who prefer concentrated formulations with minimal additives. Ampoules serve clinical settings where precise, single-use dosage improves safety and compliance.
Segmentations:
By Product
- Ferrous Gluconate
- Ferrous Sulfate
- Ferric Ammonium Citrate
- Heme Iron
- Plant-Based Iron
By Application
- Pediatric
- Prenatal
- Adults
- Geriatric
By Form
- Syrups
- Droppers
- Tinctures
- Ampoules
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America Leads with Strong Healthcare Awareness and High Supplement Adoption
North America holds the dominant share due to strong clinical emphasis on early anemia detection and widespread consumer engagement in nutritional supplementation. The Liquid Iron Supplements Market gains traction as healthcare providers recommend liquid formats for children, pregnant women, and older adults. It benefits from well-established retail networks, including pharmacies, online channels, and specialty nutrition stores. High prevalence of iron-deficiency anemia among women of reproductive age supports sustained demand. Brands introduce clean-label, flavored, and gentle-on-stomach variants that align with evolving consumer expectations. Government and clinical guidelines promote consistent iron intake, which strengthens adoption across all age groups.
Europe Shows Steady Demand Supported by Regulatory Standards and Preference for Natural Formulations
Europe records stable growth driven by structured healthcare systems, strong nutrition awareness, and rising interest in plant-based wellness products. The Liquid Iron Supplements Market expands across Germany, France, the UK, and Nordic countries where consumers prioritize safety, transparency, and quality-certified formulations. It benefits from strict regulatory frameworks that promote high product consistency and labeling accuracy. Regional users adopt liquid iron supplements to support energy balance, immune function, and prenatal health. Retailers highlight clean-label and allergen-free products that appeal to environmentally conscious buyers. Public health initiatives address anemia prevalence, which sustains long-term consumption.
Asia-Pacific Emerges as the Fastest-Growing Region Due to Rising Anemia Burden and Expanding Healthcare Access
Asia-Pacific shows the strongest growth momentum driven by high rates of iron-deficiency anemia in India, China, and Southeast Asia. The Liquid Iron Supplements Market grows steadily because consumers gain better access to nutritional products through pharmacies, e-commerce platforms, and community clinics. It aligns with government programs focused on maternal health and child nutrition. Rising disposable incomes support higher spending on preventive wellness solutions. Local and international brands introduce affordable liquid formats that appeal to diverse income segments. Urbanization and lifestyle shifts increase awareness of micronutrient deficiencies, which strengthens long-term market potential.
Key Player Analysis:
- AdvaCare Pharma
- Aspen Pharmacare
- Feosol
- Kolinpharma SpA
- Kye Pharmaceuticals, Inc.
- Nemysis Ltd.
- Ortho Molecular Products
- Raffles Medical Group
- Shield Therapeutics plc
- Solvsotrin
Competitive Analysis:
The Liquid Iron Supplements Market features a diverse competitive landscape characterized by global pharmaceutical companies, specialized nutrition brands, and emerging innovators focusing on bioavailable and gentle formulations. Key players include AdvaCare Pharma, Aspen Pharmacare, Feosol, Kolinpharma SpA, Kye Pharmaceuticals, Inc., Nemysis Ltd., Ortho Molecular Products, Raffles Medical Group, Shield Therapeutics plc, and Solvotrin.
These companies invest in R&D to improve absorption, taste, and gastrointestinal tolerance, which strengthens product differentiation. It drives competition toward clean-label, plant-based, and pediatric-friendly formulations that meet evolving consumer expectations. Leading brands expand digital outreach and retail distribution to capture a wider user base across pharmacies, e-commerce platforms, and health clinics. Strategic collaborations allow firms to enhance clinical evidence, regulatory compliance, and geographic presence. Market participants emphasize innovation in formulation stability and packaging to maintain quality and extend shelf life.
Recent Developments:
- In November 2025, AdvaCare Pharma actively participated in the VIV MEA 2025 event in Abu Dhabi during November 25–27, marking its ongoing business development initiatives in the MENA region.
- In November 2024, Nemysis Ltd announced the successful acquisition of TFarma SRL by its wholly-owned subsidiary Enteralia Bioscience SRL, establishing a strong sales and distribution platform in Italy focused on women's health and gastroenterology.
Report Coverage:
The research report offers an in-depth analysis based on Product, Application, Form and Region. It details leading Market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current Market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven Market expansion in recent years. The report also explores Market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on Market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the Market.
Future Outlook:
- Rising focus on preventive healthcare will increase long-term demand for liquid iron across all age groups.
- Growing awareness of iron-deficiency anemia will strengthen adoption through physician guidance and public health programs.
- Expansion of clean-label, vegan, and allergen-free formulations will attract health-conscious consumers.
- Digital health platforms will improve adherence through personalized dosing recommendations and virtual consultations.
- E-commerce growth will enhance accessibility across emerging and remote markets.
- Improved taste-masking technologies will increase acceptance among pediatric and sensitive user groups.
- Stronger clinical evidence supporting high-absorption liquid formats will reinforce physician preference.
- Product diversification across flavored, sugar-free, and gentle-on-stomach variants will broaden the consumer base.
- Strategic partnerships between manufacturers and healthcare institutions will expand distribution networks.
- Innovation in packaging stability and shelf-life improvement will support global market competitiveness.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence of Iron-Deficiency Anemia
The increasing global incidence of iron-deficiency anemia, particularly among women, children, and the elderly, is driving demand for liquid iron supplements as a convenient and effective solution to address nutritional gaps and improve hemoglobin levels.
Preference for High-Absorption and Easy-to-Consume Formulations
Liquid iron supplements are favored for their superior bioavailability and ease of ingestion, especially among children, pregnant women, and individuals with swallowing difficulties or malabsorption disorders, leading to higher adoption rates.
Expansion of Preventive Healthcare and Nutrition Awareness
Growing consumer awareness of micronutrient insufficiency and the shift toward preventive healthcare encourage proactive iron supplementation, supported by physician recommendations and public health campaigns.
Wider Retail Availability and E-Commerce Growth
The expansion of retail channels, including pharmacies, online platforms, and specialty nutrition stores, has improved accessibility and convenience, making liquid iron supplements more readily available to a broader consumer base.
Innovation in Clean-Label and Gentle Formulations
Manufacturers are investing in clean-label, plant-based, sugar-free, and gentle-on-stomach liquid iron products, which appeal to health-conscious consumers and those with dietary restrictions, further fueling market growth.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Liquid Iron Supplements Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Liquid Iron Supplements Market expected to grow between 2024 and 2032?
What are the primary factors driving the growth of the liquid iron supplements market?
Are there specific populations or age groups that benefit most from liquid iron supplements?
What are the challenges associated with taste and palatability in liquid iron supplements, and how are they addressed?
Can liquid iron supplements cause digestive discomfort, and are there ways to minimize these effects?
How does the shelf life of liquid iron supplements compare to other iron supplementation?
What innovative formulations are being explored to improve the effectiveness and appeal of liquid iron supplements?
How is the distribution of liquid iron supplements evolving, and which channels are gaining prominence?
What is the growth potential of the liquid iron supplements market in the Asia Pacific region, and what factors are contributing to this growth?
Who are the leading companies in the Liquid Iron Supplements Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Form
- 1.2.1 Syrups
- 1.2.2 Droppers
- 1.2.3 Tinctures
- 1.2.4 Ampoules
- 1.3 By Product
- 1.3.1 Ferrous Gluconate
- 1.3.2 Ferrous Sulfate
- 1.3.3 Ferric Ammonium Citrate
- 1.3.4 Heme Iron
- 1.3.5 Plant-Based Iron
- 1.4 By Application
- 1.4.1 Pediatric
- 1.4.2 Prenatal
- 1.4.3 Adults
- 1.4.4 Geriatric
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 356.3 million → 2032: USD 629.33 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Liquid Iron Supplements Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Liquid Iron Supplements Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Liquid Iron Supplements Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Liquid Iron Supplements Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Liquid Iron Supplements Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Liquid Iron Supplements Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Liquid Iron Supplements Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Liquid Iron Supplements Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 356.3 million → 2032: USD 629.33 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Liquid Iron Supplements Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Form - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Syrups
- 12.3.7.2 Droppers
- 12.3.7.3 Tinctures
- 12.3.7.4 Ampoules
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Ferrous Gluconate
- 12.4.7.2 Ferrous Sulfate
- 12.4.7.3 Ferric Ammonium Citrate
- 12.4.7.4 Heme Iron
- 12.4.7.5 Plant-Based Iron
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Pediatric
- 12.5.7.2 Prenatal
- 12.5.7.3 Adults
- 12.5.7.4 Geriatric
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Liquid Iron Supplements End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Liquid Iron Supplements Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Liquid Iron Supplements Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Liquid Iron Supplements Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 AdvaCare Pharma
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Aspen Pharmacare
- 18.4 Feosol
- 18.5 Kolinpharma SpA
- 18.6 Kye Pharmaceuticals, Inc.
- 18.7 Nemysis Ltd.
- 18.8 Ortho Molecular Products
- 18.9 Raffles Medical Group
- 18.10 Shield Therapeutics plc
- 18.11 Solvotrin
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

