
Market Overview:
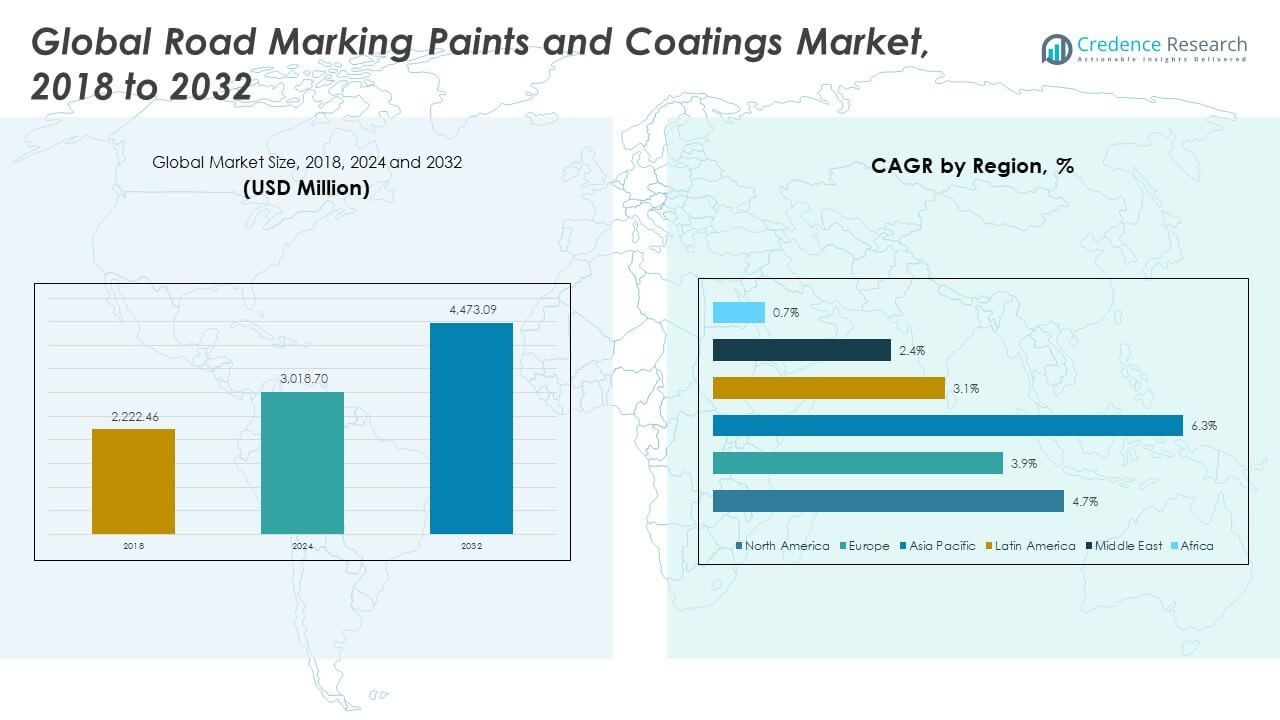
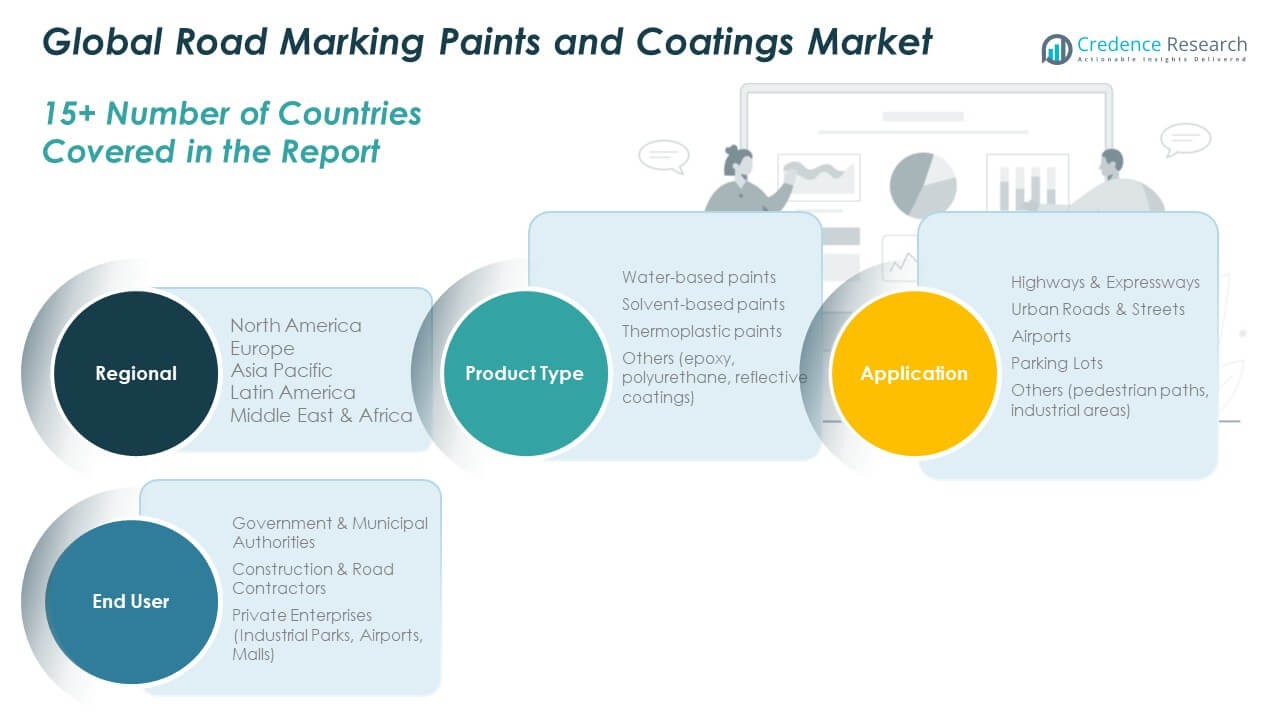
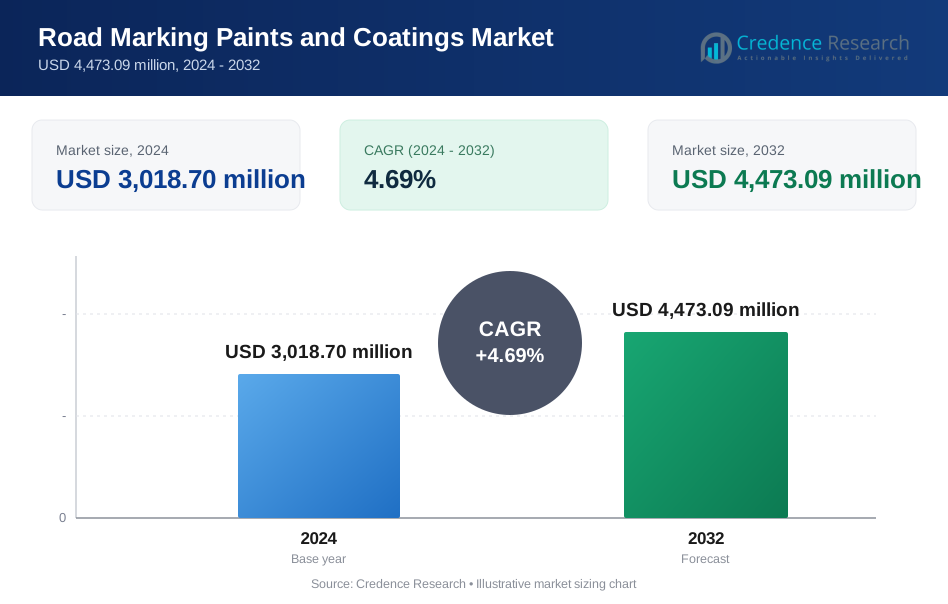
The Global Road Marking Paints and Coatings Market size was valued at USD 2,222.46 million in 2018 to USD 3,018.70 million in 2024 and is anticipated to reach USD 4,473.09 million by 2032, at a CAGR of 4.69% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Road Marking Paints and Coatings Market Size 2024 | USD 3,018.70 Million |
| Road Marking Paints and Coatings Market, CAGR | 4.69% |
| Road Marking Paints and Coatings Market Size 2032 | USD 4,473.09 Million |
Stronger driver programs, smart city expansion, and rising transportation density shape steady adoption. Agencies invest in high-performance thermoplastic, epoxy, and water-based formulas to enhance lane clarity and road safety. Pavement upgrades lift demand for longer-lasting markings that reduce repaint cycles. Cold-applied coatings gain attention due to safer handling and faster drying. Innovation in reflective glass beads helps improve night visibility. Many regions adopt sustainable formulas to reduce emissions and improve compliance with environmental rules, which further strengthens market growth.
North America leads due to advanced highway systems, strong safety standards, and steady maintenance budgets across large road networks. Europe follows with strict regulatory norms and high adoption of environment-friendly materials. Asia Pacific emerges as a fast-growing region driven by rapid urban development, new expressways, and rising vehicle population. China and India expand road programs to support economic growth. Latin America and the Middle East gain traction as governments invest in new transport corridors and upgrade older roads to improve mobility and logistics efficiency.
Market Insights:
- The Global Road Marking Paints and Coatings Market was valued at USD 2,222.46 million in 2018, reached USD 3,018.70 million in 2024, and is forecast to hit USD 4,473.09 million by 2032, growing at a CAGR of 4.69%.
- North America (43.15%), Europe (27.41%), and Asia Pacific (20.83%) hold the largest shares due to strong infrastructure programs, strict safety regulations, and rapid highway expansion supported by urban mobility upgrades.
- Asia Pacific, with a 83% share, is the fastest-growing region, driven by large-scale expressway development, rapid urbanization, and rising investments in durable and climate-resilient road marking systems.
- Segment distribution in the chart indicates water-based paints lead with roughly 35%, supported by environmental compliance and wider adoption across public projects.
- Solvent-based (≈25%), thermoplastic (≈20%), and others such as epoxy and polyurethane (≈20%) follow, reflecting diverse performance needs across weather conditions, traffic intensity, and application requirements.
Market Drivers:
Strong Expansion Of Road Modernization Programs And Traffic Safety Investments
Governments expand highway upgrades, boosting demand for consistent and durable lane markings. Agencies focus on structured safety efforts that require reliable visibility standards. The Global Road Marking Paints and Coatings Market gains support from rising roadway density. Investments in resurfacing programs encourage wider adoption of premium marking systems. Many regions adopt high-durability thermoplastic formulas to cut maintenance cycles. Cities push safer intersections, pedestrian crossings, and speed-calming zones. Road agencies explore low-toxicity and fast-drying compounds for smoother project execution. Public infrastructure funding creates a stable base for long-term consumption.
- For instance, Ennis-Flint’s preformed thermoplastic lines are certified to retain retroreflectivity above 300 mcd/m²/lux after extended wear cycles, supporting high-traffic corridor upgrades.
Rising Preference For High-Performance Coatings That Improve Durability And Visibility
High-performance marking solutions gain demand due to longer life and stronger reflectivity. Many buyers select coatings that maintain clarity under heavy traffic and harsh climates. Contractors depend on products that resist abrasion and fading. Climate-resilient formulas support better adhesion on wet, hot, and cold pavement. Agencies invest in reflective bead systems to raise night-time visibility. Thermoplastic and epoxy materials maintain sharp edges over extended cycles. Improved pigments support a stronger visual profile for lane guides. Sustained performance under pressure builds confidence in advanced coating options.
- For instance, 3M's All Weather Paint System, which integrates unique microcrystalline ceramic beads, is engineered to provide enhanced visibility in varied climates, with its most advanced elements achieving typical average wet continuous retroreflectivity levels up to 300 mcd/m²/lux and dry retroreflectivity reaching up to 1,250 mcd/m²/lux.
Growing Adoption Of Sustainable And Low-Emission Formulations Across Road Networks
Regulators push wider use of low-VOC and water-based road marking systems. Environmental policies motivate public and private operators to replace older solvent options. Water-based compounds support cleaner application processes with fewer hazards. Agencies promote greener maintenance strategies that protect workers and local communities. Pavement managers seek coatings that meet strict eco-compliance norms. Many cities implement climate-action targets that encourage sustainable material use. Research teams scale bio-based ingredients to reduce chemical footprints. Wider acceptance of these formulas creates stable demand for cleaner production.
Integration Of Advanced Technology To Support Safer, Smarter And Longer-Lasting Roadway Markings
Digital sensing, machine-vision systems, and automated vehicles require sharper road markings. Many road agencies prepare networks for driver-assist platforms that depend on clear lane boundaries. High-contrast coatings support machine readability under bright and low-light conditions. Pavement managers upgrade markings to support safe autonomous testing. OEMs recommend coatings with uniform reflectivity across long routes. Road designers select patterns compatible with emerging mobility systems. Durable bonds help markings remain consistent under heavy stress. It strengthens reliability across smart transportation corridors.
Market Trends:
Shift Toward Intelligent And Machine-Readable Road Markings For Connected Mobility
Smart transportation networks push interest toward coatings optimized for sensors and cameras. Road builders deploy high-contrast pigments for automated navigation. The Global Road Marking Paints and Coatings Market benefits from this shift toward digital compatibility. Engineers test coatings that maintain uniform brightness for machine-vision tools. Automated driving trials require markings that retain clarity after repeated stress. High-grade reflective systems help support precise lane detection. Wider use of ADAS vehicles encourages upgrades in older corridors. This trend strengthens alignment with future mobility systems.
- For instance, machine-vision systems for autonomous vehicles perform best on road markings with high-luminance contrast ratios, prompting industry partners to develop high-performance materials from suppliers like 3M and Swarco to help cities and road authorities adopt new standards.
Rapid Growth Of Cold-Applied And Quick-Cure Coatings For Faster Roadway Turnaround
Cold-applied formulas attract interest due to safer application and reduced downtime. Contractors use quick-cure compounds to reopen busy corridors sooner. Many cities support these formulas to reduce traffic disruption. Quick-set thermoplastic hybrids keep markings stable within short windows. Road authorities aim for smoother project schedules that avoid peak-hour delays. Products that cure well in humid or low-temperature environments gain attention. Flexible application options support emergency maintenance work. It improves productivity for small and large contractors.
- For instance, cold-applied methyl methacrylate (MMA) systems, such as the PlastiRoute MMA range from Geveko Markings, are formulated for rapid curing. These systems can be traffic-ready in as little as 15–30 minutes (at temperatures around 72°F/22°C), enabling the faster reopening of high-load zones, even at low temperatures through the adjustment of hardener levels.
Increasing Use Of High-Durability Glass Beads And Reflective Additives For Night Visibility
Reflective additives allow pavement guides to shine brighter under vehicle headlights. Manufacturers expand premium bead technologies for low-light zones. The Global Road Marking Paints and Coatings Market gains traction with stronger reflection properties. Road agencies deploy micro-prismatic bead systems for complex intersections. Improved refractive index values help stabilize visibility during rain. High-end bead mixtures support long-distance clarity on highways. Many testing units validate enhanced bind strength for rough conditions. Visibility upgrades align with national safety targets.
Growing Penetration Of Automated And Robotic Application Systems In Pavement Marking
Robotic applicators reduce labor pressure and improve line precision. Contractors adopt guided machines that ensure tighter edge quality. Automated rigs operate steadily across straight and curved paths. Digital controls help teams maintain uniform coating thickness. Road builders gain stronger project consistency through automated lines. Machine-guided sprayers reduce waste and improve repeatability. Precision application supports better long-term marking strength. Robotics adoption encourages major operators to refine large-scale resurfacing plans.
Market Challenges Analysis:
Volatile Raw Material Costs And Complex Environmental Compliance Requirements
Resin, pigment, and additive prices shift due to supply disruptions. Contractors face pressure when material volatility affects bid accuracy. The Global Road Marking Paints and Coatings Market experiences challenges when procurement cycles tighten. Environmental rules limit solvent usage in many regions. Producers adjust formulations to meet strict emission norms. Compliance testing slows product approvals across several markets. Smaller firms struggle with the cost of greener transitions. It creates pressure across supply chains during high-demand seasons.
Short Application Windows, Labor Shortages And Durability Issues In Harsh Environments
Many regions limit pavement work to specific seasons due to weather. Contractors manage tight timelines when rainfall or extreme temperatures disrupt plans. Skilled labor shortages raise project risks during peak cycles. Road markings degrade faster on heavy-traffic or rough-surface corridors. Agencies replace faded lines sooner than expected under intense wear. Remote zones lack consistent maintenance schedules. Unplanned failures reduce safety levels until new coatings are applied. Durability gaps strain public budgets across large road networks.
Market Opportunities:
Expansion Of Smart Cities, Expressway Networks And Machine-Vision-Ready Road Systems Smart city programs unlock long-term adoption of intelligent coatings. The Global Road Marking Paints and Coatings Market benefits as governments upgrade major routes. Connected vehicles require sharper and more durable lane markings. High-contrast pigments open opportunities in regions testing autonomous mobility. Digital-ready coatings support next-generation safety systems. Expressway expansion across developing countries raises new consumption routes. Large transport corridors create steady need for reflective solutions. It positions suppliers for sustained growth. Increasing Demand For Eco-Friendly, Low-VOC And Bio-Based Marking Solutions Eco-friendly paint systems unlock fresh demand across regulated regions. Buyers shift toward safer, low-emission formulas that support greener projects. Water-based coatings open major opportunities in urban roads and school zones. Bio-derived materials gain momentum among agencies seeking sustainable options. Compliance with climate targets boosts interest in clean chemistry. Producers refine recyclable packaging and lower-waste systems. Environmental support programs raise visibility for green offerings. It helps suppliers strengthen brand value across global markets. Market Segmentation Analysis:By Product Type
Thermoplastic paints lead due to strong durability and suitability for high-traffic routes. Water-based paints gain traction in regions with strict emission rules. Solvent-based paints remain relevant for quick-dry needs across varied climates. Cold plastic MMA coatings attract demand for long-life performance on critical lanes. Epoxy coatings support industrial safety lines where chemical resistance matters. Polyurea and polyurethane coatings deliver high elasticity and weather stability. Buyers select products based on climate, road density, and maintenance cycles. The Global Road Marking Paints and Coatings Market benefits from steady upgrades across these material categories.
- For instance, Sherwin-Williams’ polyurea marking systems show elongation rates above 300%, supporting durability under thermal expansion and heavy vehicle loads.
By Application
Roads and highways dominate due to continuous expansion of national networks. Streets and municipal roads require frequent repaint cycles to maintain clarity. Airport runways need precision coatings that withstand jet blast and heavy loads. Parking lots adopt cost-effective markings for smooth navigation. Pavements and pedestrian zones rely on anti-skid and high-visibility formulas. Factory markings support workflow safety and equipment guidance. Sports tracks use specialized pigments to maintain bright edges under regular use. High-performance coatings maintain relevance across all major surface types.
By End User
Government and municipal agencies drive major procurement due to regular maintenance mandates. Highway authorities allocate budgets for durable materials that reduce rework. Airports invest in long-lasting coatings that support safety rules. Commercial facilities use structured markings to improve customer flow. Industrial sites need chemical-resistant lines for operational safety. Private infrastructure developers adopt advanced solutions for new corridors. End users select materials that match operational pressure, climate exposure, and compliance requirements.
Segmentation:
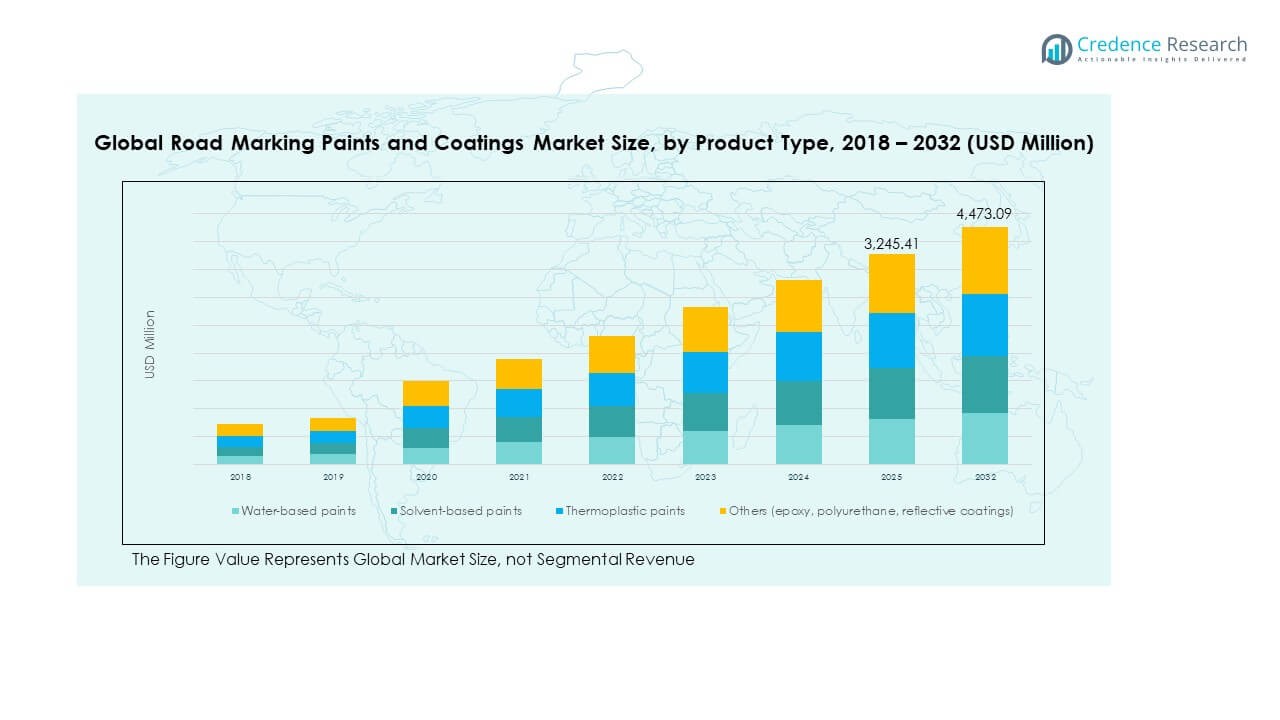
By Product Type
- Thermoplastic Paints
- Water-Based Paints
- Solvent-Based Paints
- Cold Plastic (MMA) Coatings
- Epoxy Coatings
- Polyurea / Polyurethane Coatings
By Application
- Roads & Highways
- Streets & Municipal Roads
- Airport Runways
- Parking Lots
- Pavements & Pedestrian Crossings
- Factory Markings
- Sports Tracks
By End User
- Government & Municipal Agencies
- Highway Authorities
- Airports
- Commercial Facilities
- Industrial Facilities
- Private Infrastructure Developers
By Region
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East
- Africa
Country-Level Breakouts (as per TOC)
North America
- U.S.
- Canada
- Mexico
Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
Asia Pacific
- China
- Japan
- India
- South Korea
- Southeast Asia
- Rest of Asia Pacific
Latin America
- Brazil
- Argentina
- Rest of Latin America
Middle East
- GCC Countries
- Rest of the Middle East
Africa
- South Africa
- Rest of Africa
Regional Analysis:
North America
Market Value Statement The North America Global Road Marking Paints and Coatings Market size was valued at USD 969.76 million in 2018 to USD 1,303.51 million in 2024 and is anticipated to reach USD 1,936.89 million by 2032, at a CAGR of 4.7% during the forecast period.
Regional Insights North America holds an estimated 43.15% market share in 2024, making it the leading region in the Global Road Marking Paints and Coatings Market. The region benefits from structured federal highway programs and high-quality road networks. It maintains strong adoption of thermoplastic and MMA coatings due to heavy traffic loads. State agencies prioritize reflectivity and long-term visibility across lane systems. Airports invest in durable runway coatings that withstand extreme operational pressure. Municipal bodies focus on repaint cycles that support urban flow efficiency. Contractors rely on advanced materials to improve drying time and reduce project delays. It continues to expand through modernization of interstate routes and safety-focused investments.
Europe
Market Value Statement The Europe Global Road Marking Paints and Coatings Market size was valued at USD 631.93 million in 2018 to USD 827.46 million in 2024 and is anticipated to reach USD 1,154.56 million by 2032, at a CAGR of 3.9% during the forecast period.
Regional Insights Europe accounts for an estimated 27.41% market share in 2024 driven by strict regulatory norms and sustainability goals. The region moves toward water-based coatings to meet emission limits. Western Europe adopts performance materials for highways with dense mobility patterns. Eastern Europe expands spending due to rapid road development programs. Airports across the region require robust coating systems for heavy aviation traffic. Municipalities upgrade pedestrian zones with anti-skid solutions. Industrial zones use epoxy markings to support safety workflow. The Global Road Marking Paints and Coatings Market gains strong traction here through long-term infrastructure plans.
Asia Pacific
Market Value Statement The Asia Pacific Global Road Marking Paints and Coatings Market size was valued at USD 427.47 million in 2018 to USD 629.32 million in 2024 and is anticipated to reach USD 1,056.16 million by 2032, at a CAGR of 6.3% during the forecast period.
Regional Insights
Asia Pacific secures an estimated 20.83% market share in 2024 and stands as the fastest-growing region. Expanding expressways across China and India fuel large-scale consumption. Southeast Asia upgrades urban corridors to manage rising vehicle density. Airports across the region expand capacity, strengthening demand for high-performance markings. Local agencies adopt thermoplastic and cold plastic solutions for tropical climates. Rapid industrialization increases factory marking requirements. Government-backed infrastructure programs drive continuous repaint cycles. It emerges as a central growth hub for suppliers seeking long-term volume expansion.
Latin America
Market Value Statement The Latin America Global Road Marking Paints and Coatings Market size was valued at USD 106.94 million in 2018 to USD 143.49 million in 2024 and is anticipated to reach USD 188.64 million by 2032, at a CAGR of 3.1% during the forecast period.
Regional Insights Latin America holds an estimated 4.75% market share in 2024 with gradual but steady adoption. Infrastructure upgrades in Brazil and Mexico support long-term demand. Urban expansion encourages new markings across local streets. Airports invest in runway safety programs to align with global aviation standards. Municipal bodies adopt cost-effective water-based and solvent-based formulas. Industrial parks require layout markings for safer movement patterns. Remote zones face maintenance delays due to logistics constraints. It strengthens its position through government-backed mobility improvements.
Middle East
Market Value Statement The Middle East Global Road Marking Paints and Coatings Market size was valued at USD 60.53 million in 2018 to USD 74.95 million in 2024 and is anticipated to reach USD 93.16 million by 2032, at a CAGR of 2.4% during the forecast period.
Regional Insights
The Middle East represents an estimated 2.48% market share in 2024 supported by heavy investment in national corridors. Gulf countries allocate strong budgets for expressway development. High-temperature climates increase demand for resilient thermoplastic materials. Airports maintain strong procurement cycles linked to aviation expansion. Urban centers apply reflective solutions to improve night visibility. Municipalities adopt water-based coatings for controlled emissions. Industrial sites expand road layouts to support logistics activities. It maintains stable growth due to structurally planned infrastructure programs.
Africa
Market Value Statement The Africa Global Road Marking Paints and Coatings Market size was valued at USD 25.83 million in 2018 to USD 39.97 million in 2024 and is anticipated to reach USD 43.67 million by 2032, at a CAGR of 0.7% during the forecast period.
Regional Insights
Africa accounts for an estimated 1.32% market share in 2024 with slow but emerging expansion. Many countries focus on upgrading national highways under development programs. Urban zones adopt basic thermoplastic and water-based systems. Airports expand steadily to support rising passenger volumes. Limited budgets create longer repaint cycles across municipalities. Industrial zones introduce structured marking layouts to improve safety. Climate stress requires durable formulas for hot and dry regions. The Global Road Marking Paints and Coatings Market gains selective traction where infrastructure investment rises.
Key Player Analysis:
- 3M
- Nippon Paint
- Asian Paints
- Jotun Paints
- Sherwin Williams
Competitive Analysis:
The Global Road Marking Paints and Coatings Market features strong competition driven by established manufacturers and regional suppliers. Companies invest in advanced resins, reflective systems, and long-life coatings to strengthen product performance. It benefits from growing innovation across thermoplastic, MMA, and water-based technologies. Players compete on durability, drying speed, environmental compliance, and application efficiency. Many firms expand distribution networks to capture high-volume public sector projects. Strategic partnerships with road contractors help boost visibility across major tenders. New entrants focus on value-driven offerings for municipal upgrades. Leading companies continue to improve formulations that address climate stress, heavy traffic loads, and safety standards.
Recent Developments:
- In August 2025, PPG and Asian Paints announced the renewal of their joint venture agreement in India with a 15-year extension through 2041. The partnership agreement began in 1997 with the formation of PPG Asian Paints Private Ltd., and expanded in 2012 with the creation of Asian Paints PPG Private Ltd. This venture specifically serves the protective and powder coatings market, including road marking paints. According to Tim Knavish, PPG chairman and CEO, "This decades-long relationship is a key success factor for our business in India".
- In March 2025, Nippon Paint Holdings completed the acquisition of AOC (LSF11 A5 TopCo LLC and its subsidiaries) for USD 2,194 million, making it a full subsidiary. AOC is a global specialty formulator with operations chiefly in the Americas and Europe, specializing in composite resins and materials. Additionally, Evonik Coating Additives and Nippon Paint China announced a strategic partnership in March 2025 focused on developing eco-friendly coating solutions. The collaboration aims to create next-generation products that meet consumers' growing demands for environmentally friendly coating solutions.
Report Coverage:
The research report offers an in-depth analysis based on Product Type and Application segments. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand will grow as more countries expand road modernization programs.
- Water-based coatings will gain share with rising environmental compliance needs.
- Thermoplastic and MMA systems will strengthen their presence on high-traffic routes.
- Digital-ready markings will rise due to autonomous and connected mobility.
- Airports will invest in durable systems that support higher flight movement.
- Urban centers will prioritize high-visibility coatings for pedestrian safety.
- Suppliers will expand technology partnerships with infrastructure developers.
- Reflective bead innovation will improve nighttime visibility on major highways.
- Eco-friendly materials will shape procurement trends across regulated regions.
- Global vendors will focus on durability, climate resistance, and fast-application chemistry.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expansion of Road Modernization and Safety Programs
Governments worldwide are investing in highway upgrades and structured safety initiatives, which require consistent and durable road markings to enhance visibility and reduce accidents. This drives demand for advanced marking paints and coatings that can withstand heavy traffic and environmental stress.
Rising Preference for High-Performance and Durable Coatings
There is increasing adoption of thermoplastic, epoxy, and MMA-based coatings due to their superior durability, abrasion resistance, and ability to maintain clarity under harsh weather and traffic conditions. These high-performance solutions reduce repaint cycles and maintenance costs, fueling market growth.
Shift Toward Sustainable and Low-Emission Formulations
Stricter environmental regulations and climate action targets are pushing agencies and contractors to adopt water-based and low-VOC road marking paints. The move toward eco-friendly and bio-based materials is expanding the market, especially in regions with strong regulatory compliance.
Integration of Advanced Technology for Smart and Machine-Readable Markings
The rise of smart cities and autonomous vehicles is increasing the need for digital-ready, high-contrast, and machine-readable road markings. Investments in reflective bead technology and coatings optimized for sensors and cameras are supporting the evolution of connected mobility infrastructure.
Rapid Urbanization and Expressway Development in Emerging Markets
Asia Pacific and other developing regions are experiencing rapid urban growth and large-scale expressway construction, which is significantly boosting the consumption of road marking paints and coatings for new and upgraded transport corridors.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Global Road Marking Paints and Coatings Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Global Road Marking Paints and Coatings Market projected to grow between 2025 and 2032?
Which Global Road Marking Paints and Coatings Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Global Road Marking Paints and Coatings Market?
Who are the leading companies in the Global Road Marking Paints and Coatings Market?
Which region commanded the largest share of the Global Road Marking Paints and Coatings Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Government & Municipal Agencies
- 1.2.2 Highway Authorities
- 1.2.3 Airports
- 1.2.4 Commercial Facilities
- 1.2.5 Industrial Facilities
- 1.2.6 Private Infrastructure Developers
- 1.3 By Application
- 1.3.1 Roads & Highways
- 1.3.2 Streets & Municipal Roads
- 1.3.3 Airport Runways
- 1.3.4 Parking Lots
- 1.3.5 Pavements & Pedestrian Crossings
- 1.3.6 Factory Markings
- 1.3.7 Sports Tracks
- 1.4 By Product Type
- 1.4.1 Thermoplastic Paints
- 1.4.2 Water-Based Paints
- 1.4.3 Solvent-Based Paints
- 1.4.4 Cold Plastic (MMA) Coatings
- 1.4.5 Epoxy Coatings
- 1.4.6 Polyurea / Polyurethane Coatings
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 3,018.70 million → 2032: USD 4,473.09 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Road Marking Paints and Coatings Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Road Marking Paints and Coatings Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Road Marking Paints and Coatings Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Road Marking Paints and Coatings Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Road Marking Paints and Coatings Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Road Marking Paints and Coatings Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Road Marking Paints and Coatings Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Road Marking Paints and Coatings Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 3,018.70 million → 2032: USD 4,473.09 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Road Marking Paints and Coatings Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Government & Municipal Agencies
- 12.3.7.2 Highway Authorities
- 12.3.7.3 Airports
- 12.3.7.4 Commercial Facilities
- 12.3.7.5 Industrial Facilities
- 12.3.7.6 Private Infrastructure Developers
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Roads & Highways
- 12.4.7.2 Streets & Municipal Roads
- 12.4.7.3 Airport Runways
- 12.4.7.4 Parking Lots
- 12.4.7.5 Pavements & Pedestrian Crossings
- 12.4.7.6 Factory Markings
- 12.4.7.7 Sports Tracks
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Thermoplastic Paints
- 12.5.7.2 Water-Based Paints
- 12.5.7.3 Solvent-Based Paints
- 12.5.7.4 Cold Plastic (MMA) Coatings
- 12.5.7.5 Epoxy Coatings
- 12.5.7.6 Polyurea / Polyurethane Coatings
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Road Marking Paints and Coatings End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Road Marking Paints and Coatings Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Road Marking Paints and Coatings Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Road Marking Paints and Coatings Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 3M
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Nippon Paint
- 18.4 Asian Paints
- 18.5 Jotun Paints
- 18.6 Sherwin Williams
- 18.7 PPG Industries
- 18.8 Geveko Markings
- 18.9 Swarco
- 18.10 Ennis-Flint
- 18.11 Axalta Coating Systems
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

