
Long Steel Products Market Overview:
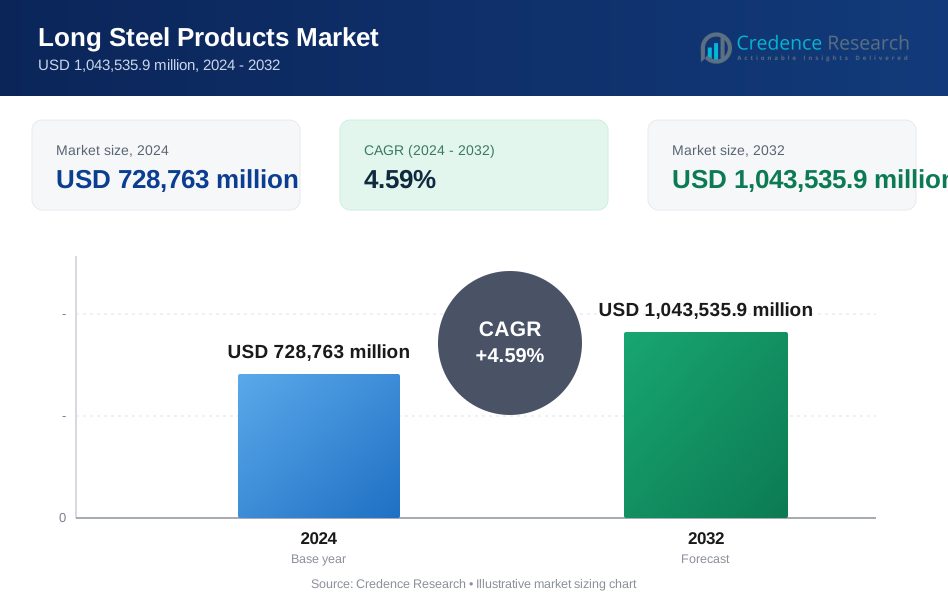
The Long Steel Products Market size was valued at USD 728,763 million in 2024 and is anticipated to reach USD 1,043,535.9 million by 2032, growing at a CAGR of 4.59% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Long Steel Products Market Size 2024 | USD 728,763 million |
| Long Steel Products Market, CAGR | 4.59% |
| Long Steel Products Market Size 2032 | USD 1,043,535.9 million |
Long Steel Products Market Insights
- Growth is driven by large-scale infrastructure development, urban housing projects, railway expansion, and rising industrial construction demand across emerging and developed economies.
- Rebars dominated the product segment with a 8% share in 2024, while Building & Construction led end-use demand with a 61.3% share, supported by reinforced concrete structures and public infrastructure investments.
- Market trends highlight increasing adoption of high-strength steel grades, expansion of recycling-based production, and investments in low-carbon manufacturing to meet sustainability and regulatory requirements.
- Asia Pacific led regional demand with a 6% market share in 2024, followed by North America at 17.4% and Europe at 15.8%, supported by infrastructure modernization, transportation upgrades, and industrial activity.

Long Steel Products Market Segmentation Analysis:
By Product:
The Long Steel Products Market, by product, is led by Rebars, which accounted for 44.8% market share in 2024, driven by their extensive use in residential, commercial, and infrastructure construction for reinforced concrete structures. Rebars dominate due to rising urbanization, large-scale public infrastructure investments, and strict building safety regulations across emerging and developed economies. Wire Rods follow, supported by demand from fasteners and welding applications, while Sections benefit from structural steel usage in bridges and industrial buildings. Tubes maintain steady demand from mechanical and structural applications, supported by industrial expansion.
- For instance, POSCO, JSW Steel, and NMDC operate significant iron ore mining or sourcing operations to fuel steelmaking, with verified production figures demonstrating their contributions.
By End-use:
By end-use, the Building & Construction segment dominated with a 61.3% market share in 2024, supported by strong demand for rebars and sections in housing, commercial complexes, and large infrastructure projects. Government-backed infrastructure development, smart city initiatives, and rising private construction investments are key growth drivers. Railways & Highway applications continue to expand due to track modernization and road network expansion, while Automotive & Aerospace demand is driven by chassis and structural components. Other end-uses, including industrial manufacturing, contribute steadily through machinery and fabrication demand.
- For instance, Aldar adopted EMSTEEL’s hydrogen-based steel rebar for Abu Dhabi’s first net-zero carbon mosque in Sustainable City Yas Island, marking a MENA regional first in low-emission construction materials.
Key Growth Drivers
Expanding Infrastructure and Construction Investments
The Long Steel Products Market continues to benefit from sustained investments in infrastructure and construction across both developed and emerging economies. Large-scale projects such as highways, bridges, rail corridors, metros, and urban housing programs are driving strong demand for rebars, sections, and wire rods. Government-led initiatives focused on smart cities, affordable housing, and industrial corridors are accelerating steel consumption. In addition, rapid urbanization and population growth are increasing the need for durable construction materials, reinforcing long steel’s critical role in structural reinforcement and load-bearing applications.
- For instance, ArcelorMittal Europe supplied over 20,000 tonnes of B500SP EPSTAL rebars (10-32 mm diameter) for the Warsaw Metro M2 line's 10 new stations, ensuring compliance with safety standards in this major urban transit expansion.
Industrialization and Manufacturing Expansion
Accelerated industrialization and growth in manufacturing activities are key contributors to the Long Steel Products Market. Expansion of heavy industries, machinery manufacturing, shipbuilding, and fabrication units is increasing demand for sections, rods, and tubes with high tensile strength and durability. Developing economies are witnessing rising investments in industrial parks and production facilities, boosting structural steel usage. Furthermore, modernization of existing manufacturing infrastructure and increased focus on domestic production capabilities are supporting consistent consumption of long steel products across industrial end-use segments.
- For instance, Sambhv Steel Tubes approved a ₹50 crore expansion in 2025 to double its cold rolled and galvanized coil capacity from 58,000 MT to 116,000 MT annually at its Raipur facility, targeting ERW pipes and structural tubes.
Transportation and Railway Network Development
Ongoing expansion and modernization of transportation infrastructure significantly drive demand in the Long Steel Products Market. Railways, highways, ports, and airport developments require large volumes of rails, sections, and reinforcement bars for tracks, bridges, and supporting structures. Governments are prioritizing rail electrification, high-speed rail corridors, and expressway construction to improve logistics efficiency. These projects demand long steel products with enhanced strength and fatigue resistance, supporting stable long-term market growth across transportation and mobility applications.
Key Trends & Opportunities
Shift Toward High-Strength and Specialty Long Steel Products
The market is witnessing a growing shift toward high-strength, low-alloy, and specialty long steel products designed to improve structural efficiency and reduce material usage. Construction and infrastructure developers increasingly prefer advanced grades that offer superior load-bearing capacity, corrosion resistance, and extended service life. This trend creates opportunities for manufacturers to invest in value-added products, premium rebars, and customized sections. Adoption of advanced metallurgy and rolling technologies is enabling producers to differentiate offerings and improve margins in competitive markets.
- For instance, Nucor's Aeos ASTM A913 high-strength structural steel provides a superior strength-to-weight ratio over traditional A992 grades, enabling fewer tons for the same load in urban high-rises and distribution centers.
Sustainability Initiatives and Low-Carbon Steel Production
Rising emphasis on sustainability and carbon reduction is shaping new opportunities in the Long Steel Products Market. Steel producers are increasingly adopting electric arc furnaces, recycling-based production, and energy-efficient manufacturing processes to lower emissions. Demand for environmentally responsible construction materials is growing, especially in developed regions with strict environmental regulations. This trend encourages innovation in green steel production and strengthens partnerships between steelmakers and infrastructure developers focused on achieving sustainability targets.
- For instance, Tata Steel Nederland launched Zeremis Carbon Lite, a green steel product offering a 30% reduction in CO2 intensity versus the European average through process optimizations like biomethane deployment and regenerative thermal oxidation systems.
Key Challenges
Volatility in Raw Material Prices
Fluctuating prices of key raw materials such as iron ore, coking coal, and scrap steel remain a major challenge for the Long Steel Products Market. Sudden cost variations directly impact production economics and profit margins, making pricing strategies difficult for manufacturers. Supply disruptions, geopolitical tensions, and changes in mining output further intensify price instability. Smaller producers are particularly vulnerable, as limited hedging capabilities restrict their ability to absorb cost shocks while remaining competitive.
Overcapacity and Intense Market Competition
Global overcapacity and intense competition pose persistent challenges for the Long Steel Products Market. Several regions continue to experience excess production capacity, leading to pricing pressure and reduced profitability. Aggressive exports, especially from low-cost manufacturing countries, intensify competition in domestic markets. Additionally, trade restrictions and tariffs create uncertainty in cross-border steel flows. Manufacturers must focus on operational efficiency, product differentiation, and regional demand alignment to sustain long-term competitiveness.
Regional Analysis
Asia Pacific
Asia Pacific dominated the Long Steel Products Market with a 52.6% market share in 2024, supported by rapid urbanization, large-scale infrastructure development, and strong construction activity across China, India, Japan, and Southeast Asia. High demand for rebars and sections from residential housing, railways, highways, and industrial projects continues to drive regional growth. Government investments in smart cities, metro rail networks, and renewable infrastructure further strengthen consumption. The presence of large domestic steel producers, expanding manufacturing bases, and favorable government policies sustains Asia Pacific’s leadership in both production and consumption of long steel products.
North America
North America accounted for a 17.4% market share in 2024, driven by infrastructure modernization, commercial construction, and transportation upgrades in the United States and Canada. Increased investments in highways, bridges, and rail rehabilitation programs are boosting demand for rebars, sections, and wire rods. The region benefits from stable industrial activity, strong automotive manufacturing, and rising adoption of high-strength steel products. Additionally, government funding for infrastructure renewal and reshoring of manufacturing activities supports consistent long steel consumption across construction and industrial end-use sectors.
Europe
Europe captured a 15.8% market share in 2024, supported by renovation of aging infrastructure, sustainable construction practices, and steady demand from industrial and transportation sectors. Countries such as Germany, France, Italy, and Spain contribute significantly through residential refurbishment, rail network expansion, and commercial construction. Stringent environmental regulations are driving demand for high-quality and low-carbon long steel products. Investments in renewable energy projects, including wind and grid infrastructure, further support regional demand, while established steel manufacturing capabilities maintain stable supply across the market.
Latin America
Latin America held a 7.1% market share in 2024, driven by infrastructure development and construction growth in Brazil, Mexico, and Argentina. Government-backed housing programs, road expansion projects, and industrial development initiatives are increasing demand for rebars and sections. The region benefits from rising urban population and gradual recovery in industrial activities. Local steel production capacity and increasing investments in transportation infrastructure support steady market growth, while improving economic stability encourages long-term construction and manufacturing investments.
Middle East & Africa
The Middle East & Africa represented a 7.1% market share in 2024, supported by large-scale infrastructure projects, urban development, and industrial diversification efforts. Gulf countries drive demand through mega construction projects, smart cities, and transportation networks, while African markets benefit from growing residential construction and basic infrastructure development. High demand for rebars and structural sections remains central to regional growth. Government-led investment programs and increasing private sector participation continue to strengthen long steel consumption across construction and industrial applications.
Long Steel Products Market Segmentations:
By Product
- Rebars
- Wire Rods
- Sections
- Tubes
By End-use
- Building & Construction
- Automotive & Aerospace
- Railways & Highway
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Competitive landscape of the Long Steel Products Market is shaped by major players such as ArcelorMittal, Nippon Steel Corporation, Tata Steel, POSCO, BHP Group, Steel Authority of India Limited, JFE Steel Corporation, Celsa Group, Gerdau S.A., and Emirates Steel. The market is characterized by a mix of global integrated steelmakers and strong regional producers competing on product quality, scale, and cost efficiency. Companies focus on expanding rebar and structural steel capacities to address rising construction and infrastructure demand. Strategic investments in electric arc furnaces, recycling-based production, and low-carbon steel initiatives strengthen positioning amid tightening environmental regulations. Capacity expansions, regional production optimization, and long-term supply contracts with construction and infrastructure developers remain key strategies, while technological upgrades and value-added long steel grades support differentiation and margin stability.
Key Player Analysis
- Gerdau S.A.
- Nippon Steel Corporation
- Emirates Steel
- BHP Group
- Celsa Group
- Steel Authority of India Limited
- POSCO
- Tata Steel
- JFE Steel Corporation
- ArcelorMittal
Recent Developments
- In December 2025, JFE Steel Corporation and JSW Steel Limited announced a 50:50 joint venture to acquire and operate Bhushan Power & Steel Limited's integrated steel facility in Odisha, India, focusing on expanding crude steel production capacity to 10 million tons by 2030, including long products like bars and wire rods.
- In December 2025, Tata Steel and Lloyds Metals & Energy Ltd signed a Memorandum of Understanding to explore joint opportunities in iron ore mining, a greenfield 6 million tons steel capacity development, and cooperation on long products projects in Maharashtra.
- In July 2025, Tata Steel’s indirect subsidiary acquired the remaining 40% stake in TSN Wires Company, consolidating ownership and strengthening its wire and long steel product offerings.
Report Coverage
The research report offers an in-depth analysis based on Product, End Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Long Steel Products Market will continue expanding due to sustained infrastructure and construction activity across emerging and developed economies.
- Government investments in highways, railways, metros, and urban housing will strengthen long-term demand for rebars and structural sections.
- Adoption of high-strength and advanced-grade long steel products will increase to improve structural efficiency and durability.
- Sustainability initiatives will accelerate the shift toward electric arc furnace production and recycling-based steel manufacturing.
- Demand from railways and transportation projects will remain a stable growth contributor over the forecast period.
- Manufacturers will focus on capacity optimization and regional production balance to address demand fluctuations.
- Technological upgrades in rolling and metallurgy processes will enhance product quality and cost efficiency.
- Rising urbanization in Asia Pacific and Africa will support consistent long steel consumption.
- Strategic partnerships with construction and infrastructure developers will improve market reach and order stability.
- Regulatory emphasis on safety standards and environmental compliance will shape product innovation and investment priorities.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Long Steel Products Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Long Steel Products Market projected to grow between 2024 and 2032?
Which Long Steel Products Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Long Steel Products Market?
Who are the leading companies in the Long Steel Products Market?
Which region commanded the largest share of the Long Steel Products Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 728,763 million → 2032: USD 1,043,535.9 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Long Steel Products Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Long Steel Products Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Long Steel Products Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Long Steel Products Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Long Steel Products Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Long Steel Products Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Long Steel Products Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Long Steel Products Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 728,763 million → 2032: USD 1,043,535.9 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Long Steel Products Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Long Steel Products Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Long Steel Products Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Long Steel Products Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

