
Market Overview:
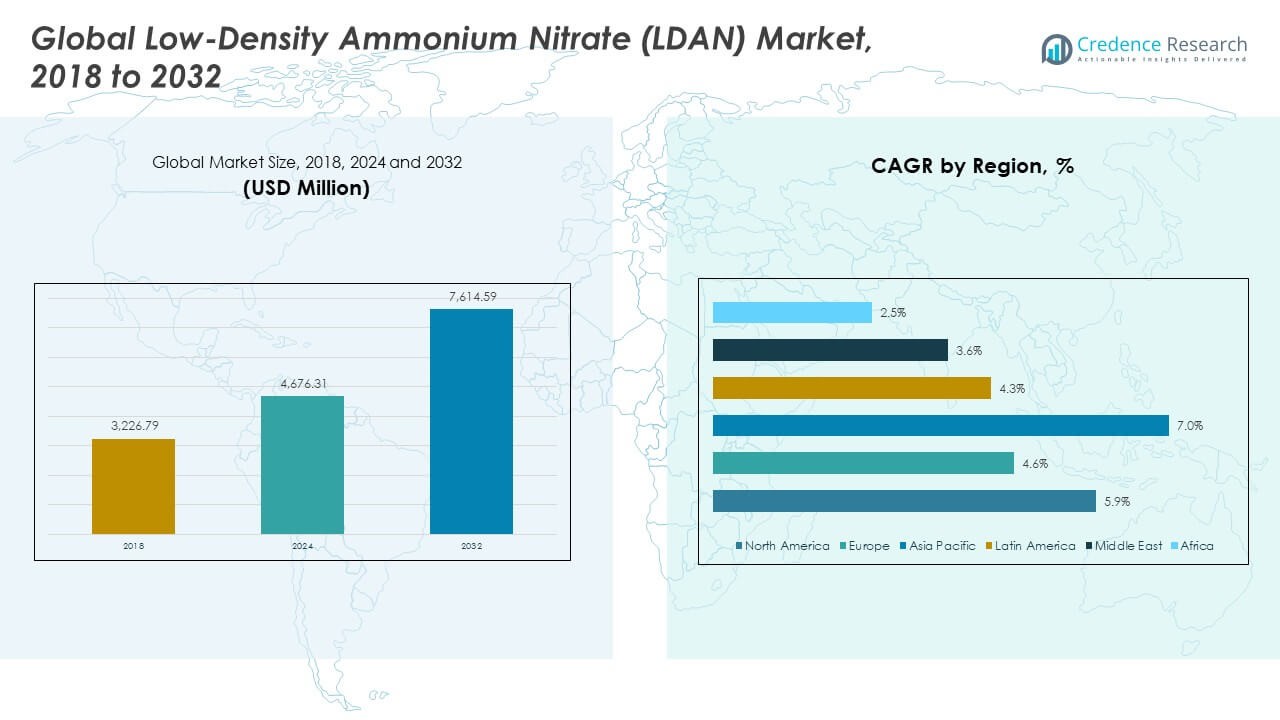
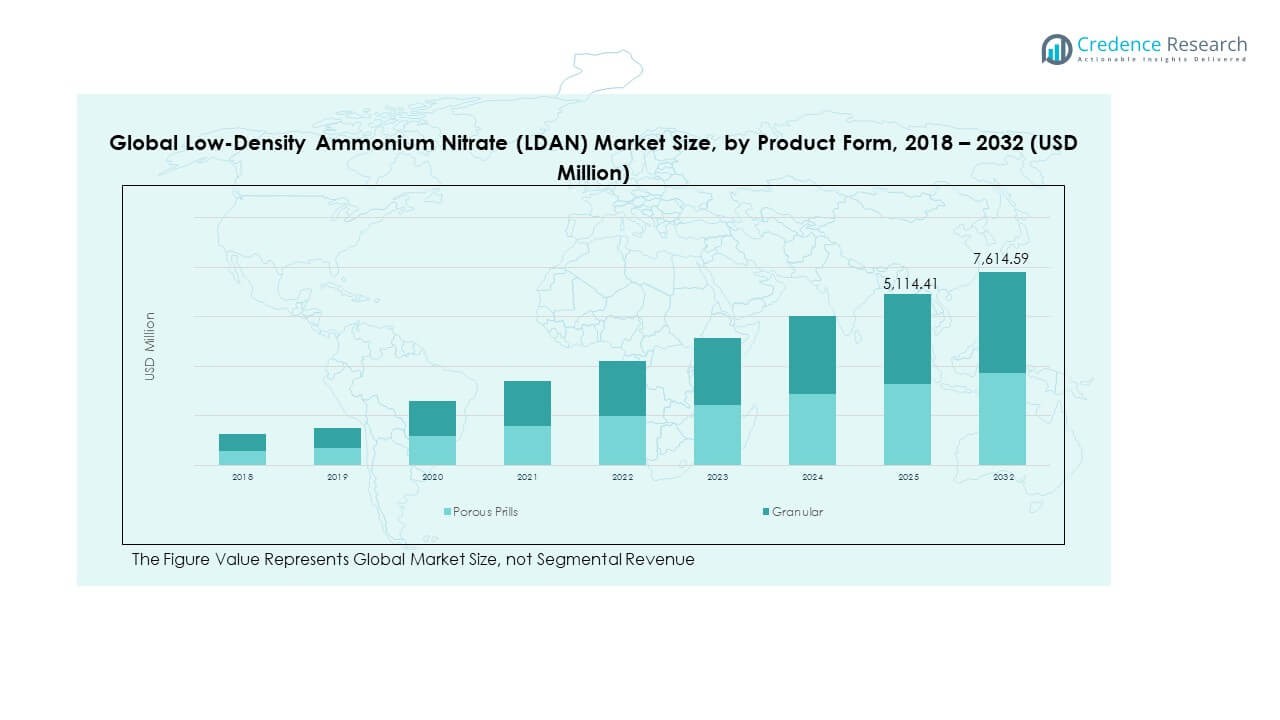
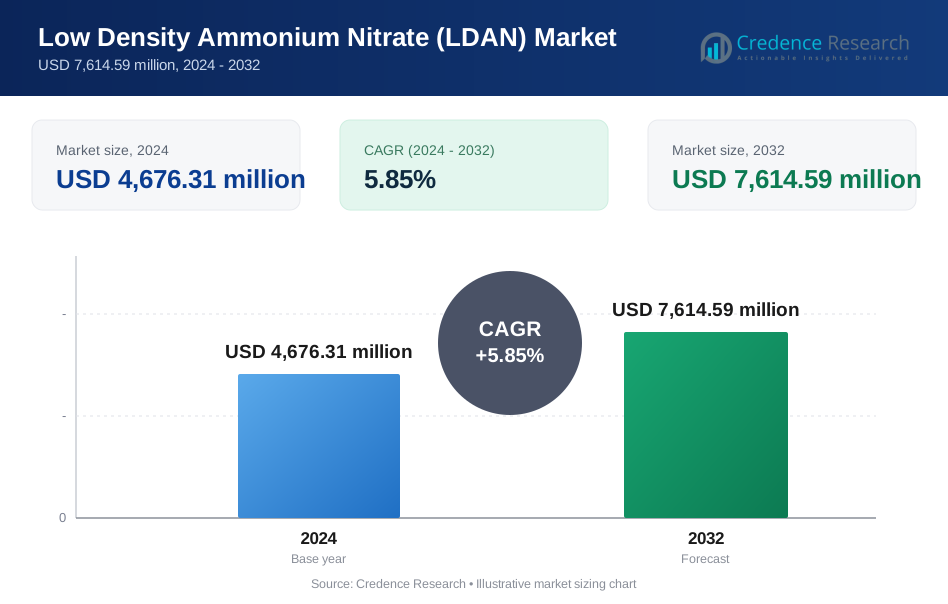
The Low-Density Ammonium Nitrate (LDAN) Market size was valued at USD 3,226.79 million in 2018 to USD 4,676.31 million in 2024 and is anticipated to reach USD 7,614.59 million by 2032, at a CAGR of 5.85% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Low-Density Ammonium Nitrate (LDAN) MarketSize 2024 | USD 4,676.31 Million |
| Low-Density Ammonium Nitrate (LDAN) Market, CAGR | 5.85% |
| Low-Density Ammonium Nitrate (LDAN) Market Size 2032 | USD 7,614.59 Million |
Demand rises due to strong industrial and mining activity. Explosives producers rely on LDAN for consistent blast performance in large sites. Construction firms use it to manage expanding infrastructure programs. Steady growth in quarrying and tunneling lifts consumption. Growing energy and metal extraction boosts adoption across global operations.
North America leads due to strong mining, quarrying, and energy extraction projects. The region benefits from mature production lines and stable raw material access. Asia Pacific emerges fast due to rising construction, rapid mineral exploration, and expanding industrial zones. Countries in the region support LDAN use through growing infrastructure plans and higher explosives demand. Europe maintains steady uptake due to controlled mining and strict quality norms. Latin America gains traction through rising copper, gold, and iron ore extraction. Africa sees growing interest from large mining corridors.
Market Insights:
- The Global Low-Density Ammonium Nitrate (LDAN) Market was valued at USD 3,226.79 million in 2018, reached USD 4,676.31 million in 2024, and is projected to hit USD 7,614.59 million by 2032, supported by a 5.85% CAGR driven by steady mining, quarrying, and construction activity.
- North America (42.68%) leads due to strong open-pit mining, efficient supply chains, and high adoption of controlled blasting. Asia Pacific (30.34%) follows with rapid industrialization and heavy mineral extraction. Europe (18.10%) maintains a stable share backed by regulated quarrying and tunneling projects.
- Asia Pacific is the fastest-growing region, supported by rising metal demand, expansion of large infrastructure corridors, and increased use of engineered prills across diverse geological settings.
- Porous Prills hold the larger share in the product form segmentation, representing an estimated 55% of total usage due to their superior detonation sensitivity and suitability for large mining blasts.
- Granular LDAN accounts for roughly 45%, supported by consistent use in controlled demolition, smaller blasting applications, and markets requiring improved handling stability.
 Market Drivers:
Strong Expansion of Mining, Quarrying, and Large-Scale Extraction Activities
Mining operators lift demand due to rising ore extraction needs across major regions. Many firms depend on LDAN for stable detonation in deep and complex sites. Large quarries use it to support uniform blast outcomes across varied rock conditions. Construction contractors deploy it for tunneling work and controlled ground removal. Energy projects need reliable blasting input to open new drilling zones. Growing investment in mineral exploration strengthens long-term consumption. Expanding quarry operations lift procurement across industrial belts. The Global Low-Density Ammonium Nitrate (LDAN) Market gains steady traction due to strong extraction cycles.
- For instance, Orica’s BlastIQ digital blasting platform increased fragmentation accuracy by up to 25%, strengthening LDAN performance in high-volume mines.
Growth in Infrastructure Development and Mega Construction Programs Worldwide
Governments push large road, rail, and tunnel projects that require controlled blasting. Contractors depend on LDAN to manage rock displacement across hard terrains. Infrastructure plans create sustained demand across transport corridors and energy hubs. Urban expansion increases excavation work across dense regions. Mining-linked construction activities lift parallel demand from service contractors. Renewable energy farms need site-clearing work for equipment placement. Ports and industrial parks require land shaping at larger depth levels. High project intensity drives consistent LDAN consumption across global markets.
- For instance, Dyno Nobel’s DigiShot® Plus 4G electronic initiation system enables timing precision within 0.01 milliseconds, improving blast control in large tunneling and construction zones.
Rising Adoption of Bulk Explosives and Automated Blasting Systems in Industrial Operations
Bulk explosive units use LDAN for predictable output across wide blast patterns. Automation in charging systems improves blast timing and accuracy. Large mine fleets rely on optimized blends that lift safety margins. Firms integrate LDAN into on-site mixing trucks to support efficient delivery. Automated control panels help maintain uniform density across complex blasts. Industrial players value stable handling performance under variable climates. It strengthens adoption in high-volume operations that require high precision. Reliability lifts LDAN uptake across long-term extraction cycles.
Increased Demand from Expanding Energy, Metal Recovery, and Resource Development Projects
Strong metal demand in global supply chains pushes extraction activity higher. Energy producers open new fields that require rock clearing. Metal recycling programs support new mining zones due to supply constraints. Resource development in remote belts increases LDAN usage. Firms invest in advanced blasting methods to reduce operational delays. Stable product flow supports quick field deployment across rough terrains. Demand intensifies where mineral reserves sit deeper underground. The market grows due to rising resource exploration commitments.
Market Trends:
Shift Toward Environment-Focused Formulations and Safer Blasting Solutions
Producers create cleaner LDAN blends that support lower emission needs. Firms refine granulation techniques to reduce dust formation during handling. Safer formulations help contractors meet strict site compliance rules. Governments push safety audits that encourage controlled use practices. Product innovation lifts interest in low-impact blasting inputs. It supports consistent adoption in regulated mining corridors. Safer packaging formats reduce moisture risk across long transport routes. The Global Low-Density Ammonium Nitrate (LDAN) Market tracks stronger movement toward eco-focused and safe-use materials.
- For instance, Yara’s specialized ammonium nitrate formulations use specific production technologies and additives to reduce particulate matter, which can help industrial operators meet strict environmental compliance standards regarding air quality during processes such as handling or the charging of blast holes.
Rising Integration of Digital Monitoring and Blast Optimization Platforms
Digital platforms guide blast patterns using real-time geological inputs. Firms track density variations through automated sensors. Remote systems help operators manage explosive distribution with high accuracy. Data tools reduce misfires in large extraction sites. AI-based modeling supports improved fragmentation gains. Digital control raises safety metrics across high-risk zones. It offers better predictability for mine productivity improvements. Adoption rises as operators shift toward precision-driven workflows.
- For instance, Epiroc’s Mobilaris Mining Intelligence system processes location data with under 1-second delay, reducing safety incidents and improving blast readiness across deep mining zones.
Increasing Focus on Supply Chain Reinforcement and Regional Production Hubs
Producers build new plants near mining belts to reduce transit risk. Supply chain teams diversify sourcing plans for stable raw material availability. Localized production improves delivery speed to remote sites. Firms design flexible storage units for climate-controlled stock. Many operators prefer regional suppliers for fast replenishment cycles. It boosts resilience against cross-border delays and volatility. Long-term contracts help maintain stable procurement planning. Regional hubs strengthen industry stability across heavy-use regions.
Growing Use of LDAN in Emerging Blasting Technologies and Advanced Fragmentation Methods
New blasting methods require precise density control across each charge point. Firms refine LDAN to support advanced fragmentation outcomes. Technology suppliers build systems that match LDAN flow to digital blast maps. Improved porosity control enhances detonation sensitivity. Advanced mining fleets adopt refined blends for deeper operations. Contractors use engineered blends to reduce oversize formation. It encourages wider use across technologically advanced extraction regions. The trend aligns with strong investment in modern mining equipment.
 Market Challenges Analysis:
Volatile Raw Material Costs and Strict Global Regulatory Oversight Impact Production Stability
Producers face unstable ammonia and gas feedstock prices that affect cost planning. Price swings reduce margins across long-term supply contracts. Regulatory frameworks increase compliance pressure across every stage. Safety rules restrict storage formats in many countries. Transport limits tighten handling protocols across land and port systems. Firms invest in monitoring systems to track regulatory changes. It increases operating cost for producers and distributors. The Global Low-Density Ammonium Nitrate (LDAN) Market must manage these constraints to maintain reliable supply.
Rising Environmental Scrutiny, Safety Incidents, and Complex Logistics Challenge Market Expansion
Environmental groups monitor emissions from explosive-grade chemicals in active regions. Safety incidents create higher approval barriers across mining zones. Some countries impose strict clearance rules for imports and on-site storage. Logistics networks face risk from long-distance movement across harsh climates. Port delays disrupt timely loading cycles for industrial clients. Firms adopt strict packaging norms to reduce moisture issues during transit. It increases complexity for suppliers that operate in multiple regions. Market players work to secure resilient distribution networks under these conditions.
Market Opportunities:
Growth in New Mining Districts, Deep-Ore Exploration, and Large Infrastructure Corridors
Emerging mining belts in Africa, Asia, and Latin America create strong growth space. Deep-ore exploration programs rely on LDAN for controlled and reliable blasts. Infrastructure corridors across developing regions need extensive excavation. Governments support major public works that expand usage over long timelines. Resource firms invest in high-volume blasting programs that require steady LDAN flow. It opens long-term opportunities for producers that scale supply. The Global Low-Density Ammonium Nitrate (LDAN) Market benefits from structural growth in new industrial regions. Expansion into frontier resource zones lifts future demand.
Rising Potential from Automation, Digital Blast Design, and Advanced Explosive Formulations
Automation tools increase demand for LDAN that supports precise control. Digital blast design platforms use LDAN inputs to optimize fragmentation. Advanced formulations open new applications across complex geological profiles. Mining operators seek products that improve energy output stability. Firms pursue partnerships with digital solution providers to enhance performance. It supports new service models that integrate explosives, data, and field execution. The opportunity widens as global mining shifts toward technology-driven operations.
Market Segmentation Analysis:
Product Form Segments
Porous prills lead consumption due to strong demand from large mines that need uniform porosity and stable detonation. Granular grades hold a steady share where controlled density and easy handling support diverse blasting work. The Global Low-Density Ammonium Nitrate (LDAN) Market gains strength from rising adoption of engineered prill structures across complex geological settings. Each form segment supports specific fragmentation goals in field operations.
- For instance, Uralchem produces low-density AN porous prills with oil absorption rates above 10%, enabling superior fuel integration and reliable detonation in large blasting patterns.
Application Segments
Surface blasting dominates due to extensive use across open-pit mines and quarry belts. Underground blasting maintains strong uptake where safe ignition and predictable output guide deep extraction work. Controlled demolition relies on LDAN for precise break patterns in urban or industrial zones. Specialized explosive formulations expand with demand for tailored blends that enhance energy transfer and fragmentation quality.
- For instance, Enaex’s RioFlex™ emulsion blends achieve excellentwater resistance, improving detonation reliability in both surface and underground blasting conditions.
End-User Industry Segments
Mining remains the core demand center due to high-volume explosive cycles. Construction uses LDAN for excavation, tunneling, and site preparation. Quarrying depends on it for stable rock fragmentation that supports aggregate supply. Agriculture reflects limited use, tied mainly to ammonium nitrate applications in specific regions. Defense agencies deploy controlled-grade LDAN for structured training and field activities.
Packaging Type & Distribution Channel Segments
Bulk packaging leads where mines require continuous supply and efficient loading. Bagged packaging meets small-scale needs across construction and quarry sites. Direct sales dominate structured contracts with large operators. Distributors serve regional markets with flexible delivery networks. Online platforms gain interest from small buyers, while industrial supply chains support long-term procurement for heavy users.
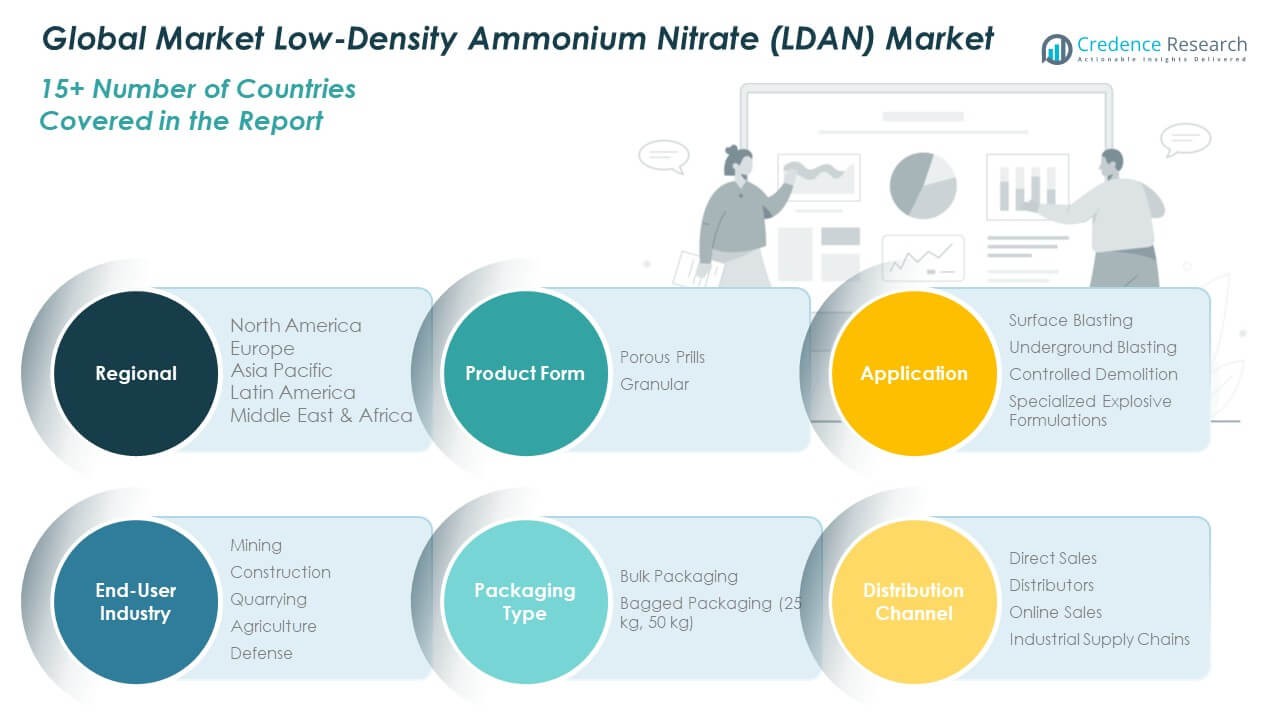
Segmentation:
Product Form Segments
- Porous Prills
- Granular
Application Segments
- Surface Blasting
- Underground Blasting
- Controlled Demolition
- Specialized Explosive Formulations
End-User Industry Segments
- Mining
- Construction
- Quarrying
- Agriculture
- Defense
Packaging Type Segments
- Bulk Packaging
- Bagged Packaging (25 kg, 50 kg)
Distribution Channel Segments
- Direct Sales
- Distributors
- Online Sales
- Industrial Supply Chains
Regional Segments
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Country-Level Segments
- U.S.
- Canada
- Mexico
- UK
- France
- Germany
- Italy
- Spain
- Russia
- China
- Japan
- South Korea
- India
- Australia
- Southeast Asia
- Brazil
- Argentina
- GCC Countries
- Israel
- Turkey
- South Africa
- Egypt
 Regional Analysis:
North America
The North America Global Low-Density Ammonium Nitrate (LDAN) Market size was valued at USD 1,391.84 million in 2018 to USD 1,995.87 million in 2024 and is anticipated to reach USD 3,259.08 million by 2032, at a CAGR of 5.9% during the forecast period. North America holds 42.68% share due to strong mining, quarrying, and energy extraction activity. Large open-pit mines in the U.S. drive continuous LDAN consumption across deep and complex zones. Canada supports growth through metal recovery projects and stable industrial blasting demand. Mexico adds momentum with expanding limestone and metal extraction belts. Regional firms deploy advanced blast optimization tools that improve efficiency. It benefits from strong safety standards that promote controlled formulations. Infrastructure upgrades in transport and energy corridors support stable long-term need. Strategic investments in production units reinforce secure LDAN supply across North America.
Europe
The Europe Global Low-Density Ammonium Nitrate (LDAN) Market size was valued at USD 617.07 million in 2018 to USD 846.44 million in 2024 and is anticipated to reach USD 1,256.46 million by 2032, at a CAGR of 4.6% during the forecast period. Europe holds 18.10% share due to stable use of LDAN in regulated mining and quarry operations. Demand grows in Nordic regions with rising metal extraction activity. Central Europe maintains steady consumption due to infrastructure tunneling and controlled blasting rules. Eastern Europe lifts use through new mineral exploration programs. Safety-focused regulations guide adoption of engineered prills and low-impact explosives. It shows consistent demand from construction work across dense urban zones. Regional suppliers invest in compliant packaging to meet strict handling rules. Growth remains moderate but stable across developed industrial belts.
Asia Pacific
The Asia Pacific Global Low-Density Ammonium Nitrate (LDAN) Market size was valued at USD 927.20 million in 2018 to USD 1,419.17 million in 2024 and is anticipated to reach USD 2,521.34 million by 2032, at a CAGR of 7.0% during the forecast period. Asia Pacific holds 30.34% share driven by extensive mining in China, Australia, and India. Strong construction activity lifts LDAN consumption across large excavation sites. Indonesia and Vietnam expand use through coal, metal, and industrial mineral extraction. Regional infrastructure projects accelerate controlled blasting needs. It benefits from a large supplier ecosystem that supports bulk delivery. Governments approve new mining licenses that raise long-term demand. Rapid industrialization pushes quarrying growth across major economic corridors. Technology adoption improves blast precision across complex terrain.
Latin America
The Latin America Global Low-Density Ammonium Nitrate (LDAN) Market size was valued at USD 155.64 million in 2018 to USD 222.81 million in 2024 and is anticipated to reach USD 322.00 million by 2032, at a CAGR of 4.3% during the forecast period. Latin America holds 4.76% share with strong uptake from mining hubs in Brazil, Chile, and Peru. Copper and iron ore mining drive consistent LDAN demand across large pits. Construction activity across the region supports controlled blasting in transport corridors. Expanding quarry operations add steady consumption from aggregate supply chains. Regional producers scale distribution networks to serve remote belts. It gains support from regulatory frameworks that manage explosive use. Industrial zones adopt advanced blast systems to lift fragmentation efficiency. Growth stays linked to global demand for critical minerals.
Middle East
The Middle East Global Low-Density Ammonium Nitrate (LDAN) Market size was valued at USD 90.74 million in 2018 to USD 120.24 million in 2024 and is anticipated to reach USD 165.34 million by 2032, at a CAGR of 3.6% during the forecast period. The region holds 2.57% share supported by quarrying and infrastructure expansion. Gulf countries use LDAN for large excavation projects in industrial and urban development zones. Mining activity grows slowly but remains steady in select belts. Infrastructure programs in transport and logistics drive controlled blasting. It gains traction from growing construction linked to energy diversification plans. Regional suppliers focus on compliant packaging due to strict safety rules. Demand strengthens where major civil works need precise blasting. Market growth stays tied to long-term urban expansion.
Africa
The Africa Global Low-Density Ammonium Nitrate (LDAN) Market size was valued at USD 44.29 million in 2018 to USD 71.77 million in 2024 and is anticipated to reach USD 90.37 million by 2032, at a CAGR of 2.5% during the forecast period. Africa holds 1.53% share dominated by mining corridors in South Africa, Ghana, and Tanzania. Gold, copper, and diamond extraction lift steady LDAN use. Quarrying contributes through rising construction material demand. Infrastructure programs create controlled blasting needs across transport networks. Remote mining belts require stable supply chains for explosives. It gains support from new exploration licenses issued across mineral-rich regions. Regional safety rules shape procurement and storage practices. Growth remains gradual but supported by long-term mineral demand.
Key Player Analysis:
Competitive Analysis:
The Global Low-Density Ammonium Nitrate (LDAN) Market reflects strong competition among integrated chemical producers and specialized explosive firms. Leading companies focus on capacity expansion, safer formulations, and efficient distribution. Firms invest in advanced granulation systems that improve density control and burn stability. Supply chain strength plays a major role in securing contracts with mines and quarry operators. It benefits from long-term agreements that ensure consistent volume flow. Competitors enhance digital support tools to improve blast planning and operational safety. Regional players gain ground through localized storage hubs and faster delivery cycles. Strategic moves focus on production optimization, compliance upgrades, and partnerships with blasting service companies.
Recent Developments:
- In November 2025, Dyno Nobel inaugurated two major manufacturing expansions at its Soma facility in Türkiye. The shock tube manufacturing facility has an annual production capacity of 57 million meters, with commissioning scheduled for November 2025 and production commencing in December 2025. The electronics assembly line produces Digishot® electronic detonators with an initial capacity of 132,000 units annually, with commissioning completed in September 2025 and production beginning in November 2025. The dual-project investment represents a combined capital expenditure of approximately AUD$1.9 million.
- In September 2025, Yara International signed a binding 10-year offtake agreement with project developer Atome for 260,000 tonnes per year of low-carbon calcium ammonium nitrate (CAN) from Atome's Villeta project in Paraguay. Atome will use hydropower to produce renewable ammonia feedstock for the CAN facility, which is strategically located near key fertilizer markets in Brazil and Argentina. The agreement was built upon Heads of Terms announced on July 24, 2024, and represents the last commercial milestone before Final Investment Decision, with FID and start of construction targeted for before the end of 2025.
- In August 2025, BASF and Yara jointly decided to discontinue their project to develop a low-carbon ammonia production facility with carbon capture and storage in the U.S. Gulf Coast region. Both companies chose to focus on initiatives with the highest potential to achieve their respective value creation goals.
- In January 2024, Dyno Nobel (Incitec Pivot Limited) announced a non-binding Memorandum of Understanding with Saudi Chemical Company Limited (SCCL) to investigate the development and operation of a technical ammonium nitrate plant in Saudi Arabia. The joint venture will develop a 300,000 MTPA TAN plant in Ras Al-Khair, Eastern Province of Saudi Arabia. Dyno Nobel will provide Front End Engineering Design and project services expertise for the facility, which would supply technical ammonium nitrate and nitric acid to Saudi regional mining and industrial users while enabling Dyno Nobel to supply TAN to its international mining customer base. This partnership aligns with Dyno Nobel's strategy to expand manufacturing operations and sales in the Europe, Middle East, and Africa (EMEA) region.
Report Coverage:
The research report offers an in-depth analysis based on product form segments, application segments, end-user industry segments, packaging type segments, and distribution channel segments. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand rises due to expanding mining and quarrying activities across major regions.
- Product innovations support safer formulations with better handling properties.
- Digital blast design tools increase adoption of engineered LDAN prills.
- Regional supply chains strengthen with new storage hubs near mining belts.
- Infrastructure development drives rising demand for controlled blasting work.
- Deep-ore extraction projects create long-term opportunities for high-quality LDAN blends.
- Producers invest in automation to improve consistency and reduce operational cost.
- Regulatory compliance drives improvements in packaging and transport safety.
- Partnerships between explosive firms and mining contractors enhance service models.
- Technology upgrades improve fragmentation efficiency across large excavation sites.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Global Low-Density Ammonium Nitrate (LDAN) Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Global Low-Density Ammonium Nitrate (LDAN) Market projected to grow between 2025 and 2032?
Which Global Low-Density Ammonium Nitrate (LDAN) Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Global Low-Density Ammonium Nitrate (LDAN) Market?
Who are the leading companies in the Global Low-Density Ammonium Nitrate (LDAN) Market?
Which region commanded the largest share of the Global Low-Density Ammonium Nitrate (LDAN) Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Low Density Ammonium Nitrate (LDAN) Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Low Density Ammonium Nitrate (LDAN) Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 4,676.31 million → 2032: USD 7,614.59 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Low Density Ammonium Nitrate (LDAN) Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Low Density Ammonium Nitrate (LDAN) Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Low Density Ammonium Nitrate (LDAN) Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Low Density Ammonium Nitrate (LDAN) Market Drivers
- 3.3 Low Density Ammonium Nitrate (LDAN) Market Restraints & Challenges
- 3.4 Low Density Ammonium Nitrate (LDAN) Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Low Density Ammonium Nitrate (LDAN) Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Low Density Ammonium Nitrate (LDAN) Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Low Density Ammonium Nitrate (LDAN) category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Low Density Ammonium Nitrate (LDAN) Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Low Density Ammonium Nitrate (LDAN) Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Low Density Ammonium Nitrate (LDAN) market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Low Density Ammonium Nitrate (LDAN) Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Low Density Ammonium Nitrate (LDAN) Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Low Density Ammonium Nitrate (LDAN) Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Low Density Ammonium Nitrate (LDAN) (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Low Density Ammonium Nitrate (LDAN) Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Low Density Ammonium Nitrate (LDAN) Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Low Density Ammonium Nitrate (LDAN) Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Low Density Ammonium Nitrate (LDAN) Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Low Density Ammonium Nitrate (LDAN) Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Low Density Ammonium Nitrate (LDAN) Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Low Density Ammonium Nitrate (LDAN) Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Low Density Ammonium Nitrate (LDAN) Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Low Density Ammonium Nitrate (LDAN) Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
