
Machining Market Overview:
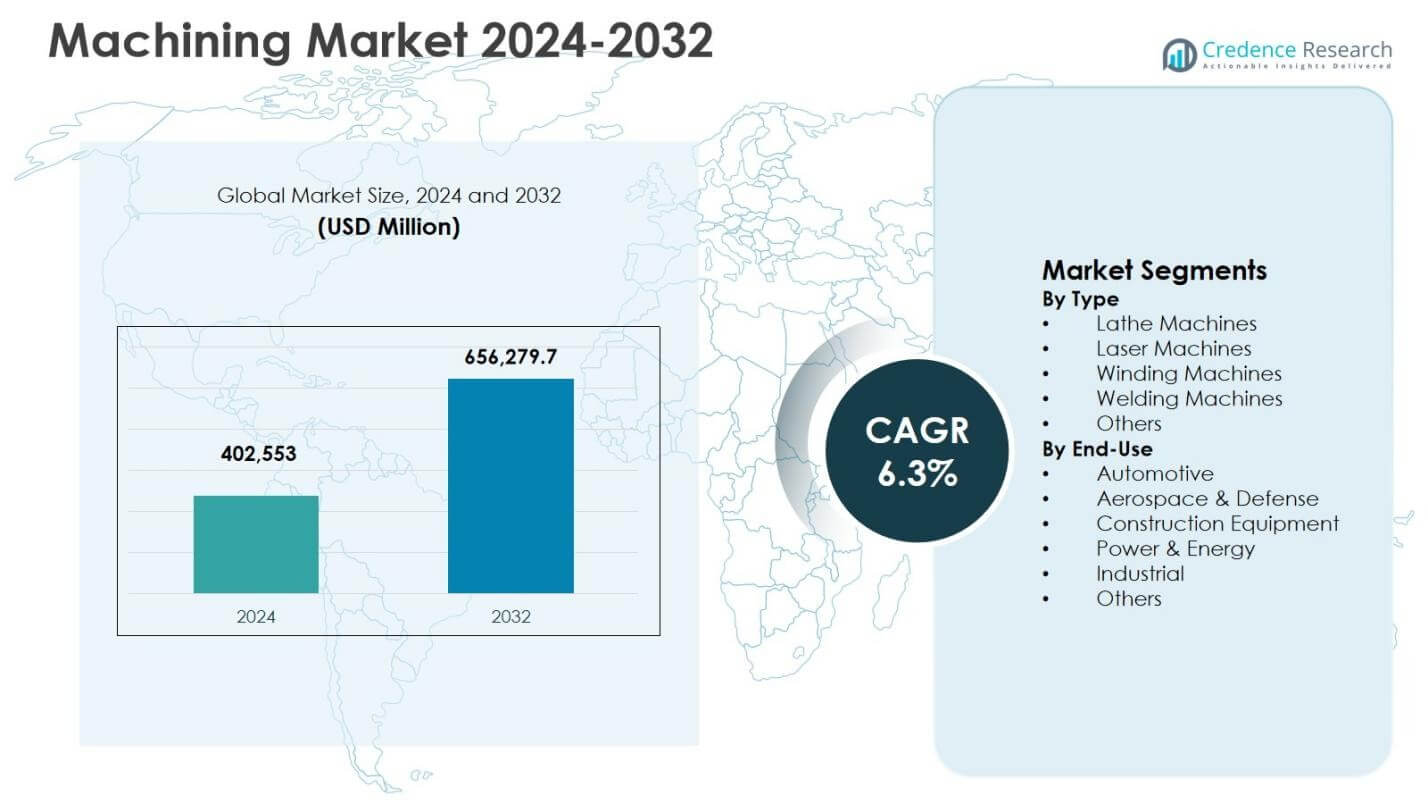
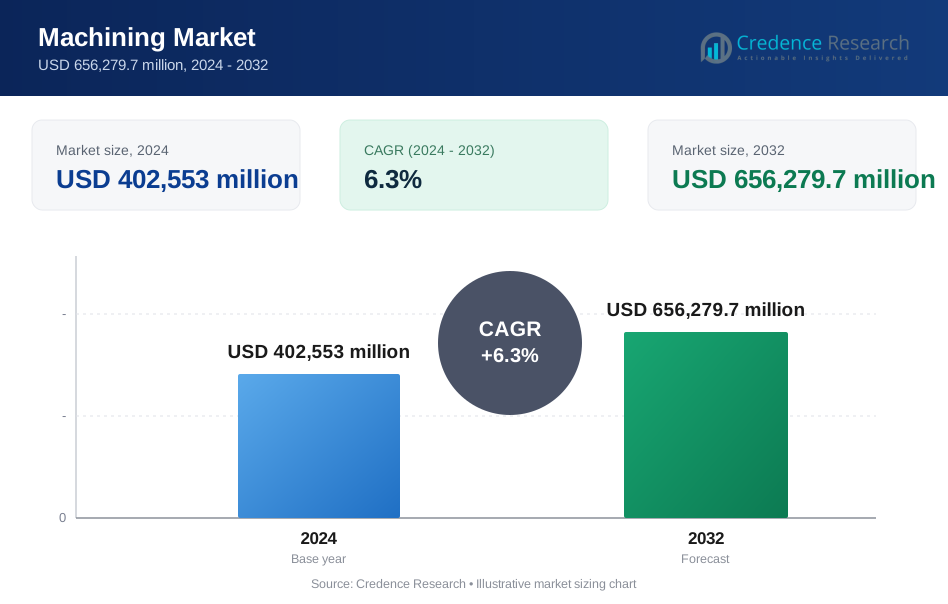
The Machining Market size was valued at USD 402,553 million in 2024 and is anticipated to reach USD 656,279.7 million by 2032, expanding at a CAGR of 6.3% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Machining Market Size 2024 | USD 402,553 million |
| Machining Market, CAGR | 6.3% |
| Machining Market Size 2032 | USD 656,279.7 million |
Machining Market Insights
- Market growth is driven by rising automotive and electric vehicle production, increased demand for precision components, and expanding adoption of CNC, automation, and smart manufacturing technologies across industrial sectors.
- Lathe machines led the Machining Market by type with a 8% share in 2024, supported by their versatility, CNC compatibility, and extensive use in automotive and industrial manufacturing applications.
- Ongoing investments in multi-axis machining, laser-based systems, and digital integration strengthen market positioning of major players while supporting productivity, accuracy, and cost efficiency across end-use industries.
- Asia Pacific dominated the Machining Market with a 9% share in 2024, followed by North America at 24.8% and Europe at 21.6%, driven by large-scale manufacturing, automotive output, and industrial automation adoption.
Machining Market Segmentation Analysis:
By Type:
The Machining Market, by type, is led by Lathe Machines, which accounted for 31.8% market share in 2024, driven by their extensive use in metal cutting, turning, threading, and shaping across automotive, industrial machinery, and general manufacturing applications. Lathe machines remain essential due to their versatility, compatibility with CNC integration, and ability to deliver high precision at scale. Growing demand for customized components, increasing adoption of CNC lathes, and rising investments in smart manufacturing systems continue to reinforce the dominance of lathe machines over laser machines, winding machines, welding machines, and other specialized machining equipment.
- For instance, Mayer & Cie invested in DMG Mori CNC lathes to automate turning, drilling, grinding, and thread cutting for circular knitting machine components like support rings and needle beds, advancing core production toward greater efficiency.
By End-Use:
By end-use, the Automotive segment dominated the Machining Market with a 34.6% share in 2024, supported by high-volume production of engine components, transmission systems, braking parts, and structural assemblies. Continuous vehicle production, rising demand for electric vehicles, and stringent tolerance requirements significantly drive machining demand in this segment. Automotive manufacturers increasingly deploy advanced CNC machining, automation, and multi-axis systems to enhance productivity and precision. Strong OEM and Tier-1 supplier investments, coupled with lightweight material processing needs, further strengthen the automotive sector’s leadership over aerospace & defense, construction equipment, and power & energy end uses.
- For instance, Volkswagen invested mid-double-digit millions over five years in metal binder jetting technology with HP and Siemens for production parts like A-pillar components, achieving 50% weight reduction versus steel while enabling up to 100,000 annual 3D-printed metal parts by 2025.
Key Growth Drivers
Expansion of Automotive and Electric Vehicle Manufacturing
The Machining Market benefits significantly from the expansion of automotive and electric vehicle manufacturing worldwide. Rising vehicle production volumes, increasing electrification, and stricter performance and safety standards are driving demand for precision-machined components such as powertrain parts, motor housings, battery enclosures, and lightweight structural elements. Automotive OEMs and Tier-1 suppliers increasingly rely on advanced machining solutions to achieve tight tolerances, high repeatability, and cost efficiency at scale. The shift toward electric and hybrid vehicles further accelerates machining demand due to the need for new component architectures, high-precision metal parts, and advanced material processing capabilities.
- For instance, Kennametal developed a 3D-printed stator bore tool with a carbon-fiber body and RIQ inserts to machine large-diameter electric motor housings, enabling three diameters in one operation with reduced cycle time and weight under 7kg for faster tool changes.
Growth of Industrial Automation and Smart Manufacturing
Rapid adoption of industrial automation and smart manufacturing technologies is a major growth driver for the Machining Market. Manufacturers are investing in CNC machines, multi-axis systems, robotics integration, and digital monitoring tools to improve productivity, reduce downtime, and enhance machining accuracy. Smart machining solutions enable real-time process optimization, predictive maintenance, and consistent quality output, which are critical in high-volume and high-precision manufacturing environments. The integration of Industry 4.0 technologies supports faster production cycles and lower operational costs, making advanced machining systems essential across automotive, aerospace, industrial equipment, and energy sectors.
- For instance, GE implements AI-driven predictive maintenance using machine learning on sensor data from manufacturing equipment to detect anomalies and prevent breakdowns.
Rising Demand from Aerospace, Defense, and Energy Sectors
Increasing demand from aerospace, defense, and energy industries strongly supports Machining Market growth. These sectors require complex, high-precision components made from advanced materials such as titanium, superalloys, and hardened steels. Aircraft production expansion, defense modernization programs, and investments in power generation infrastructure drive sustained machining demand. Machining processes are critical for producing turbine parts, structural components, and high-stress assemblies that meet strict regulatory and performance standards. Long-term contracts, high component value, and continuous technological upgrades in these industries ensure stable and recurring demand for advanced machining solutions.
Key Trends & Opportunities
Adoption of Advanced CNC and Multi-Axis Machining Technologies
The increasing adoption of advanced CNC and multi-axis machining technologies represents a key trend and opportunity in the Machining Market. Manufacturers are shifting toward five-axis and hybrid machining systems to produce complex geometries with fewer setups and higher accuracy. These technologies enable faster production cycles, improved surface finishes, and reduced material waste. The trend supports demand from aerospace, automotive, and medical device manufacturing, where component complexity is rising. Continuous advancements in software, tooling, and automation further enhance machining capabilities, creating opportunities for equipment providers and service operators to deliver higher-value, technology-driven solutions.
- For instance, Hoedtke GmbH & Co. KG uses DMG MORI's LASERTEC 65 3D hybrid machine, combining laser deposition welding with 5-axis simultaneous milling for complete machining of challenging workpieces in a single setup since 2014.
Growing Opportunities in Customization and Small-Batch Manufacturing
Rising demand for customized components and small-batch production creates significant opportunities in the Machining Market. End users increasingly seek flexible machining solutions that support rapid prototyping, short production runs, and design customization without compromising precision. This trend is driven by product differentiation strategies, shorter product life cycles, and growing demand for specialized industrial components. Advanced machining centers with quick changeovers, digital programming, and automation capabilities enable manufacturers to respond efficiently to varied customer requirements. Customization-focused machining services also open new revenue streams across automotive aftermarket, industrial machinery, and emerging technology sectors.
- For instance, TiRapid used small-batch CNC machining to produce 80 test parts for an automotive company's new model suspension system crash testing, enabling rapid verification without costly tooling.
Key Challenges
High Capital Investment and Operational Costs
High capital investment and operational costs present a major challenge for the Machining Market. Advanced machining equipment, including CNC and multi-axis systems, requires substantial upfront expenditure, which can limit adoption among small and medium-sized manufacturers. In addition, costs related to skilled labor, tooling, maintenance, and energy consumption add to operational burdens. Frequent technology upgrades and the need for software integration further increase total ownership costs. These financial constraints can slow modernization efforts, especially in cost-sensitive regions, impacting overall market penetration of advanced machining solutions.
Skilled Labor Shortage and Technical Complexity
The shortage of skilled labor and increasing technical complexity pose significant challenges to the Machining Market. Advanced machining systems require trained operators, programmers, and maintenance personnel capable of handling sophisticated software, automation, and precision tooling. Many regions face gaps in technical education and workforce readiness, leading to higher training costs and productivity risks. As machining processes become more complex, errors, downtime, and quality issues can increase without adequate expertise. Addressing this challenge requires continuous workforce development, training programs, and collaboration between equipment manufacturers and industrial users.
Regional Analysis
North America
The Machining Market in North America accounted for 24.8% market share in 2024, supported by strong demand from automotive, aerospace & defense, and industrial manufacturing sectors. The region benefits from high adoption of CNC machining, automation, and multi-axis technologies across the United States and Canada. Continuous investments in advanced manufacturing, reshoring of production activities, and defense modernization programs drive sustained machining demand. The presence of established OEMs, skilled workforce availability, and strong focus on precision engineering further strengthen regional growth. Increasing adoption of smart factories and digital manufacturing solutions continues to enhance machining productivity and output quality.
Europe
Europe captured 21.6% market share in 2024 in the Machining Market, driven by robust industrial manufacturing, automotive production, and aerospace engineering across Germany, France, Italy, and the United Kingdom. Strong emphasis on high-precision machining, advanced tooling, and sustainable manufacturing practices supports regional demand. European manufacturers actively invest in energy-efficient machines, digitalized production lines, and Industry 4.0 integration to improve operational efficiency. The region’s well-developed automotive supply chain, growing electric vehicle production, and focus on advanced materials contribute to steady demand for machining solutions across industrial and high-value manufacturing applications.
Asia Pacific
Asia Pacific dominated the Machining Market with a 38.9% market share in 2024, led by China, Japan, India, and South Korea. Rapid industrialization, expanding automotive production, and strong growth in electronics and heavy machinery manufacturing drive high machining demand. The region benefits from large-scale manufacturing capacity, cost-efficient labor, and increasing adoption of CNC and automated machining systems. Government initiatives supporting domestic manufacturing and infrastructure development further accelerate growth. Rising investments in aerospace, renewable energy equipment, and industrial automation strengthen Asia Pacific’s leadership position in both volume-driven and precision machining applications.
Latin America
Latin America held a 7.4% market share in 2024 in the Machining Market, supported by growing automotive assembly, construction equipment manufacturing, and industrial expansion in Brazil and Mexico. Increasing foreign direct investment in manufacturing and rising demand for locally produced components drive machining adoption. The region shows gradual improvement in CNC penetration and automation, particularly among automotive suppliers and industrial equipment manufacturers. Infrastructure development projects and energy sector investments further support machining demand. While cost sensitivity remains, improving industrial capabilities and export-oriented manufacturing continue to strengthen the regional machining ecosystem.
Middle East & Africa
The Middle East & Africa accounted for 7.3% market share in 2024 in the Machining Market, driven by demand from energy, oil & gas, construction equipment, and industrial maintenance sectors. Investments in power generation, infrastructure development, and industrial diversification initiatives support machining activity across key economies. The region increasingly adopts precision machining for energy equipment, heavy-duty components, and industrial fabrication. Growth is further supported by rising localization of manufacturing, particularly in the Gulf countries. Although adoption of advanced automation remains gradual, steady industrial investment sustains regional machining demand.
Market Segmentations:
By Type
- Lathe Machines
- Laser Machines
- Winding Machines
- Welding Machines
- Others
By End-Use
- Automotive
- Aerospace & Defense
- Construction Equipment
- Power & Energy
- Industrial
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Competitive landscape analysis of the Machining Market features key players such as FANUC Corp., Okuma Corp., JTEKT Corp., IPG Photonics Corp., Jenoptik AG, Messer Cutting Systems Inc., and Jet Edge Inc.. The Machining Market remains moderately consolidated, with leading players focusing on advanced CNC systems, automation integration, laser-based machining, and multi-axis solutions to strengthen their market positions. Continuous investments in smart manufacturing, digital controls, and energy-efficient machines drive product differentiation. Companies emphasize expanding global footprints through capacity expansion, technology upgrades, and partnerships with industrial OEMs. Strong after-sales services, software-driven machining optimization, and customized solutions further enhance competitiveness. Increasing demand from automotive, aerospace, and industrial manufacturing encourages players to innovate in precision, productivity, and reliability, shaping sustained competition across developed and emerging manufacturing economies.
Key Player Analysis
- Okuma Corp.
- Matcor Matsu Group Inc.
- Jenoptik AG
- Otter Tail Corp.
- JTEKT Corp.
- Messer Cutting Systems Inc.
- Jet Edge Inc.
- Mayville Engineering Co. Inc.
- IPG Photonics Corp.
- FANUC Corp.
Recent Developments
- In July 2025, PMGC Holdings Inc. completed the acquisition of AGA Precision Systems LLC, a California-based CNC machining company specializing in high-tolerance milling and specialty metals for aerospace and defense markets.
- In September 2025, Machitech acquired Victory CNC Plasma Systems to enhance its U.S. manufacturing capacity for automated cutting equipment, strengthening support for fabricators amid reshoring trends.
- In November 2025, Compass Precision acquired Trutron Corporation, bolstering its precision machining capabilities for aerospace and defense components.
Report Coverage
The research report offers an in-depth analysis based on Type, End Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Machining Market will continue to benefit from rising demand for high-precision components across automotive, aerospace, and industrial manufacturing sectors.
- Increasing adoption of CNC, multi-axis, and automated machining systems will enhance productivity and operational efficiency.
- Integration of Industry 4.0 technologies will improve real-time monitoring, predictive maintenance, and process optimization in machining operations.
- Growing electric vehicle production will drive demand for advanced machining of powertrain, motor, and battery components.
- Expansion of aerospace and defense manufacturing will support sustained demand for complex and high-tolerance machined parts.
- Manufacturers will increasingly focus on energy-efficient and environmentally compliant machining solutions.
- Customization and small-batch production capabilities will gain importance due to shorter product life cycles.
- Investments in smart factories and digital manufacturing will reshape machining workflows and cost structures.
- Skilled workforce development and automation will remain critical to address labor shortages and technical complexity.
- Emerging economies will play a growing role in global machining capacity expansion and demand growth.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Machining Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Machining Market projected to grow between 2024 and 2032?
Which Machining Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Machining Market?
Who are the leading companies in the Machining Market?
Which region commanded the largest share of the Machining Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Machining Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Machining Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 402,553 million → 2032: USD 656,279.7 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Machining Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Machining Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Machining Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Machining Market Drivers
- 3.3 Machining Market Restraints & Challenges
- 3.4 Machining Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Machining Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Machining Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Machining category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Machining Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Machining Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Machining market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Machining Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Machining Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Machining Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Machining (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Machining Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Machining Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Machining Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Machining Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Machining Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Machining Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Machining Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Machining Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Machining Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
