
Market Overview
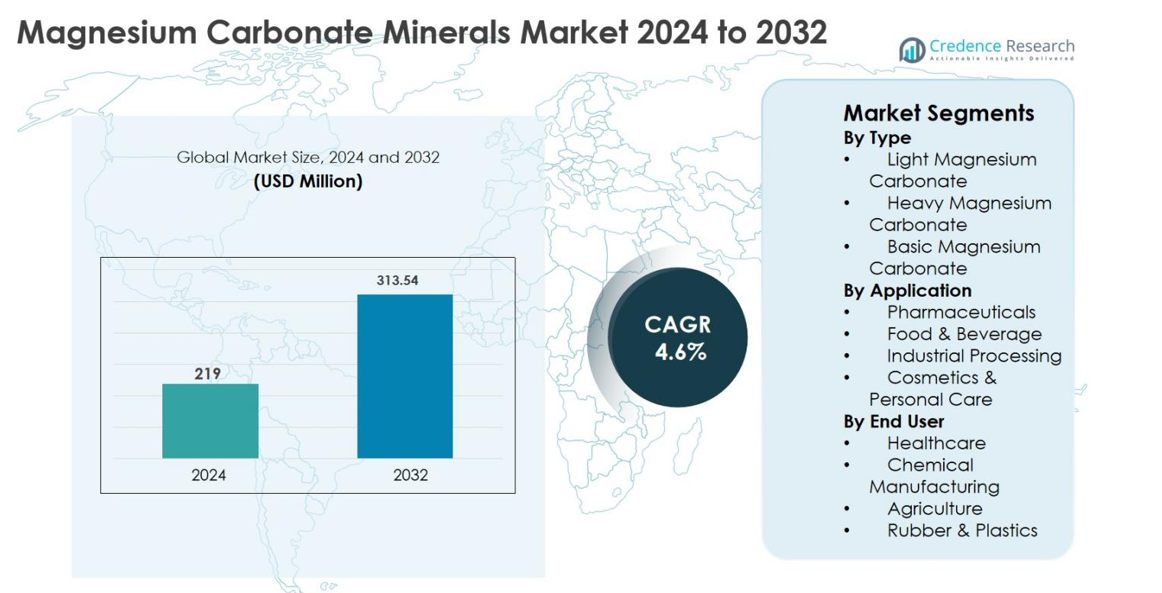
Magnesium Carbonate Minerals market size was valued at USD 219 million in 2024 and is anticipated to reach USD 313.54 million by 2032, growing at a CAGR of 4.6% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Magnesium Carbonate Minerals Market Size 2024 | USD 219 million |
| Magnesium Carbonate Minerals Market, CAGR | 4.6% |
| Magnesium Carbonate Minerals Market Size 2032 | USD 313.54 million |
Magnesium Carbonate Minerals market is led by a mix of global and regional manufacturers that focus on high-purity and application-specific grades to serve pharmaceutical, food, and industrial demand. Key players such as Grecian Magnesite, Kyowa Chemical Industry Co., Ltd., Dr. Paul Lohmann, Lehmann&Voss&Co. KG, Konoshima Chemical Co. Ltd., SCORA S.A.S, Buschle and Lepper, NUOVA SIMA, Yingkou Magnesite Chemical, and Persia Paya Madan strengthen market presence through quality differentiation, capacity optimization, and long-term supply partnerships. Asia-Pacific dominates the Magnesium Carbonate Minerals market with a 34.6% share, supported by abundant raw material availability and large-scale manufacturing in China, Japan, and India. Europe follows with 25.7% share, driven by pharmaceutical and specialty chemical production, while North America accounts for 28.4%, supported by strong healthcare and industrial consumption.
Market Insights
- Magnesium Carbonate Minerals market was valued at USD 219 million in 2024 and is projected to reach USD 313.54 million by 2032, growing at a CAGR of 4.6% during the forecast period, supported by steady demand from healthcare, food, and industrial applications.
- Growth is driven by rising pharmaceutical and nutraceutical consumption, where magnesium carbonate is widely used in antacids and excipients, along with expanding industrial processing demand for fillers and stabilizing agents in chemicals, rubber, and plastics.
- Market trends highlight increasing preference for high-purity and pharmaceutical-grade products, with Light Magnesium Carbonate holding 42.6% share by type and Pharmaceuticals accounting for 38.9% share by application due to regulatory compliance and formulation efficiency.
- Competitive dynamics reflect moderate consolidation, with players focusing on quality differentiation, customized grades, and long-term supply contracts, while cost-efficient Asian producers and premium European suppliers shape pricing and positioning.
- Regionally, Asia-Pacific leads with 34.6% share, followed by North America at 28.4% and Europe at 25.7%, while Healthcare remains the dominant end user with 41.3% share, supported by global healthcare expansion.
Market Segmentation Analysis:
By Type
The Magnesium Carbonate Minerals market by type is led by Light Magnesium Carbonate, which accounted for 42.6% market share in 2024 due to its high purity, low bulk density, and wide usability across pharmaceutical and food-grade applications. Light magnesium carbonate is preferred for tablet formulation, antacids, and food additives because of its superior absorbency and safety profile. Demand is further supported by rising pharmaceutical production and stringent quality standards. Heavy magnesium carbonate follows, driven by industrial uses, while basic magnesium carbonate serves niche applications in cosmetics and specialty chemicals.
- For instance, Scora S.A. supplies Light Magnesium Carbonate for antacid preparations and tablet production, leveraging its role as a diluent and stabilizer that enhances drug release in moisture-sensitive medications.
By Application
By application, Pharmaceuticals dominated the Magnesium Carbonate Minerals market with a 38.9% share in 2024, supported by strong demand for antacids, excipients, and laxative formulations. Magnesium carbonate is widely used as a buffering agent and stabilizer in drug manufacturing, ensuring formulation consistency and efficacy. Growth is driven by expanding global pharmaceutical manufacturing, rising digestive health awareness, and increasing OTC drug consumption. Food & beverage applications benefit from clean-label trends, while industrial processing and cosmetics show steady growth due to functional and absorbent properties.
- For instance, Bayer uses magnesium carbonate as an excipient and antacid component in certain digestive health and OTC products, consistent with pharmacopeial standards for magnesium compounds.
By End User
In terms of end users, the Healthcare segment held the largest share of 41.3% in 2024, driven by extensive use of magnesium carbonate in pharmaceutical formulations, nutraceuticals, and medical-grade compounds. Healthcare manufacturers favor magnesium carbonate for its chemical stability, non-toxicity, and regulatory acceptance. Rising healthcare spending, growing aging populations, and increased demand for digestive and mineral supplements support segment growth. Chemical manufacturing follows with strong industrial demand, while agriculture and rubber & plastics contribute through soil treatment and filler applications, respectively.
Key Growth Drivers
Rising Demand from Pharmaceutical and Healthcare Applications
The Magnesium Carbonate Minerals market benefits significantly from expanding pharmaceutical and healthcare demand, where magnesium carbonate is widely used as an active ingredient and excipient in antacids, laxatives, tablets, and nutraceutical formulations. Its buffering capacity, chemical stability, and non-toxic profile make it suitable for regulated medical applications. Growth in global pharmaceutical manufacturing, increased prevalence of gastrointestinal disorders, and rising consumption of over-the-counter digestive medications are accelerating demand. Aging populations and growing preventive healthcare awareness further support higher intake of mineral supplements. In addition, stricter quality standards in drug manufacturing are driving demand for high-purity light magnesium carbonate, reinforcing its importance across both prescription and consumer healthcare products.
- For instance, Merck KGaA (MilliporeSigma) offers high‑purity light magnesium carbonate grades specifically qualified as antacid, tablet excipient, and nutraceutical ingredient under pharmacopeial standards.
Expansion of Industrial Processing and Chemical Manufacturing
Industrial processing represents a strong growth driver for the Magnesium Carbonate Minerals market due to its extensive use as a filler, neutralizing agent, and flame retardant precursor. Chemical manufacturers utilize magnesium carbonate in ceramics, rubber, plastics, and insulation materials to improve thermal resistance and product stability. Rapid industrialization in emerging economies, along with rising infrastructure development, supports demand for construction materials incorporating magnesium compounds. Growth in specialty chemicals and functional additives further enhances consumption. Manufacturers increasingly favor magnesium carbonate for its cost-effectiveness and compatibility with diverse industrial formulations, ensuring sustained uptake across chemical processing and materials manufacturing industries.
- For instance, Lhoist supplies magnesium carbonate and related magnesium products for refractory, ceramics, and insulation applications, emphasizing improved heat resistance and performance in industrial materials
Growing Adoption in Food, Beverage, and Consumer Applications
The food and beverage sector is emerging as a notable growth driver, driven by magnesium carbonate’s use as an anti-caking agent, acidity regulator, and nutritional additive. Clean-label trends and rising consumer awareness of mineral fortification are encouraging food manufacturers to incorporate magnesium-based ingredients. Demand is supported by growth in dietary supplements, sports nutrition products, and fortified foods. Additionally, cosmetics and personal care manufacturers are increasing usage due to magnesium carbonate’s absorbent and texture-enhancing properties. Expanding consumer goods production and rising disposable incomes in developing regions further strengthen demand across food, beverage, and lifestyle applications.
Key Trends & Opportunities
Shift Toward High-Purity and Pharmaceutical-Grade Magnesium Carbonate
A major trend in the Magnesium Carbonate Minerals market is the increasing focus on high-purity and pharmaceutical-grade products. Regulatory compliance, especially in healthcare and food applications, is pushing manufacturers to invest in advanced processing and purification technologies. This shift creates opportunities for suppliers offering consistent quality, traceability, and customized grades. Pharmaceutical and nutraceutical companies prefer suppliers capable of meeting stringent pharmacopoeia standards, driving long-term supply agreements. As demand for OTC medications and supplements rises globally, producers that emphasize quality differentiation and regulatory alignment are well positioned to capture higher margins and strengthen market presence.
- For instance, Kyowa Chemical Industry supplies magnesium carbonate USP as an antacid, laxative, and excipient, emphasizing high quality and safety for pharmaceutical use.
Emerging Demand from Sustainable and Specialty Material Applications
Sustainability trends are opening new opportunities for magnesium carbonate in eco-friendly and specialty materials. Its role in flame-retardant formulations, carbon-neutral building materials, and environmentally safer fillers aligns with growing ESG and regulatory pressures. Research into magnesium-based alternatives for conventional additives is expanding its potential in green construction and energy-efficient insulation materials. These developments offer opportunities for innovation-driven manufacturers to enter high-value segments. Increasing investments in sustainable infrastructure and low-emission materials further support long-term growth opportunities for magnesium carbonate suppliers.
- For instance, Grecian Magnesite develops magnesium‑based products for construction and insulation, highlighting reduced environmental impact and improved fire resistance in comparison with conventional materials.
Key Challenges
Volatility in Raw Material Supply and Production Costs
The Magnesium Carbonate Minerals market faces challenges related to raw material availability and cost fluctuations, particularly linked to magnesite mining and energy-intensive processing. Variations in mining regulations, environmental restrictions, and geopolitical factors can disrupt supply chains and impact pricing stability. Rising energy and transportation costs further pressure production margins, especially for manufacturers operating in cost-sensitive markets. Smaller producers may struggle to absorb these cost increases, affecting competitiveness. Managing supply chain efficiency and securing long-term raw material sources remain critical challenges for market participants.
Regulatory and Environmental Compliance Pressures
Increasing regulatory scrutiny on mining activities and chemical processing poses a significant challenge for the Magnesium Carbonate Minerals market. Environmental regulations related to emissions, waste management, and land restoration increase operational complexity and compliance costs. Pharmaceutical and food-grade applications require adherence to strict safety and quality standards, raising barriers to entry for new players. Failure to meet evolving regulatory requirements can limit market access and slow product approvals. Companies must balance compliance investments with cost efficiency to maintain sustainable operations and market growth.
Regional Analysis
North America
North America accounted for 28.4% of the Magnesium Carbonate Minerals market in 2024, driven by strong demand from pharmaceutical, food, and specialty chemical industries. The region benefits from well-established healthcare infrastructure and high consumption of antacids, nutraceuticals, and OTC medications using magnesium carbonate. Stringent quality and safety regulations support the use of high-purity grades, particularly light magnesium carbonate. Industrial applications in rubber, plastics, and flame-retardant materials also contribute to steady demand. Ongoing investments in pharmaceutical manufacturing and growing health awareness continue to support stable market growth across the United States and Canada.
Europe
Europe held a 25.7% market share in 2024, supported by advanced pharmaceutical production, strong chemical manufacturing, and regulatory emphasis on product quality. Countries such as Germany, France, and Italy are key consumers due to their robust healthcare and specialty chemicals sectors. Magnesium carbonate is widely used in pharmaceuticals, cosmetics, and food processing across the region. Sustainability initiatives and demand for environmentally compliant materials further drive adoption in industrial and construction-related applications. Strict regulatory frameworks encourage the use of pharmaceutical-grade magnesium carbonate, supporting premium product demand and consistent consumption across Western and Central Europe.
Asia-Pacific
Asia-Pacific dominated the Magnesium Carbonate Minerals market with a 34.6% share in 2024, driven by large-scale production capacity, abundant raw material availability, and rapid industrial growth. China, Japan, and India are major contributors, supported by expanding pharmaceutical manufacturing, chemical processing, and food industries. Rising healthcare expenditure, growing population, and increasing consumption of OTC medicines accelerate demand. The region also benefits from cost-effective manufacturing and strong exports of magnesium carbonate products. Expanding cosmetics, agriculture, and rubber industries further strengthen regional demand, making Asia-Pacific the fastest-growing regional market.
Latin America
Latin America accounted for 6.2% of the Magnesium Carbonate Minerals market in 2024, supported by gradual growth in pharmaceutical, agriculture, and food processing sectors. Countries such as Brazil and Mexico lead regional consumption due to expanding healthcare access and increasing use of mineral supplements. Industrial applications in rubber and plastics contribute to steady demand, while agriculture benefits from magnesium-based soil treatment products. Improving manufacturing capabilities and rising consumer health awareness support market expansion. However, dependence on imports and price sensitivity moderate growth compared to developed regions.
Middle East & Africa
The Middle East & Africa region captured 5.1% of the market share in 2024, driven by growing pharmaceutical consumption and expanding chemical and construction industries. Rising healthcare investments, particularly in Gulf countries, support demand for magnesium carbonate in medical and nutraceutical applications. Industrial growth in insulation, ceramics, and specialty chemicals contributes to moderate consumption levels. Africa shows gradual adoption through agriculture and basic chemical processing. While market penetration remains limited, improving healthcare infrastructure and industrial diversification initiatives are expected to support long-term growth across the region.
Market Segmentations:
By Type
- Light Magnesium Carbonate
- Heavy Magnesium Carbonate
- Basic Magnesium Carbonate
By Application
- Pharmaceuticals
- Food & Beverage
- Industrial Processing
- Cosmetics & Personal Care
By End User
- Healthcare
- Chemical Manufacturing
- Agriculture
- Rubber & Plastics
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Magnesium Carbonate Minerals market features a moderately consolidated landscape, characterized by the presence of established global manufacturers and regionally strong producers competing on product purity, application specialization, and supply reliability. Key players such as Grecian Magnesite, Kyowa Chemical Industry Co., Ltd., Dr. Paul Lohmann, Lehmann&Voss&Co. KG, Konoshima Chemical Co. Ltd., SCORA S.A.S, Buschle and Lepper, NUOVA SIMA, Yingkou Magnesite Chemical, and Persia Paya Madan focus on serving pharmaceutical, food, and industrial-grade demand. Companies emphasize high-purity and customized grades to meet stringent regulatory requirements, particularly in healthcare and food applications. Strategic priorities include capacity expansion, process optimization, and long-term supply agreements with pharmaceutical and chemical manufacturers. Asia-based players benefit from cost-efficient production and raw material availability, while European firms leverage quality leadership and regulatory compliance, shaping competitive differentiation across regions.
Key Player Analysis
- NUOVA SIMA
- Kyowa Chemical Industry Co., Ltd.
- GRECIAN MAGNESITE
- Dr. Paul Lohmann
- Persia Paya Madan
- Konoshima Chemical Co. Ltd
- Buschle and Lepper
- Lehmann&Voss&Co. KG
- SCORA S.A.S
- Yingkou Magnesite Chemical
Recent Developments
- In October 2025, Canada Nickel Company Inc. and NetCarb advanced their strategic partnership to develop a zero-carbon industrial cluster in Northeastern Ontario that leverages carbon sequestration to produce by-products including magnesium-based products, supporting future magnesium mineral applications.
- In May 2025, MediSun Energy and EMSTEEL launched the UAE’s first pilot project to transform desalination brine into renewable blue energy and magnesium carbonate, marking a novel product pathway for sustainable magnesium carbonate generation
Report Coverage
The research report offers an in-depth analysis based on Type, Application, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Magnesium Carbonate Minerals market will witness steady demand growth driven by expanding pharmaceutical and nutraceutical production worldwide.
- Increasing use of high-purity and pharmaceutical-grade magnesium carbonate will shape product development strategies.
- Industrial processing applications will continue to support volume growth, particularly in chemicals, rubber, and plastics.
- Food and beverage manufacturers will adopt magnesium carbonate to meet clean-label and mineral fortification requirements.
- Asia-Pacific will remain the leading production and consumption hub due to raw material availability and cost-efficient manufacturing.
- Manufacturers will invest in process optimization and capacity expansion to improve quality consistency and supply reliability.
- Sustainability-focused applications such as flame retardants and eco-friendly building materials will create new growth avenues.
- Regulatory compliance will increasingly influence supplier selection, especially for healthcare and food-grade products.
- Strategic partnerships with pharmaceutical and specialty chemical companies will strengthen long-term market positioning.
- Technological advancements in purification and processing will enhance product performance and application versatility.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Magnesium Carbonate Minerals market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Magnesium Carbonate Minerals market projected to grow between 2024 and 2032?
What factors influence the pricing of magnesium carbonate minerals in the market?
How does the quality of magnesium carbonate minerals affect their market value?
What are the key geographical markets for magnesium carbonate minerals?
Who are the leading companies in the Magnesium Carbonate Minerals market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Magnesium Carbonate Minerals Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Magnesium Carbonate Minerals Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 219 million → 2032: USD 313.54 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Magnesium Carbonate Minerals Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Magnesium Carbonate Minerals Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Magnesium Carbonate Minerals Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Magnesium Carbonate Minerals Market Drivers
- 3.3 Magnesium Carbonate Minerals Market Restraints & Challenges
- 3.4 Magnesium Carbonate Minerals Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Magnesium Carbonate Minerals Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Magnesium Carbonate Minerals Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Magnesium Carbonate Minerals category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Magnesium Carbonate Minerals Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Magnesium Carbonate Minerals Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Magnesium Carbonate Minerals market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Magnesium Carbonate Minerals Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Magnesium Carbonate Minerals Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Magnesium Carbonate Minerals Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Magnesium Carbonate Minerals (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Magnesium Carbonate Minerals Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Magnesium Carbonate Minerals Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Magnesium Carbonate Minerals Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Magnesium Carbonate Minerals Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Magnesium Carbonate Minerals Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Magnesium Carbonate Minerals Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Magnesium Carbonate Minerals Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Magnesium Carbonate Minerals Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Magnesium Carbonate Minerals Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
