
Market Overview:
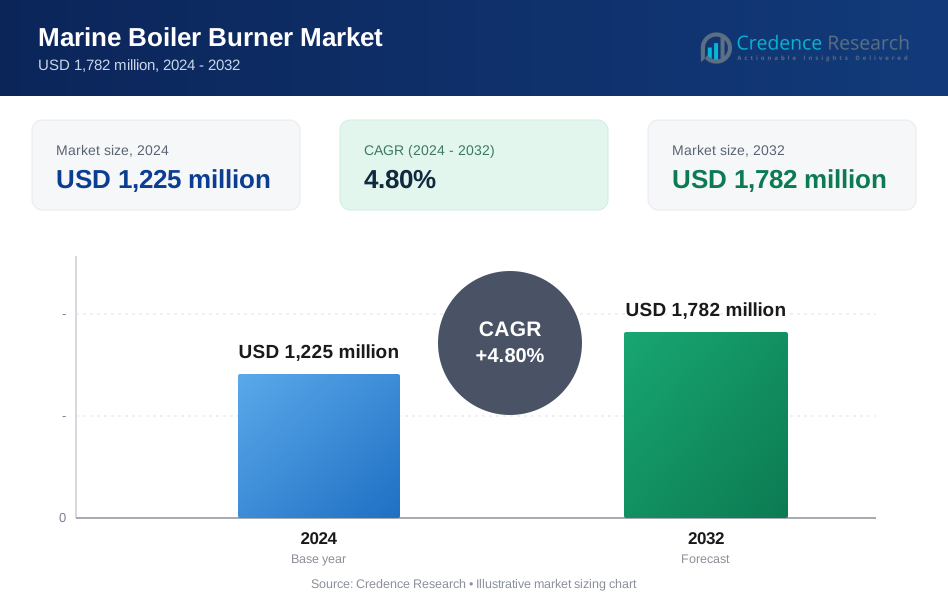
The Marine boiler burner market size was valued at USD 1225 million in 2024 and is anticipated to reach USD 1782 million by 2032, at a CAGR of 4.8 % during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Marine Boiler Burner Market Size 2024 | USD 1225 million |
| Marine Boiler Burner Market, CAGR | 4.8% |
| Marine Boiler Burner Market Size 2032 | USD 1782 million |
Key drivers propelling the Marine Boiler Burner Market include rising emphasis on maritime decarbonization and operational efficiency. The enforcement of emission norms by the International Maritime Organization (IMO), particularly MARPOL Annex VI, is pushing vessel owners to adopt low-emission combustion technologies. Demand for dual-fuel burners capable of switching between marine gas oil (MGO), heavy fuel oil (HFO), and liquefied natural gas (LNG) is increasing, especially in LNG carriers, offshore support vessels, and commercial cargo ships. Integration of automation and digital monitoring systems in boiler burners is also gaining momentum, helping optimize fuel consumption and reduce carbon footprint.
Regionally, Asia Pacific dominates the Marine Boiler Burner Market owing to the presence of major shipbuilding nations such as China, South Korea, and Japan. The region benefits from large-scale shipyard operations, a robust commercial fleet, and growing maritime trade volumes, with key players such as Weishaupt Group, SAACKE Group, Volcano Co., Ltd., Oilon Group Oy, and Burner Automation Rotterdam actively supporting demand through advanced burner technologies. Europe represents another significant market, driven by strict environmental regulations and strong retrofitting activity in countries like Germany, Norway, and the Netherlands. North America is witnessing steady growth due to offshore exploration projects and increased LNG transportation. The Middle East and Africa are also gaining momentum with infrastructure expansion and modernization of regional fleets, creating new opportunities for boiler burner deployment.
Market Insights:
- The Marine Boiler Burner Market was valued at USD 1,225 million in 2024 and is projected to reach USD 1,782 million by 2032, growing at a CAGR of 4.8%.
- Emission regulations from IMO, including MARPOL Annex VI, are compelling vessel owners to adopt low-NOx and low-sulfur boiler burner systems.
- Dual-fuel burners are gaining traction due to rising LNG adoption and the need for flexible fuel-switching across long-haul vessels.
- Automation and digital controls are being integrated into burner systems to optimize fuel use, reduce emissions, and support remote diagnostics.
- High capital costs and retrofit complexity are limiting adoption across older fleets and small-scale operators in developing markets.
- Asia Pacific leads with 45% market share, supported by dominant shipbuilding hubs and strong demand from China, South Korea, and Japan.
- Europe and North America hold 26% and 17% shares respectively, driven by retrofitting activity, LNG investments, and regulatory compliance efforts.
Market Drivers:
Stringent Maritime Emission Regulations Are Forcing Technological Upgrades in Boiler Burner Systems:
The Marine boiler burner market is experiencing significant momentum due to strict global emissions mandates led by the International Maritime Organization (IMO). IMO 2020 regulations have drastically reduced permissible sulfur content in marine fuels, prompting ship operators to upgrade or retrofit boiler burners with low-NOx and low-sulfur fuel capabilities. Compliance requirements are encouraging the adoption of dual-fuel and LNG-compatible burners across various vessel types. Burner manufacturers are also integrating emission monitoring and control technologies to support regulatory adherence. These regulatory shifts are reshaping procurement decisions and influencing burner design priorities. The regulatory pressure is a strong catalyst driving innovation and long-term demand in the market.
- For instance, Alfa Laval Aalborg KBO-A dual-fuel burner is compatible with Aalborg OS and OC boilers with a steam capacity range from 1.6 to 6.5 tons per hour, enabling a broad array of vessels to switch to low-sulfur and LNG fuels efficiently and meet IMO 2020 requirements.
Rising Demand for Dual-Fuel Burners Is Supporting Energy Transition in Marine Operations:
Fuel flexibility is becoming a top operational priority for commercial and naval fleets navigating fluctuating fuel availability and pricing. The Marine boiler burner market is benefiting from rising installations of dual-fuel systems that allow seamless switching between HFO, MGO, and LNG. Dual-fuel technology enhances energy security and reduces environmental risk, which appeals to operators managing long-haul and cross-border routes. LNG-capable burners are gaining traction in newbuilds and retrofit projects, especially in container ships and LNG carriers. This trend supports decarbonization strategies and aligns with evolving fuel infrastructure across global ports. Burner systems that accommodate alternative fuels are becoming critical assets in vessel lifecycle planning.
- Notably, Maersk placed orders for 16 dual-fuel methanol-powered container vessels with Hyundai Heavy Industries, demonstrating strong commercial fleet uptake of low-carbon, flexible-fuel technologies.
Growing Focus on Operational Efficiency Is Accelerating Demand for Automation in Burner Systems:
Shipowners are investing in automated boiler burner systems to improve combustion efficiency, reduce fuel consumption, and minimize maintenance costs. The Marine boiler burner market is seeing increased demand for smart control systems that optimize burner performance through real-time monitoring and feedback mechanisms. Integrated diagnostics and predictive maintenance features are helping prevent unplanned downtimes. These digital upgrades are especially valuable in remote offshore operations and long-duration voyages. Improved thermal efficiency from automated burners contributes to both environmental compliance and operational savings. Smart burner systems are shaping the next phase of marine engineering design.
Expansion in Global Maritime Trade and Fleet Modernization Is Stimulating Burner Installations:
Rising international shipping volumes and fleet expansion activities are increasing the demand for reliable marine boiler burner systems. The Marine boiler burner market is responding to the needs of a growing number of vessels in commercial, cruise, and offshore sectors. New shipbuilding orders across Asia, Europe, and the Middle East are incorporating advanced burner technologies for greater fuel economy and regulatory compliance. Retrofitting older fleets with modern boiler burners is also gaining importance to extend vessel life and enhance operational capabilities. Burner manufacturers are forming partnerships with shipyards to integrate efficient systems at the design stage. This alignment with ship construction and modernization cycles is reinforcing sustained market growth.
Market Trends:
Integration of Smart Technologies and Automation Is Transforming Burner Operations:
The Marine boiler burner market is undergoing a shift toward intelligent systems equipped with automation and advanced control technologies. Smart burners featuring real-time diagnostics, remote access, and predictive maintenance capabilities are becoming standard in new vessel builds and retrofits. These systems optimize combustion efficiency, reduce human error, and minimize fuel waste, aligning with cost-saving and emission-reduction goals. The use of sensors and digital interfaces allows continuous monitoring of burner performance, enabling operators to detect anomalies early and schedule maintenance proactively. Integration with vessel management systems supports centralized control and improves onboard operational transparency. These trends are redefining performance benchmarks across both commercial and naval fleets.
- For instance, Zeeco’s GBM-D LNG Marine Burner provides up to a 10:1 turndown ratio and is equipped with dual ProFlame™ self-checking flame scanners and a diesel oil pilot, contributing to improved safety and operational flexibility across boilers sized from 5T/h and upwards.
Adoption of LNG and Biofuel-Compatible Burners Is Expanding Across Vessel Classes:
Decarbonization goals are pushing the marine industry to diversify its fuel mix, leading to increased adoption of LNG and biofuel-ready boiler burner systems. The Marine boiler burner market is seeing higher demand for equipment capable of handling multiple fuel types, including synthetic and renewable options. Dual-fuel and low-NOx burners are gaining popularity among operators seeking compliance without sacrificing reliability or thermal output. LNG-fueled vessels, especially in the cruise and cargo segments, are fueling this transition with a focus on cleaner combustion and reduced greenhouse gas emissions. Burner designs are evolving to support low-carbon operations without compromising on safety or performance. This shift is encouraging manufacturers to prioritize innovation in burner flexibility and fuel compatibility.
- For instance, as of December 2024, Wärtsilä had delivered over 2,400 LNG-capable vessels globally, with an additional 1,000 vessels on order; this demonstrates extensive operational deployment of multi-fuel burner systems in the marine sector.
Market Challenges Analysis:
High Initial Investment and Integration Costs Are Slowing Adoption Across Smaller Fleets:
The Marine boiler burner market faces resistance from smaller shipping operators due to the high upfront cost of advanced burner systems. Smart burners, dual-fuel units, and emission-compliant technologies require significant capital investment and specialized integration. Many operators hesitate to upgrade older vessels because of limited budgets and uncertain returns on investment. Retrofitting challenges such as spatial constraints, compatibility issues, and downtime costs further delay adoption. It creates a barrier for market penetration in developing maritime regions and among aging fleets. Cost-sensitive operators often opt for basic solutions that meet minimum regulatory standards but lack long-term efficiency.
Fuel Supply Volatility and Regulatory Uncertainty Are Complicating Technology Planning:
Unstable fuel pricing and evolving international regulations pose strategic challenges for burner system investments. The Marine boiler burner market must address operator concerns regarding long-term fuel availability and compliance risks. Shifting preferences toward LNG, biofuels, and future synthetic fuels create uncertainty in burner design and procurement decisions. Shipowners struggle to select systems that remain compliant across multiple fuel scenarios and jurisdictions. Delays in global port infrastructure upgrades further reduce the appeal of fuel-flexible technologies. It restricts the pace of innovation deployment and increases the complexity of fleet-wide technology planning.
Market Opportunities:
Growth in LNG-Fueled Vessel Construction Offers Strong Demand for Dual-Fuel Burners:
The global shift toward LNG as a marine fuel presents a significant opportunity for dual-fuel boiler burner manufacturers. Shipbuilders and fleet operators are actively investing in LNG-capable vessels to meet emission mandates and reduce fuel costs. The Marine boiler burner market can capitalize on this transition by offering systems that support both traditional and alternative fuels. LNG infrastructure expansion at major ports supports adoption and opens long-term retrofit possibilities. OEMs that develop compact, efficient, and low-emission burners for LNG applications can strengthen their position in high-growth segments like LNG carriers and container ships. It creates a path for scalable innovation across multiple vessel classes.
Retrofitting Aging Fleets with Emission-Compliant Burners Presents a Major Revenue Stream:
Fleet modernization initiatives are accelerating across regions with older commercial and offshore vessels. Many shipowners seek to extend vessel life while complying with tightening IMO and regional emissions rules. The Marine boiler burner market has the opportunity to provide retrofitting solutions that upgrade combustion efficiency without requiring full boiler replacement. Customized burner kits, automation add-ons, and low-NOx modules can attract clients aiming to balance cost with compliance. Emerging markets with limited access to new builds are likely to invest in high-performance retrofits. It enables manufacturers to diversify their offerings and increase aftersales service revenue.
Market Segmentation Analysis:
By Product Type:
The Marine boiler burner market includes pressure burners, rotary cup burners, and register burners. Pressure burners dominate due to their compact design, ease of maintenance, and suitability for medium to large vessels. Register burners are gaining popularity for large-capacity marine boilers where precise air-fuel mixing is critical. Rotary cup burners offer stable combustion with heavy fuel oils, making them preferred for auxiliary boilers on commercial ships. Each type serves distinct performance and installation needs across vessel classes.
- For instance, Superior Boiler supplied for 1,500-horsepower Mohican fire tube boilers to a major industrial facility, demonstrating reliable, high-capacity performance that meets the demands of large-scale marine applications.
By Fuel Type:
The market segments by fuel type into diesel, heavy fuel oil (HFO), and dual-fuel options. Diesel-based burners remain widely used for their clean combustion and compatibility with emission norms. HFO burners maintain relevance in large commercial vessels but face regulatory pressure. Dual-fuel burners are gaining traction due to rising LNG adoption and the need for fuel flexibility. It reflects a broader industry shift toward cleaner propulsion alternatives and long-term compliance strategies.
By Capacity:
Burners are classified into less than 1 MW, 1–10 MW, and above 10 MW. The 1–10 MW segment leads the market, driven by widespread deployment in mid-sized cargo, tanker, and support vessels. Burners above 10 MW are used in large marine boilers for long-haul applications and offshore platforms. Systems below 1 MW cater to smaller vessels and onboard auxiliary functions. It enables targeted solutions based on vessel size, operational load, and energy efficiency requirements.
- For instance, Weishaupt’s 3 MW marine burner is installed on container ships, providing robust residual oil combustion for thermal fluid heaters and auxiliary systems.
Segmentations:
By Product Type:
- Pressure Burners
- Rotary Cup Burners
- Register Burners
By Fuel Type:
- Diesel
- Heavy Fuel Oil (HFO)
- Dual-Fuel
By Capacity:
- Less than 1 MW
- 1–10 MW
- Above 10 MW
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
Asia Pacific:
The Asia Pacific region holds the largest share in the Marine boiler burner market due to its strong shipbuilding infrastructure in China, South Korea, and Japan. It accounts for 45% of the global market, supported by extensive commercial fleet deployment and high retrofit demand. Major shipyards across the region prioritize the integration of advanced boiler burners in newbuilds to meet evolving emission norms. The region also benefits from rising LNG vessel production, driving demand for dual-fuel and low-NOx burner systems. Regulatory frameworks in Japan and South Korea are encouraging low-emission marine technologies, strengthening regional growth. It creates sustained opportunities for burner manufacturers partnering with OEMs and maritime engineering firms.
Europe :
Europe commands 26% of the Marine boiler burner market, driven by early adoption of green maritime technologies and strong environmental legislation. Countries such as Germany, Norway, and the Netherlands are investing in cleaner marine propulsion systems, prompting demand for emission-compliant burners. Retrofitting activity is high, with aging fleets upgrading systems to meet IMO Tier III and EU maritime standards. LNG-fueled ships in Northern Europe further support the market for dual-fuel burner installations. Ports across the region offer LNG bunkering facilities, enabling broader fuel transition strategies. It reinforces the role of Europe as a mature and regulation-driven market for burner technology.
North America:
North America holds 17% of the global market, with growth driven by offshore energy operations, naval procurement, and commercial shipping modernization. The United States is investing in LNG-ready and hybrid vessels, increasing demand for advanced boiler burner systems. The market is supported by retrofitting projects across cruise lines and supply vessels operating in emission control areas (ECAs). Technological adoption is gaining traction, with a focus on automation and digital combustion controls. LNG bunkering infrastructure is expanding along the Gulf and East Coasts, improving the feasibility of dual-fuel systems. It positions North America as a key market for specialized and fuel-flexible burner technologies.
Key Player Analysis:
- Weishaupt Group
- SAACKE Group
- Volcano Co., Ltd.
- Oilon Group Oy
- Burner Automation Rotterdam
- Filter AS
- Zeeco, Inc.
- Forespar
- Ocean Signal
- Osculati
Competitive Analysis:
The Marine boiler burner market features a competitive landscape led by a mix of established global manufacturers and specialized engineering firms. Key players include Weishaupt Group, SAACKE Group, Volcano Co., Ltd., Oilon Group Oy, and Burner Automation Rotterdam. It is shaped by innovation in emission control, fuel flexibility, and automation. Companies are focusing on dual-fuel technologies and smart burner systems to meet stringent IMO regulations and evolving fuel standards. Strategic collaborations with shipyards and fleet operators help secure long-term supply and retrofit contracts. Players also invest in expanding service networks and providing lifecycle support to strengthen customer retention. The market rewards technological expertise, compliance readiness, and reliable aftersales performance, making continuous R&D a central part of competitive positioning.
Recent Developments:
- In January 2025, Weishaupt Group announced a partnership with Superior Boiler to launch the Cheyenne and ULN burner package, designed to deliver sub-7 ppm NOx emissions in industrial heating applications.
- In December 2024, Zeeco, Inc. and ClearSign Technologies Corporation announced the launch of a co-branded process burner line capable of firing 100% natural gas and 100% hydrogen with ultra-low NOx emissions.
Market Concentration & Characteristics:
The Marine boiler burner market exhibits moderate concentration, with a mix of established global players and regional specialists competing across OEM and aftermarket segments. Key manufacturers focus on dual-fuel technology, automation integration, and low-emission performance to meet evolving regulatory and operational demands. It remains highly technical and compliance-driven, with customer preference leaning toward customized, fuel-flexible systems. Competitive dynamics are shaped by long-term partnerships with shipbuilders, fleet operators, and maritime engineering firms. Entry barriers are high due to complex design requirements, safety certifications, and marine regulatory standards. The market emphasizes reliability, thermal efficiency, and lifecycle service support, which influence procurement decisions across vessel types.
Report Coverage:
The research report offers an in-depth analysis based on Product, Fuel, Capacity and Region. It details leading Market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current Market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven Market expansion in recent years. The report also explores Market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on Market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the Market.
Future Outlook:
- The Marine boiler burner market will continue adopting dual-fuel systems to support LNG and alternative fuel integration.
- It will advance digital control platforms to enhance performance monitoring and predictive maintenance.
- Operators will prioritize low-NOx and low-sulfur burner models to comply with tightening marine emission standards.
- Manufacturers will develop modular burner units enabling efficient retrofits in older vessels.
- The industry will invest in sensor-based combustion optimization to reduce fuel consumption and carbon output.
- It will foster stronger collaborations with shipyards to integrate burners at design stage of new builds.
- Suppliers will expand service networks and lifecycle support offerings to improve operational uptime.
- The Marine boiler burner market will move toward standardized platforms for easier customization across vessel types.
- It will explore hydrogen and biofuel readiness to align with future zero-emission targets.
- The sector will strengthen data-driven decision tools, giving operators insight into fuel and maintenance costs.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Marine Boiler Burner Market?
What are the key segments within the Marine Boiler Burner Market?
What are some challenges faced by the Marine Boiler Burner Market?
Who are the major players in the Marine Boiler Burner Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Marine Boiler Burner Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Marine Boiler Burner Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1,225 million → 2032: USD 1,782 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Marine Boiler Burner Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Marine Boiler Burner Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Marine Boiler Burner Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Marine Boiler Burner Market Drivers
- 3.3 Marine Boiler Burner Market Restraints & Challenges
- 3.4 Marine Boiler Burner Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Marine Boiler Burner Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Marine Boiler Burner Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Marine Boiler Burner category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Marine Boiler Burner Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Marine Boiler Burner Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Marine Boiler Burner market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Marine Boiler Burner Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Marine Boiler Burner Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Marine Boiler Burner Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Marine Boiler Burner (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Marine Boiler Burner Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Marine Boiler Burner Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Marine Boiler Burner Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Marine Boiler Burner Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Marine Boiler Burner Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Marine Boiler Burner Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Marine Boiler Burner Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Marine Boiler Burner Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Marine Boiler Burner Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
