
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Bio Marine Ingredients Market Size 2024 | USD 2,500 million |
| Bio Marine Ingredients Market, CAGR | 5.7% |
| Bio Marine Ingredients Market Size 2032 | USD 3,895.2 million |
Market Overview
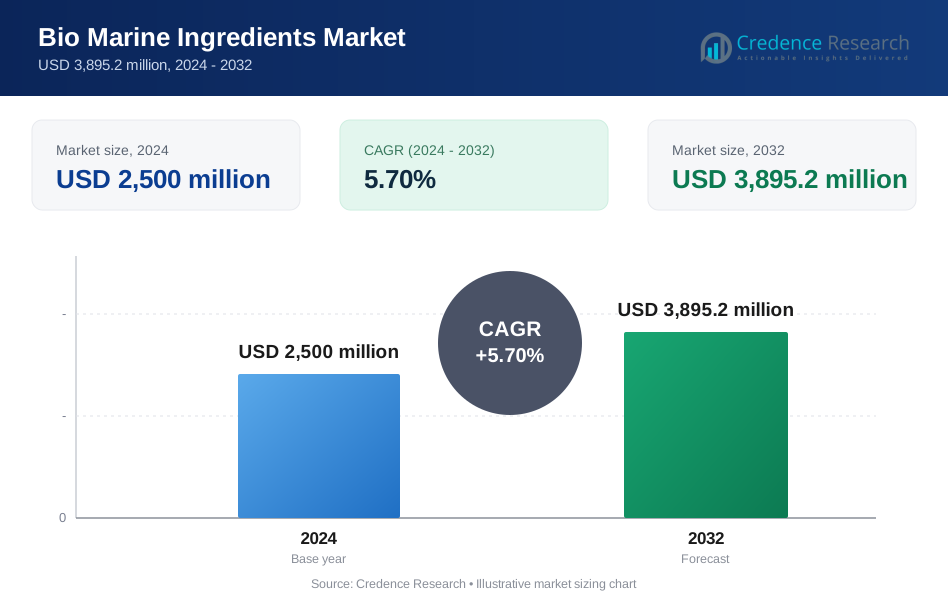
The bio marine ingredients market is projected to grow from USD 2,500 million in 2024 to USD 3,895.2 million by 2032, registering a compound annual growth rate (CAGR) of 5.7% during the forecast period.
The bio marine ingredients market is driven by the rising demand for natural and sustainable ingredients across the food, nutraceutical, cosmetic, and pharmaceutical industries. Growing awareness about the health benefits of marine-derived proteins, peptides, omega-3 fatty acids, and collagen is fueling product adoption, especially in functional foods and dietary supplements. Regulatory support for sustainable marine harvesting and advancements in biotechnological extraction processes are further encouraging market growth. At the same time, trends such as clean-label formulations, increasing use of fish by-products to reduce waste, and innovation in algae-based ingredients are shaping the market landscape. The shift toward eco-conscious consumer preferences is accelerating the development of marine-based alternatives to synthetic ingredients. Moreover, partnerships between biotech companies and seafood processing firms are strengthening supply chains and promoting the circular economy. With increasing research and development investments and expansion into emerging markets, the bio marine ingredients market is poised for steady growth over the coming years.
The Bio marine ingredients market demonstrates strong geographical diversity, with North America leading at 34% market share due to advanced R&D and high demand for nutraceuticals and cosmetics. Europe follows with 28%, supported by a mature marine biotech sector and sustainability-focused consumers. Asia-Pacific holds 24% and represents the fastest-growing region, driven by health-conscious populations and expanding marine resources in China, Japan, and India. The Rest of the World accounts for 14%, with emerging opportunities in Latin America, the Middle East, and Africa. Key players in the market include Aker Bio Marine AS, Cargill Incorporated, Rousselot S.A.S., Marinova Pty Ltd, CP Kelco, Algenuity, Arctic Bioscience, Calysta, Seagarden AS, and Bio Marine Ingredients Ireland. These companies compete through innovation, sustainability, and regional expansion to meet the rising global demand for functional and clean-label marine-derived ingredients.
Market Insights
- The bio marine ingredients market is projected to grow from USD 2,500 million in 2024 to USD 3,895.2 million by 2032, registering a CAGR of 5.7%.
- Rising consumer demand for sustainable and natural ingredients is driving the adoption of marine-derived proteins, peptides, omega-3s, and collagen across multiple industries.
- Regulatory support for sustainable marine harvesting and clean-label trends are pushing companies to innovate and reduce reliance on synthetic alternatives.
- Technological advancements such as enzymatic hydrolysis and membrane filtration are improving product quality, efficiency, and scalability in ingredient extraction.
- North America leads the market with 34% share, followed by Europe (28%), Asia-Pacific (24%), and Rest of the World (14%) with growing contributions.
- Key players include Aker Bio Marine AS, Cargill Incorporated, Rousselot S.A.S., Marinova Pty Ltd, CP Kelco, Algenuity, Arctic Bioscience, and others.
- Challenges include limited marine biomass availability, high production costs, and technical complexities in scaling and formulating high-performance bioactives.
Market Drivers
Rising Demand for Natural and Sustainable Ingredients
Consumers are shifting toward natural, eco-friendly products, pushing industries to replace synthetic components with sustainable alternatives. The Bio marine ingredients market is benefiting from this trend, with marine-derived compounds such as collagen, omega-3s, and proteins gaining traction in nutraceuticals, personal care, and functional foods. It supports clean-label product development and aligns with sustainability goals. Regulatory backing for sustainable marine sourcing is reinforcing this shift across key global markets.
- For instance, Skretting sourced 39% of its marine ingredients from by-products in 2022, supporting circularity and sustainable feed production.
Expanding Applications Across End-Use Industries
The use of bio marine ingredients has expanded from traditional food and supplements to cosmetics, pharmaceuticals, and pet nutrition. Marine collagen, peptides, and oils are widely applied for their bioactivity, enhancing skin health, joint support, and cardiovascular function. The Bio marine ingredients market benefits from cross-industry adoption driven by scientific validation and consumer awareness. Demand for anti-aging products and functional foods is reinforcing the relevance of marine ingredients in product innovation.
- For instance, Hill’s Pet Nutrition incorporates marine-sourced ingredients in its Science Diet line, with documented evidence of enhanced skin and coat health in pets, as supported by veterinary studies.
Technological Advancements in Extraction and Processing
Innovations in extraction and processing technologies have significantly improved yield, purity, and functionality of marine bioactives. Enzymatic hydrolysis, membrane filtration, and supercritical fluid extraction allow for high-quality ingredient production with minimal waste. The Bio marine ingredients market is responding with new product launches that meet stringent quality and safety standards. It enables manufacturers to develop tailored formulations, enhancing application in targeted health and cosmetic solutions.
Circular Economy and Waste Valorization Efforts
Global efforts to reduce seafood waste have led to increased utilization of fish by-products and algae in ingredient production. Companies are investing in circular economy models that convert low-value biomass into high-value functional compounds. The Bio marine ingredients market is directly linked to this shift, making it a key player in sustainable resource management. It addresses both environmental concerns and raw material cost optimization for manufacturers.
Market Trends
Growth of Algae-Based Ingredient Innovation
Algae is emerging as a versatile raw material in marine-based ingredient development due to its rich nutrient profile and minimal environmental footprint. Manufacturers are increasingly exploring algae-derived omega-3s, proteins, and pigments for food, beverage, and cosmetic applications. The Bio marine ingredients market is witnessing strong investment in microalgae cultivation technologies that improve biomass yields and processing efficiency. It reflects a broader industry push for plant-based marine alternatives with reduced ecological impact and scalable production.
- For instance, Corbion produces AlgaPrime™ DHA, a high-quality, vegetarian omega-3 ingredient derived from microalgae via industrial-scale fermentation. This product delivers sustainable DHA for animal feed and human nutrition, reducing reliance on fish oil and supporting environmental conservation.
Increased Focus on Functional and Fortified Foods
The rising consumer preference for health-enhancing and functional products is driving demand for marine-sourced bioactives such as collagen, peptides, and polyunsaturated fatty acids. These ingredients are being used to fortify a wide range of foods and beverages, targeting immunity, cognitive health, and joint support. The Bio marine ingredients market is closely tied to this shift in dietary habits. It enables brands to differentiate through nutritional claims and scientific backing, enhancing product credibility.
Clean Label and Traceability Expectations
Consumers and regulatory bodies are placing greater emphasis on clean-label products with transparent sourcing and processing methods. This trend is encouraging the development of minimally processed marine ingredients with no artificial additives. The Bio marine ingredients market is evolving to meet these expectations by promoting traceable supply chains and certified sustainable harvesting practices. It strengthens consumer trust and positions marine-based ingredients as ethical and safe choices in global markets.
- For instance, Chicago Bar Company launched protein bars with simple, transparent ingredients, boosting consumer trust and leading to a $600 million acquisition.
R&D Investments Driving Ingredient Customization
Ongoing research in marine biotechnology is enabling the customization of bioactive profiles to suit specific applications in cosmetics, pharmaceuticals, and wellness products. Companies are targeting functional benefits such as anti-inflammatory effects, improved skin elasticity, and cardiovascular support through tailored marine extracts. The Bio marine ingredients market is advancing with this focus on precision formulations. It allows producers to meet evolving consumer needs while improving the efficacy and market value of their offerings.
Market Challenges Analysis
Limited Raw Material Availability and Environmental Concerns
The availability of marine biomass remains a key constraint due to seasonal variability, overfishing risks, and strict environmental regulations. Sourcing high-quality raw materials from sustainable marine ecosystems demands careful management and often leads to higher input costs. The Bio marine ingredients market faces challenges in maintaining a stable and traceable supply chain. It must balance growing demand with conservation efforts, which can limit scalability and disrupt production cycles in sensitive marine zones.
High Production Costs and Technical Barriers
Extracting and processing marine ingredients require advanced technologies, which involve significant capital investment and operational expertise. These processes must ensure the preservation of bioactivity and meet regulatory compliance, contributing to elevated production costs. The Bio marine ingredients market encounters obstacles in achieving cost-efficiency while scaling innovations. It also faces technical barriers in formulating stable, effective products for diverse end-use applications. Market entry for new players remains limited due to complex extraction standards and patent-heavy competition.
Market Opportunities
Expansion into Personalized Nutrition and Wellness
The rising demand for targeted health solutions creates significant growth potential for marine-derived bioactives tailored to individual needs. Companies are leveraging advancements in nutrigenomics and consumer health data to develop customized supplements featuring marine collagen, peptides, and omega-3 fatty acids. The Bio marine ingredients market can capitalize on this trend by offering products that align with age, lifestyle, or specific health goals. It supports innovation in functional food and supplement formulations with enhanced consumer relevance.
Emerging Markets and Sustainable Product Demand
Growing middle-class populations and health awareness in Asia-Pacific, Latin America, and the Middle East present new demand centers for marine-based ingredients. Consumers in these regions are increasingly seeking clean-label and sustainably sourced products across personal care, food, and pharmaceuticals. The Bio marine ingredients market has strong opportunity to expand its footprint through localized production and partnerships. It can serve regional needs while supporting global sustainability goals and regulatory compliance in newer markets.
Market Segmentation Analysis:
By Type
The Bio marine ingredients market includes a broad range of ingredient types, with proteins, peptides, and omega-3 fatty acids leading in demand due to their high nutritional and functional value. Collagen is gaining significant traction in beauty and joint health products, while chitosan and polysaccharides are valued for their bioactivity in medical and agricultural applications. Peptides offer antioxidant and anti-inflammatory properties, enhancing their role in both cosmetics and nutraceuticals. Each type addresses distinct consumer and industrial needs.
- For instance, chitosan-based wound dressings from companies like Hemcon Medical Technologies utilize shellfish-derived chitosan for its documented wound-healing and antimicrobial properties.
By Source
Sources such as fish, algae, and crustaceans dominate ingredient extraction in the bio marine industry. Fish remains the most widely used due to its rich protein and oil content. Algae and seaweeds are gaining momentum for their sustainable production and diverse bioactive compounds. The Bio marine ingredients market also includes inputs from mollusks and microorganisms, expanding possibilities in biotechnology. It supports diversification in sourcing strategies to meet sustainability and efficiency targets.
By Application
Food and beverages represent a major application area, driven by functional product development and health-conscious consumer behavior. Pharmaceuticals use marine ingredients for their bioavailability and targeted therapeutic properties, while cosmetics focus on anti-aging and skin-repair benefits. The Bio marine ingredients market also finds application in agriculture, where bioactive compounds promote plant health and soil enrichment. It continues to evolve with increasing cross-industry collaboration and customized product innovations.
- For instance, in pharmaceuticals, companies like BASF have utilized marine collagen for its high bioavailability in targeted therapies, with clinical studies supporting its use in wound healing and tissue regeneration.
Segments:
Based on Type
- Protein
- Peptides
- Collagen
- Chitosan
- Omega-3 Fatty Acids
- Polysaccharides
- Others
Based on Source
- Fish
- Algae
- Crustaceans
- Mollusks
- Microorganisms
- Seaweeds
- Others
Based on Application
- Food and Beverages
- Pharmaceuticals
- Cosmetics and Personal Care
- Agriculture
- Others
Based on the Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds the largest share of the Bio marine ingredients market, accounting for 34% of global revenue. Strong demand for functional foods, dietary supplements, and clean-label beauty products drives regional growth. The presence of established nutraceutical and cosmetics industries encourages continued product development using marine-derived bioactives. Regulatory frameworks support sustainable marine harvesting and traceability, further strengthening market expansion. Companies invest heavily in R&D and partnerships with local fisheries to ensure quality sourcing. It remains a key innovation hub for premium-grade marine ingredients.
Europe
Europe captures 28% of the Bio marine ingredients market, driven by high consumer awareness around sustainability and product traceability. The region benefits from a mature marine biotechnology sector and stringent environmental regulations that promote ethical ingredient sourcing. Demand for marine collagen, omega-3 supplements, and algae-based extracts is increasing across both personal care and pharmaceutical applications. Countries like Norway, France, and Iceland lead in marine ingredient processing. It supports eco-conscious product lines and integrates marine extracts into various functional formulations.
Asia-Pacific
Asia-Pacific accounts for 24% of the Bio marine ingredients market and shows the fastest growth rate among all regions. Rising health awareness, a growing middle class, and expanding marine resources contribute to strong regional demand. Countries such as China, Japan, South Korea, and India are investing in algae cultivation and fish-based extraction technologies. It enables cost-effective ingredient production for use in supplements, skincare, and fortified foods. Local manufacturers collaborate with global firms to scale up operations and meet rising consumption.
Rest of the World
The Rest of the World holds 14% of the Bio marine ingredients market, with growing activity in Latin America, the Middle East, and Africa. These regions offer untapped marine resources and emerging demand for functional and natural products. Governments and industry players are exploring opportunities in algae farming and fishery by-product utilization. It encourages infrastructure development and localized production strategies. The market is gradually gaining pace through international partnerships and regulatory improvements.
Key Player Analysis
- CP Kelco
- Marinova Pty Ltd
- Cargill Incorporated
- Algenuity
- Rousselot S.A.S.
- Seagarden AS
- Arctic Bioscience
- Calysta
- Bio Marine Ingredients Ireland
- Aker Bio Marine AS
Competitive Analysis
The Bio marine ingredients market is highly competitive, with both global corporations and specialized biotech firms actively expanding their product portfolios. Leading players such as Aker Bio Marine AS, Cargill Incorporated, and Rousselot S.A.S. invest in advanced extraction technologies, sustainable sourcing practices, and product innovation to maintain market leadership. Companies like Algenuity, Marinova Pty Ltd, and Arctic Bioscience focus on niche segments such as algae-based ingredients and high-purity bioactives. Strategic partnerships, acquisitions, and regional expansion help firms access new markets and secure supply chains. It continues to attract R&D investments aimed at developing customized solutions for functional foods, personal care, and pharmaceuticals. Smaller players emphasize traceability, clean-label offerings, and environmental compliance to differentiate in a crowded landscape. Competitive intensity is rising with increasing demand for high-performance marine ingredients across global applications.
Recent Developments
- In March 2025, Aker BioMarine partnered with Nordmann to expand distribution of its marine-based ingredients—SUPERBA Krill Oil, Revervia™, and PL+™—across the DACH region, strengthening its presence in the European market.
- In July 2024, Marine Biologics revealed its intention to debut a macroalgae-based ingredient prototype by September, using its proprietary brown algae microrefinery platform to deliver high-value functional extracts.
- In early 2025, Aker BioMarine introduced Revervia™, a premium plant-based DHA oil sourced from algae, enhancing its sustainable ingredient portfolio targeting human health and nutrition markets.
- In 2025, Cargill’s bioindustrial division collaborated with Arizona State University to develop new marine-based materials for semiconductor applications, expanding the scope of marine biotechnology innovations.
Market Concentration & Characteristics
The Bio marine ingredients market exhibits moderate to high market concentration, with a mix of dominant multinational corporations and specialized regional players. Large firms such as Aker Bio Marine AS and Cargill Incorporated maintain significant market share through integrated supply chains, technological expertise, and global distribution networks. Smaller companies and startups contribute through innovation in algae-based ingredients, sustainability-focused processes, and niche product offerings. It is characterized by strong emphasis on natural origin, bioactivity, and regulatory compliance, aligning with clean-label and eco-conscious consumer trends. The market operates under strict environmental and safety standards, especially in Europe and North America, which reinforces quality and traceability requirements. High entry barriers exist due to capital-intensive processing technologies, complex extraction protocols, and patent-protected formulations. It shows dynamic growth potential driven by cross-industry applications, while seasonal sourcing challenges and resource availability influence pricing and supply consistency. Companies compete through R&D, partnerships, and product diversification to gain strategic advantage.
Report Coverage
The research report offers an in-depth analysis based on Type, Source, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for marine-derived ingredients will continue to rise across food, cosmetics, and pharmaceutical industries.
- Algae-based and microorganism-sourced ingredients will gain stronger traction due to sustainability and scalability.
- Clean-label and traceable formulations will dominate new product development pipelines.
- Functional foods and dietary supplements will remain key application areas for marine proteins and omega-3s.
- Technological improvements will reduce production costs and enhance ingredient purity.
- Circular economy models will drive greater use of fishery by-products and reduce raw material waste.
- Regulatory frameworks will increasingly favor sustainably sourced marine ingredients.
- Cross-industry collaborations will help scale innovations and expand market access.
- Emerging economies will create new growth avenues for localized production and distribution.
- Companies will invest in personalized nutrition solutions using bioactive marine compounds.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Bio marine ingredients market?
What are the key segments within the Bio marine ingredients market?
What are some challenges faced by the Bio marine ingredients market?
Who are the major players in the Bio marine ingredients market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Bio Marine Ingredients Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Bio Marine Ingredients Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 2,500 million → 2032: USD 3,895.2 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Bio Marine Ingredients Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Bio Marine Ingredients Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Bio Marine Ingredients Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Bio Marine Ingredients Market Drivers
- 3.3 Bio Marine Ingredients Market Restraints & Challenges
- 3.4 Bio Marine Ingredients Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Bio Marine Ingredients Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Bio Marine Ingredients Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Bio Marine Ingredients category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Bio Marine Ingredients Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Bio Marine Ingredients Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Bio Marine Ingredients market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Bio Marine Ingredients Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Bio Marine Ingredients Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Bio Marine Ingredients Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Bio Marine Ingredients (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Bio Marine Ingredients Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Bio Marine Ingredients Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Bio Marine Ingredients Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Bio Marine Ingredients Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Bio Marine Ingredients Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Bio Marine Ingredients Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Bio Marine Ingredients Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Bio Marine Ingredients Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Bio Marine Ingredients Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
