
Market Overview
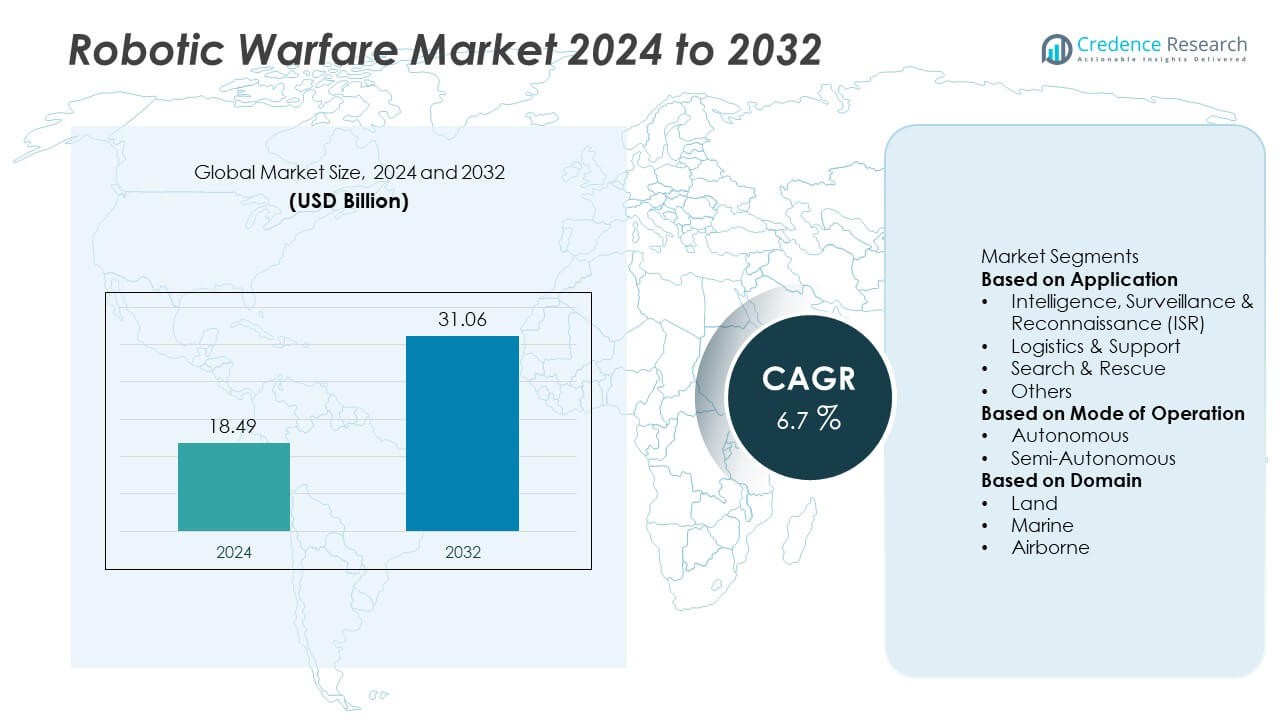
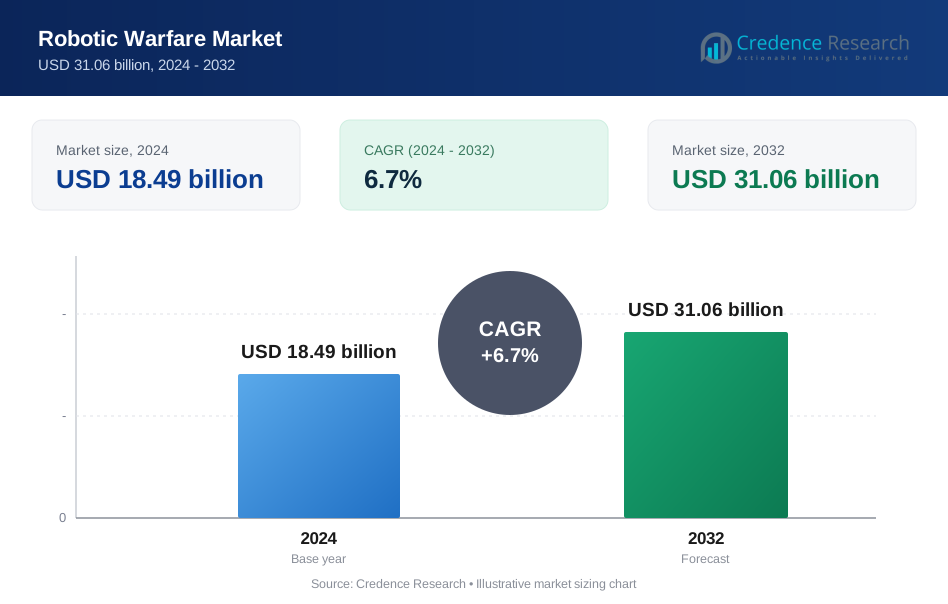
The global robotic warfare market was valued at USD 18.49 billion in 2024 and is projected to reach USD 31.06 billion by 2032, growing at a CAGR of 6.7% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Robotic Warfare Market Size 2024 | USD 18.49 Billion |
| Robotic Warfare Market, CAGR | 6.7% |
| Robotic Warfare Market Size 2032 | USD 31.06 Billion |
The robotic warfare market is led by key players including Dassault Group, Cobham plc, General Atomics, Lockheed Martin Corporation, BAE Systems plc, Boeing, Elbit Systems Ltd., AeroVironment, Inc., Northrop Grumman Corporation, and Autonomous Solutions, Inc. (ASI). These companies lead through innovation in AI-enabled unmanned systems, autonomous drones, and multi-domain robotic platforms. North America dominated the global market with a 41% share in 2024, supported by high defense spending and advanced R&D infrastructure. Asia-Pacific followed with a 26% share, driven by increasing military modernization and adoption of autonomous systems in China, India, and Japan. Continuous innovation and government collaboration enhance market competitiveness globally.
Market Insights
- The global robotic warfare market was valued at USD 18.49 billion in 2024 and is projected to reach USD 31.06 billion by 2032, growing at a CAGR of 6.7% during the forecast period.
- Market growth is driven by increasing investments in autonomous defense technologies, expanding use of unmanned ground and aerial vehicles, and rising demand for AI-driven combat systems.
- Key trends include the integration of swarm robotics, machine learning-based targeting, and hybrid multi-domain platforms enhancing tactical efficiency.
- The competitive landscape is led by Lockheed Martin, BAE Systems, Boeing, Northrop Grumman, and General Atomics, focusing on advanced autonomy, cross-domain coordination, and real-time intelligence capabilities.
- North America held 41%, Asia-Pacific 26%, and Europe 28% shares in 2024, while the Intelligence, Surveillance & Reconnaissance (ISR) segment dominated with a 46% share, supported by its widespread application in threat detection and battlefield monitoring.
Market Segmentation Analysis:
By Application
The Intelligence, Surveillance & Reconnaissance (ISR) segment dominated the robotic warfare market with a 46% share in 2024. This dominance is driven by the growing adoption of unmanned systems for real-time data collection, threat detection, and battlefield monitoring. Defense forces increasingly rely on ISR robots to enhance situational awareness and minimize human exposure in high-risk zones. Advancements in AI, high-resolution imaging, and communication systems are improving reconnaissance precision. Expanding deployment of autonomous drones and ground robots for border security and tactical missions continues to strengthen this segment’s leadership globally.
- For instance, Northrop Grumman developed the RQ-4B Global Hawk Block 40, equipped with the AN/ZPY-2 Multi-Platform Radar Technology Insertion Program (MP-RTIP) sensor capable of scanning 100,000 km² per mission.
By Mode of Operation
The semi-autonomous segment held a 59% share in 2024, supported by its balance between human oversight and autonomous functionality. Semi-autonomous systems are widely used in surveillance, logistics, and combat support due to their reliability and controlled decision-making. They offer enhanced safety, precision, and adaptability under dynamic battlefield conditions. Military agencies favor semi-autonomous robots for missions requiring partial human intervention to ensure compliance with combat rules and ethical considerations. The integration of AI-driven navigation and remote-control systems further boosts adoption across land and aerial defense platforms.
- For instance, L3Harris Technologies developed the T7 multi-mission robotic platform, which has a total weight of 322 kilograms and is equipped with an intuitive haptic feedback arm that provides human-like dexterity and enables precision control. Its arm can lift over 113 kilograms near the chassis or more than 27 kilograms at full extension.
By Domain
The land domain segment accounted for a 52% share in 2024, emerging as the dominant category in robotic warfare. Land-based robots are extensively used for reconnaissance, bomb disposal, logistics support, and combat operations. Increasing demand for unmanned ground vehicles (UGVs) enhances troop protection and operational efficiency. Major defense organizations are investing in advanced ground robots equipped with autonomous mobility, AI vision, and weapon systems. Rising deployment of robotic tanks, surveillance rovers, and logistics carriers across conflict zones and border patrol operations continues to drive growth within this segment.
Key Growth Drivers
Increasing Defense Modernization Programs
Global defense forces are rapidly adopting robotic systems to enhance combat readiness and reduce human casualties. Modernization initiatives in the U.S., China, and European nations are focusing on integrating unmanned ground, air, and marine platforms. These systems improve mission accuracy, endurance, and intelligence-gathering capabilities. Governments are investing heavily in AI-driven robotic systems and autonomous weapon technologies to strengthen surveillance and battlefield decision-making, fueling consistent growth in robotic warfare adoption.
- For instance, QinetiQ Group and Pratt Miller Defence developed the RCV-L (Robotic Combat Vehicle-Light) prototype, a diesel-electric hybrid capable of reaching a top speed of 64 km/h.
Rising Adoption of Unmanned Systems for ISR Operations
The growing use of unmanned systems for Intelligence, Surveillance, and Reconnaissance (ISR) missions is a major growth driver. Defense organizations are deploying robotic drones and ground vehicles for real-time data collection and situational analysis. These systems enhance decision-making efficiency while minimizing risks to soldiers. Continuous advancements in imaging sensors, AI-based analytics, and autonomous control technologies further improve ISR accuracy. Expanding use of ISR robotics across border patrols, reconnaissance missions, and urban warfare drives sustained market growth.
- For instance, Elbit Systems developed the Hermes 900 StarLiner UAV equipped with a 450 kg payload capacity and a flight endurance of up to 36 hours. The platform carries EO/IR sensors, SAR/GMTI radar, and SIGINT modules, transmitting real-time data through encrypted satellite links.
Integration of Artificial Intelligence and Machine Learning
AI and machine learning integration is transforming the effectiveness of robotic warfare systems. These technologies enable autonomous navigation, real-time threat assessment, and adaptive combat responses. Defense contractors are developing smart robots capable of self-learning and multi-domain coordination. AI-based algorithms improve decision-making accuracy, enabling robots to analyze complex data and execute missions with minimal human input. The growing need for faster response systems and autonomous defense operations continues to strengthen market expansion globally.
Key Trends & Opportunities
Emergence of Swarm Robotics in Military Operations
Swarm robotics is emerging as a transformative trend in robotic warfare. It involves deploying multiple coordinated robotic units that operate autonomously to achieve shared objectives. Defense agencies are experimenting with swarm drones for surveillance, electronic warfare, and coordinated strikes. This technology enhances coverage, adaptability, and redundancy on the battlefield. Ongoing R&D investments in swarm intelligence and communication systems are expected to open new opportunities for cost-effective and scalable robotic warfare solutions.
- For instance, Boeing demonstrated its MQ-28 Ghost Bat drone system, which can operate alongside crewed aircraft in multi-ship missions controlled by a single operator. Each autonomous drone measures 11.7 meters in length and carries a modular payload of up to 500 kilograms for missions such as ISR and electronic warfare.
Development of Hybrid and Multi-Domain Robotic Platforms
The industry is witnessing a shift toward hybrid robotic platforms capable of operating across land, air, and marine domains. These multi-domain robots offer flexibility in reconnaissance, logistics, and tactical missions. Defense contractors are designing modular systems that can transition between terrains and communication environments. Such developments support joint-force operations and interoperability among military branches. The growing demand for versatile and rapid-response robotic units presents new opportunities for innovation in hybrid warfare technologies.
- For instance, Northrop Grumman developed the MQ-8C Fire Scout, an unmanned helicopter designed for both naval and land-based operations with an endurance of 12 hours and operational range exceeding 278 kilometers.
Key Challenges
High Cost of Development and Deployment
Developing advanced robotic warfare systems requires significant investment in research, testing, and integration of AI and sensor technologies. The high procurement and maintenance costs limit adoption, especially among developing nations. Complex defense procurement procedures and long development cycles also delay deployment. Despite potential for long-term cost savings, the initial financial burden remains a key barrier to large-scale adoption. Manufacturers are focusing on modular and cost-optimized designs to overcome these economic challenges.
Ethical and Regulatory Concerns Over Autonomous Weapons
The growing use of autonomous robots in combat raises ethical and legal concerns. International regulations regarding lethal autonomous weapon systems (LAWS) remain inconsistent, creating operational uncertainty. The potential for unintended engagements or lack of human accountability intensifies debate on deployment ethics. Many nations are balancing technological progress with strict oversight to ensure compliance with humanitarian laws. Establishing clear frameworks for human-in-the-loop control and accountability remains essential to address public and regulatory concerns.
Regional Analysis
North America
North America held a 41% share in 2024, driven by strong investments in defense modernization and advanced autonomous technologies. The United States leads the region with extensive use of unmanned ground and aerial systems for surveillance, reconnaissance, and combat operations. High defense spending by the U.S. Department of Defense and collaborations with companies such as Lockheed Martin and Northrop Grumman strengthen regional dominance. The integration of AI, robotics, and cybersecurity solutions in warfare systems further enhances operational capability. Continuous R&D in autonomous weapon systems and swarm robotics reinforces North America’s leadership in robotic warfare technologies.
Europe
Europe accounted for a 28% share in 2024, supported by growing defense budgets and collaborative military projects under the European Defence Fund. Countries such as the United Kingdom, France, and Germany are investing heavily in autonomous ground and aerial combat systems to enhance security capabilities. The region’s focus on ethical AI deployment and interoperability across NATO allies encourages innovation. European defense companies are developing advanced robotic systems for reconnaissance, logistics, and border protection. The increasing integration of robotic platforms into military modernization programs continues to strengthen Europe’s position in the global market.
Asia-Pacific
Asia-Pacific captured a 26% share in 2024, propelled by expanding defense programs and rapid technological adoption in countries like China, India, Japan, and South Korea. Governments are prioritizing the development of unmanned combat vehicles, surveillance drones, and robotic naval systems. China’s investment in AI-driven defense systems and India’s modernization under the “Make in India” initiative drive significant market growth. Regional tensions and border disputes are accelerating adoption of autonomous and semi-autonomous systems for surveillance and combat. Continuous funding for R&D and domestic production capabilities enhances Asia-Pacific’s growing influence in the global robotic warfare market.
Middle East & Africa
The Middle East & Africa held a 3% share in 2024, driven by increasing military expenditure and defense diversification efforts. Countries such as Israel, Saudi Arabia, and the UAE are adopting advanced robotic systems for surveillance, border control, and counter-terrorism operations. Israel leads regional innovation with extensive deployment of autonomous vehicles and drones in defense missions. Ongoing geopolitical instability and cross-border security challenges are fueling investments in AI-enabled warfare systems. Partnerships with global defense manufacturers and technology providers further support regional adoption and modernization of military robotics infrastructure.
Latin America
Latin America represented a 2% share in 2024, with growth driven by modernization initiatives in Brazil, Mexico, and Colombia. The region is adopting robotic systems for border surveillance, counter-narcotics, and disaster response operations. Defense agencies are exploring unmanned ground and aerial systems to enhance situational awareness and mission efficiency. Limited defense budgets constrain large-scale deployment, but collaborations with U.S. and European defense firms are facilitating technology transfer. Increasing focus on upgrading national security infrastructure and integrating autonomous surveillance technologies supports gradual market growth across the region.
Market Segmentations:
By Application
- Intelligence, Surveillance & Reconnaissance (ISR)
- Logistics & Support
- Search & Rescue
- Others
By Mode of Operation
- Autonomous
- Semi-Autonomous
By Domain
- Land
- Marine
- Airborne
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the robotic warfare market includes major players such as Dassault Group, Cobham plc, General Atomics, Lockheed Martin Corporation, BAE Systems plc, Boeing, Elbit Systems Ltd., AeroVironment, Inc., Northrop Grumman Corporation, and Autonomous Solutions, Inc. (ASI). These companies dominate through advanced robotics platforms, AI integration, and strong defense partnerships. Leading manufacturers focus on developing autonomous drones, unmanned ground vehicles, and intelligent combat systems equipped with advanced sensors and control algorithms. Strategic collaborations between defense contractors and governments drive innovation and deployment across air, land, and marine domains. Firms are also investing in next-generation swarm robotics, real-time communication systems, and autonomous decision-making technologies to enhance combat efficiency. Increasing R&D spending and a shift toward hybrid and AI-enabled robotic systems continue to intensify global competition while supporting modernization efforts across defense forces worldwide.
Key Player Analysis
- Dassault Group
- Cobham plc
- General Atomics
- Lockheed Martin Corporation
- BAE Systems plc
- Boeing
- Elbit Systems Ltd.
- AeroVironment, Inc.
- Northrop Grumman Corporation
- Autonomous Solutions, Inc. (ASI)
Recent Developments
- In October 2025, General Atomics Aeronautical Systems signed a deal with Hanwha Aerospace to jointly develop a STOL (short-takeoff and landing) variant of the “Gray Eagle” drone. The agreement targets first flight in 2027 and local production in South Korea.
- In September 2025, Lockheed Martin and BAE Systems plc announced a strategic partnership to develop a new range of modular uncrewed air systems for attack and electronic warfare roles, designed for flexible launch from air, land or sea platforms.
- In September 2025, BAE Systems revealed it is aiming to bring its autonomous submarine platform “Herne” to market by the end of 2026.
- In June 2025, General Atomics demonstrated its MQ‑20 Avenger unmanned jet using the latest autonomous mission software, engaging both live and virtual aircraft in the exercise.
Report Coverage
The research report offers an in-depth analysis based on Application, Mode of Operation, Domain and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will expand with growing defense modernization and increased use of unmanned systems.
- AI and machine learning integration will enhance autonomous decision-making and targeting accuracy.
- Swarm robotics will play a key role in surveillance and coordinated combat operations.
- Demand for semi-autonomous systems will rise due to balance between control and autonomy.
- Governments will increase funding for R&D in AI-enabled combat and reconnaissance robots.
- Hybrid platforms capable of operating across air, land, and marine domains will gain traction.
- Ethical and regulatory frameworks will shape deployment of lethal autonomous systems.
- Partnerships between defense contractors and governments will accelerate innovation.
- Asia-Pacific will experience strong growth due to expanding military programs in China and India.
- Continuous advancements in communication, navigation, and sensor technologies will redefine future battlefield strategies.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Robotic Warfare market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Robotic Warfare market projected to grow between 2025 and 2032?
Which Robotic Warfare market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Robotic Warfare market?
Who are the leading companies in the Robotic Warfare market?
Which region commanded the largest share of the Robotic Warfare market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 18.49 billion → 2032: USD 31.06 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Robotic Warfare Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Robotic Warfare Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Robotic Warfare Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Robotic Warfare Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Robotic Warfare Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Robotic Warfare Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Robotic Warfare Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Robotic Warfare Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 18.49 billion → 2032: USD 31.06 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Robotic Warfare Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Robotic Warfare Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Robotic Warfare Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Robotic Warfare Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

