
Market Overview:
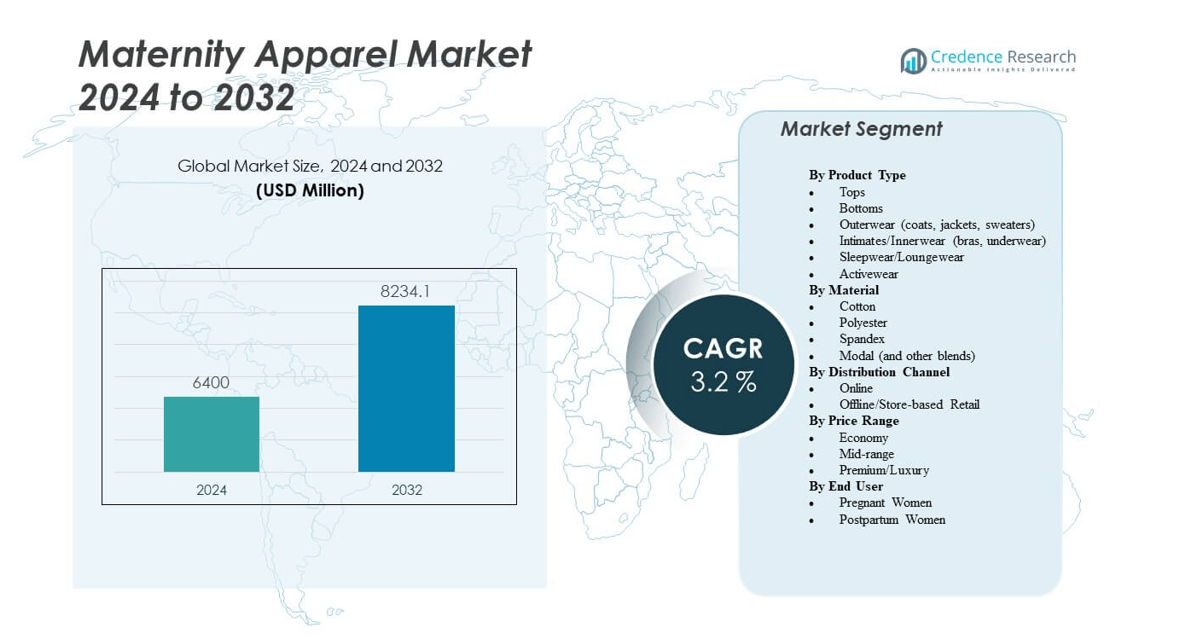
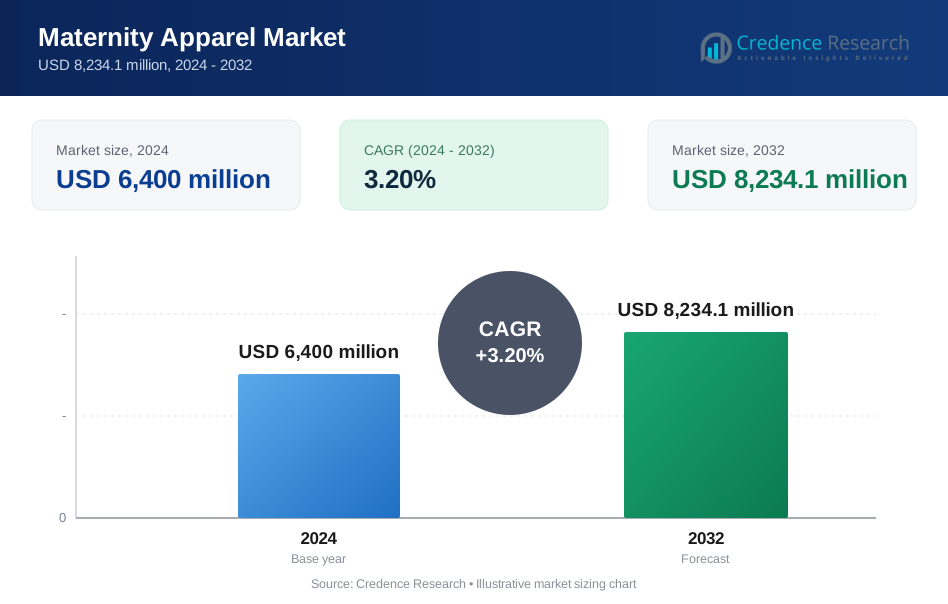
The Maternity Apparel Market is projected to grow from USD 6,400 million in 2024 to an estimated USD 8,234.1 million by 2032, with a compound annual growth rate (CAGR) of 3.2% from 2024 to 2032.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Maternity Apparel Market Size 2024 | USD 6,400 million |
| Maternity Apparel Market, CAGR | 3.2% |
| Maternity Apparel Market Size 2032 | USD 8,234.1 million |
Growth in the maternity apparel market is supported by rising awareness of maternal health, increasing focus on comfort, and the influence of evolving fashion trends. Women seek clothing that blends functionality with style, which has encouraged manufacturers to design innovative collections. Growing disposable incomes and the popularity of online retail platforms are also driving demand. The expansion of working women populations globally adds to this momentum, as professional maternity wear becomes a priority.
Regionally, North America and Europe lead the maternity apparel market due to strong consumer awareness and established fashion industries. Asia Pacific is emerging as a key growth hub, fueled by rising birth rates, increasing urbanization, and expanding retail networks. Countries such as China and India are seeing heightened demand as consumers embrace modern styles. Meanwhile, Latin America and the Middle East are gradually developing, with growing disposable incomes and shifting lifestyle patterns boosting adoption across these regions.
Market Insights:
- The Maternity Apparel Market is valued at USD 6,400 million in 2024 and expected to reach USD 8,234.1 million by 2032, growing at a CAGR of 3.2%.
- Rising demand for comfortable, functional, and stylish maternity clothing continues to drive product innovation.
- Growing disposable incomes and lifestyle changes encourage spending on both premium and mid-range maternity apparel.
- High price sensitivity in developing economies limits the adoption of luxury and designer maternity collections.
- Limited awareness in rural regions and restricted distribution channels remain barriers to market expansion.
- North America leads with 34% share, followed by Europe at 27%, while Asia Pacific shows the fastest growth.
- Online retail channels strengthen global accessibility, while offline stores maintain relevance for personal fittings.
Market Drivers:
Rising Demand for Comfortable and Functional Maternity Wear Across Global Regions
The Maternity Apparel Market is strongly influenced by rising demand for comfortable and functional clothing that supports women during pregnancy. It is driven by a preference for breathable fabrics and ergonomic designs that improve daily wear. Women increasingly choose specialized garments that provide style without compromising comfort. The rising participation of women in professional sectors creates need for formal maternity wear. Urban consumers actively seek products that blend practicality with fashion-driven designs. The availability of new collections by leading brands strengthens this shift. It encourages buyers to explore innovative offerings through offline and online channels. The growing acceptance of body-positive fashion further contributes to its expansion.
- For example, Seraphine markets its Twin Pack Bamboo Nursing Bras in bamboo viscose that offers hypoallergenic, temperature‑regulating, moisture‑wicking, and antibacterial properties, along with a seamless design for all‑day comfort during pregnancy and nursing. The fabric adapts to body changes while delivering a breathable fit.
Expansion of Online Retail Platforms and Enhanced Consumer Accessibility
Online retail platforms significantly accelerate growth by offering consumers easy access to varied maternity collections. It is supported by secure payment systems and flexible return policies that build confidence. Online shopping platforms allow detailed product descriptions and sizing guidance, which reduce hesitation among buyers. Growing digital adoption in developing economies further increases visibility of global maternity brands. Social media campaigns by influencers and celebrities help retailers gain traction in this segment. Consumer engagement strategies focused on digital advertisements expand awareness of seasonal collections. Competitive pricing options create strong appeal for middle-income groups. This combination enhances the penetration of maternity wear into untapped markets.
Growing Disposable Incomes and Shifts in Consumer Lifestyle Preferences
The rising disposable incomes of consumers play a vital role in supporting maternity wear sales. It enables women to prioritize both comfort and aesthetics during pregnancy. Lifestyle changes and exposure to international fashion trends increase demand for premium maternity wear. Professional women seek designs that allow them to maintain style within workplace environments. The influence of celebrity endorsements raises the desirability of high-end brands. Retailers introduce exclusive designer collections that position maternity clothing as a lifestyle choice. It drives stronger consumer attachment to luxury maternity segments. Expanding middle-class populations in developing nations further create consistent demand for affordable ranges.
Increasing Focus on Maternal Health and Wellness During Pregnancy Phases
Maternal health awareness significantly strengthens the need for specialized apparel that ensures both comfort and safety. It influences product development, encouraging designs that support changing body shapes. Healthcare providers emphasize the importance of non-restrictive clothing that reduces discomfort. This emphasis shapes consumer behavior, leading to wider adoption of maternity garments. Demand for fitness-oriented maternity wear also grows in response to rising wellness culture. Activewear collections designed for expectant mothers gain popularity among health-conscious buyers. Retailers respond with products that allow women to continue daily exercise routines safely. The role of wellness-focused maternity clothing reinforces long-term industry relevance.
- For example, Nike’s Zenvy (M) maternity leggings are made with InfinaSoft fabric, offering twice the stretch of standard spandex and a buttery-soft feel. They integrate sweat-wicking Dri-FIT technology, keeping expectant mothers comfortable during exercise across pregnancy stages.
Market Trends:
Integration of Sustainable Materials and Eco-Friendly Production Approaches
Sustainable fashion adoption strongly influences maternity wear design and production methods. The Maternity Apparel Market is experiencing a transition toward eco-friendly fabrics such as organic cotton and bamboo blends. It aligns with growing awareness of environmental responsibility among consumers. Retailers increasingly highlight certifications that guarantee sustainability in supply chains. Consumers appreciate brands that emphasize ethical sourcing practices and reduced carbon footprints. Designers experiment with biodegradable packaging and recycled materials to enhance eco-value. Rising environmental campaigns strengthen demand for responsible apparel options. The integration of sustainable practices positions maternity clothing brands competitively in long-term growth cycles.
- H&M offers its Conscious Collection that features clothing made from sustainable materials such as organic cotton and recycled polyester. The brand also reported that in 2023, it achieved an 85% share of materials that were either recycled or sustainably sourced.
Growing Popularity of Multi-Functional and Transitional Maternity Clothing Designs
Consumers are increasingly drawn to multi-functional maternity clothing that extends usability beyond pregnancy. It reflects a shift toward clothing designed to transition into nursing and post-pregnancy phases. Retailers introduce garments with adjustable fits, elastic bands, and detachable features. This trend appeals to women seeking practical investments in wardrobe essentials. Premium collections often highlight flexibility in styling across different stages of motherhood. Social media platforms showcase the adaptability of such designs, boosting wider adoption. Manufacturers gain long-term consumer loyalty by emphasizing reusability and cost-effectiveness. The demand for transitional clothing reflects evolving priorities of modern mothers.
Influence of Fashion Collaborations and Celebrity Endorsements on Consumer Preferences
Fashion collaborations between maternity brands and mainstream designers create unique collections that capture attention. The Maternity Apparel Market benefits from endorsements by high-profile personalities who promote stylish maternity looks. Celebrity influence elevates brand visibility and strengthens consumer confidence in premium collections. Social media campaigns highlight exclusive launches and drive digital engagement. Fashion-forward mothers adopt these trends to align with popular culture. Designers leverage collaborations to expand product appeal across global markets. This strategy enhances product desirability and boosts sales for featured collections. The rising importance of influencer marketing strengthens momentum for maternity fashion lines.
Technological Integration in Retail and Personalized Consumer Experiences
Retailers are introducing advanced digital solutions to improve shopping experiences in maternity fashion. Virtual fitting tools enable consumers to visualize clothing without physical trials. It reduces concerns regarding sizing and fit across changing body stages. Augmented reality applications add convenience by offering interactive engagement. Personalized product recommendations based on purchase history increase sales conversions. E-commerce platforms adopt AI-driven analytics to predict consumer trends effectively. Retailers expand loyalty programs supported by data-driven insights for repeat purchases. These innovations enhance customer trust and transform maternity apparel shopping behavior globally.
- For instance, ASOS piloted its “See My Fit” augmented reality tool in partnership with Zeekit, enabling shoppers to view clothing on 16 digital models ranging in sizes 4 to 18. The tool digitally mapped garments onto models in a realistic way, giving customers a clearer view of how items, including maternity wear, might look on different body types.
Market Challenges Analysis:
High Price Sensitivity and Uneven Affordability Across Regions
The Maternity Apparel Market faces significant challenges from price sensitivity among consumers in developing economies. It limits adoption of premium brands where affordability remains a primary concern. Local retailers often dominate with low-cost alternatives, restricting penetration for luxury apparel. High production costs for sustainable or designer lines reduce their competitiveness. Women in low-income regions prioritize essentials over fashion-focused maternity wear. Price gaps between developed and emerging regions highlight disparities in market accessibility. Retailers struggle to balance affordability with quality in these circumstances. It reflects the pressing need for inclusive pricing strategies across regions.
Limited Awareness and Accessibility in Rural and Underserved Markets
Limited awareness of maternity-specific apparel continues to constrain demand in rural and underserved areas. It is affected by cultural practices where traditional wear replaces specialized maternity clothing. Distribution channels often fail to reach remote regions, restricting market expansion. Lack of targeted marketing campaigns reduces exposure for modern maternity collections. Smaller retailers struggle with limited resources to promote maternity fashion lines. Healthcare initiatives promoting wellness rarely emphasize apparel benefits. Slow adoption in underserved markets hinders the growth potential for global brands. These challenges require strategic interventions to ensure balanced market presence.
Market Opportunities:
Growing Adoption of Digital Platforms for Global Market Penetration
The Maternity Apparel Market holds strong opportunities through expanded digital presence across global regions. E-commerce platforms enable retailers to reach consumers without geographic restrictions. It opens direct access to emerging markets with rising internet adoption. Online marketing campaigns improve visibility for maternity collections among younger demographics. Digital platforms reduce operational costs while supporting faster delivery networks. Brands can engage directly with consumers through personalized digital experiences. The opportunity to expand across social commerce channels enhances competitiveness. This shift toward digitalization offers long-term scalability for maternity apparel players.
Expansion of Premium and Wellness-Oriented Maternity Fashion Collections
The demand for wellness-focused and premium maternity wear presents profitable opportunities for retailers. It creates potential for brands to introduce activewear collections that align with fitness culture. Premium designs gain acceptance among professionals seeking style without compromising comfort. The rising awareness of body positivity further promotes demand for tailored clothing. Healthcare partnerships may support awareness of specialized apparel benefits. Retailers that position maternity clothing as lifestyle essentials gain loyal customer bases. Product innovation in luxury and wellness lines reinforces strong consumer engagement. This opportunity positions maternity fashion as both a practical and aspirational choice.
Market Segmentation Analysis:
By Product Type
The Maternity Apparel Market by product type highlights varied demand across tops, bottoms, outerwear, intimates, sleepwear, and activewear. Tops and bottoms dominate sales because they serve as everyday essentials during pregnancy. Outerwear, including coats, jackets, and sweaters, shows strong traction in colder climates where practicality aligns with seasonal needs. Intimates and innerwear remain vital, driven by the necessity of comfort and body support. Sleepwear and loungewear reflect increasing time spent at home and focus on rest. Activewear records significant growth with more women prioritizing fitness and wellness during maternity. It underlines the broad diversification of maternity wardrobes.
- For instance, Fitta Mamma, a maternity activewear brand, designs moisture-wicking leggings made from high-performance stretch fabric with flat seams and supportive waistbands, offering comfort for prenatal yoga, exercise, and postpartum recovery.
By Material
Material selection plays a decisive role in shaping preferences across maternity clothing. Cotton leads consumption due to its breathable, soft, and hypoallergenic properties that ensure comfort during pregnancy. Polyester remains popular in mid-range categories, offering cost efficiency and durability. Spandex demand rises due to its stretchable properties that adapt to body changes. Modal and blended fabrics gain acceptance by combining softness with sustainability appeal. Each material caters to different consumer needs ranging from affordability to premium quality. It reinforces the importance of fabric innovation in creating functional yet stylish maternity collections.
- For instance, Motherhood Maternity offers apparel such as its Essential Stretch Secret Fit Belly® leggings, made with 87% cotton and spandex blends, providing softness, stretch, and breathability for expectant mothers.
By Distribution Channel
The distribution channel landscape reflects a dual structure of online and offline retail. Online platforms continue to expand, offering convenience, wider variety, and favorable return policies. Social commerce and influencer-led campaigns further boost digital demand. Offline or store-based retail retains significance as many consumers prefer personal fittings and fabric checks before purchase. It remains particularly relevant in markets with lower digital penetration. Hybrid models that integrate both online and offline strategies strengthen brand positioning. The evolution of retail channels shapes consumer accessibility and brand loyalty.
By Price Range
Price range segmentation reveals distinctive consumer behaviors across economy, mid-range, and premium categories. Economy apparel dominates emerging economies where affordability guides purchasing decisions. Mid-range options attract growing middle-class populations that value both quality and price balance. Premium and luxury collections thrive in developed regions where fashion and exclusivity are prioritized. Designer collaborations and celebrity endorsements strengthen the appeal of higher-end maternity wear. It reflects clear segmentation across consumer income levels, encouraging brands to diversify product portfolios. The balance of affordability and exclusivity continues to define growth strategies.
By End User
End user segmentation divides demand between pregnant women and postpartum women. Pregnant women represent the largest consumer group, driving consistent demand for essentials like tops, bottoms, and innerwear. Postpartum women increasingly contribute to market growth by seeking nursing-friendly and transitional apparel. This segment values functionality, adaptability, and comfort that extend beyond pregnancy. Retailers respond with clothing that serves dual purposes across maternity and post-maternity phases. It enhances the lifecycle value of maternity garments. The inclusion of both groups ensures sustainable growth and broader consumer engagement.
Segmentation:
By Product Type
- Tops
- Bottoms
- Outerwear (coats, jackets, sweaters)
- Intimates/Innerwear (bras, underwear)
- Sleepwear/Loungewear
- Activewear
By Material
- Cotton
- Polyester
- Spandex
- Modal (and other blends)
By Distribution Channel
- Online
- Offline/Store-based Retail
By Price Range
- Economy
- Mid-range
- Premium/Luxury
By End User
- Pregnant Women
- Postpartum Women
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis:
North America holds the largest share of the Maternity Apparel Market with 34% of global revenue. Strong consumer awareness, established retail networks, and high purchasing power drive this dominance. The region benefits from premium product availability supported by fashion-driven designs and celebrity endorsements. Online and offline channels both contribute significantly, with digital sales growing at a faster pace. Healthcare campaigns emphasizing maternal wellness also support adoption of specialized apparel. It reflects a mature market where innovation and brand differentiation remain critical growth strategies.
Europe accounts for 27% of the market share, supported by a well-developed fashion industry and strong demand for premium maternity wear. Sustainable and eco-friendly collections gain traction in this region due to heightened consumer awareness. Countries such as Germany, France, and the United Kingdom drive most of the regional growth. Retailers invest heavily in store-based formats but also embrace digital platforms to reach wider audiences. The region shows consistent interest in wellness-focused maternity clothing. It demonstrates how fashion consciousness and regulatory focus on sustainable production influence product adoption.
Asia Pacific captures 24% of the Maternity Apparel Market and demonstrates the fastest growth potential. Rising birth rates, urbanization, and expanding middle-class populations create strong demand for maternity wear. China and India dominate this segment, supported by increasing online retail penetration. Affordability remains key, though premium and transitional clothing categories are gaining attention. Latin America contributes 9% while the Middle East & Africa account for 6% of the market. It shows that emerging economies are gradually shaping the industry landscape through evolving consumer expectations and rising disposable incomes.
Key Player Analysis:
- Seraphine
- H&M Group (H&M Mama)
- ASOS
- Gap Inc.
- Hatch Collection
- Ingrid & Isabel
- Isabella Oliver
- FirstCry (BabyHug)
- Hotmilk Lingerie
- Pinkblush Maternity
- Mamacouture
- Belabumbum
- Boob Design
- Cache Cœur
- Mamalicious
Competitive Analysis:
The Maternity Apparel Market features strong competition driven by global and regional brands offering diverse collections. H&M Mama, ASOS, and Gap Inc. maintain dominance with affordable and stylish options distributed across large retail networks. Seraphine and Hatch Collection focus on premium designs that appeal to fashion-conscious consumers seeking exclusivity. Ingrid & Isabel, Isabella Oliver, and Boob Design emphasize comfort-driven apparel with sustainable materials to strengthen brand positioning. FirstCry and Mamacouture expand presence in emerging markets by catering to price-sensitive consumers. Niche players such as Hotmilk Lingerie, Belabumbum, and Cache Cœur build brand identity through specialized categories like intimate wear. Pinkblush Maternity and Mamalicious attract younger demographics through trend-focused designs and active online engagement. It creates a competitive landscape where affordability, sustainability, and innovation shape differentiation strategies among leading players.
Recent Developments:
- In July 2025, Next and Frasers Group completed the acquisition of Seraphine, a leading maternity apparel brand, highlighting ongoing consolidation trends within the specialist maternity retail sector and expanding the buyers’ presence in premium maternity fashion.
- In July 2025, Seraphine underwent a significant transition when Next plc acquired key assets of the maternity fashion brand for £600,000 after Seraphine entered administration earlier that month. As part of the acquisition, Seraphine's founder, Cécile Reinaud, has returned in an advisory capacity with Next aiming to relaunch the brand and reinforce its position in the maternity apparel market, preserving its core identity in fashionable and functional clothing for expectant mothers.
- In June 2025, H&M Group announced a multi-year partnership with Circulose, a recycled textile manufacturer, to source significant volumes of Circulose fiber for its collections, replacing a substantial share of virgin viscose used across the company’s brands.
- In July 2024, Motherhood Maternity partnered with Kohl’s to launch shop-in-shop concepts across several Kohl’s locations, marrying physical retail reach with refreshed brand imaging to tap wider audiences.
Report Coverage:
The research report offers an in-depth analysis based on Product Type, Material, Distribution Channel, Price Range and End User. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising preference for stylish yet functional maternity wear will drive innovation in product designs.
- Growing adoption of sustainable fabrics will strengthen consumer trust in eco-friendly maternity collections.
- Expanding online retail channels will enhance global reach and improve accessibility for diverse consumer groups.
- Increasing focus on activewear and wellness apparel will create opportunities in fitness-oriented maternity lines.
- Collaborations between fashion brands and influencers will boost brand visibility among younger demographics.
- Technological integration, such as virtual fitting tools, will improve shopping experiences and reduce sizing concerns.
- Premium and luxury maternity fashion will gain traction in developed regions with higher purchasing power.
- Emerging economies will contribute to growth through rising disposable incomes and changing lifestyle preferences.
- Greater emphasis on postpartum clothing will extend product lifecycles and attract repeat customers.
- Continuous innovation in fabrics and multi-functional designs will ensure long-term competitiveness for key players.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Focus on Comfort, Functionality, and Style
Expectant mothers increasingly seek maternity apparel that combines comfort, ergonomic support, and contemporary fashion, prompting brands to innovate with breathable fabrics and adaptive designs that cater to changing body shapes.
Expansion of Online Retail and Digital Accessibility
The proliferation of e-commerce platforms and digital marketing has made maternity apparel more accessible, especially in emerging markets, while online sizing tools and influencer campaigns boost consumer confidence and drive global sales.
Rising Disposable Incomes and Lifestyle Shifts
Growing middle-class populations and higher disposable incomes, particularly in developing regions, enable consumers to spend more on both premium and mid-range maternity wear, supporting market expansion and diversification.
Increasing Maternal Health and Wellness Awareness
Heightened awareness of maternal health and wellness encourages the adoption of specialized maternity clothing, including activewear and non-restrictive garments, as healthcare providers and wellness trends emphasize the importance of comfort and safety during pregnancy.
Sustainable and Eco-Friendly Product Innovation
Consumer demand for environmentally responsible products is driving brands to incorporate organic, recycled, and sustainable materials into maternity collections, enhancing brand loyalty and aligning with global sustainability trends.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Maternity Apparel Market, and what is its projected size in 2032?
Which Maternity Apparel Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Maternity Apparel Market?
Who are the leading companies in the Maternity Apparel Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Material
- 1.2.1 Cotton
- 1.2.2 Polyester
- 1.2.3 Spandex
- 1.2.4 Modal (and other blends)
- 1.3 By Price Range
- 1.3.1 Economy
- 1.3.2 Mid-range
- 1.3.3 Premium/Luxury
- 1.4 By Product Type
- 1.4.1 Tops
- 1.4.2 Bottoms
- 1.4.3 Outerwear (coats, jackets, sweaters)
- 1.4.4 Intimates/Innerwear (bras, underwear)
- 1.4.5 Sleepwear/Loungewear
- 1.4.6 Activewear
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 6,400 million → 2032: USD 8,234.1 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Maternity Apparel Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Maternity Apparel Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Maternity Apparel Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Maternity Apparel Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Maternity Apparel Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Maternity Apparel Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Maternity Apparel Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Maternity Apparel Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 6,400 million → 2032: USD 8,234.1 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Maternity Apparel Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Material - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Cotton
- 12.3.7.2 Polyester
- 12.3.7.3 Spandex
- 12.3.7.4 Modal (and other blends)
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Price Range - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Economy
- 12.4.7.2 Mid-range
- 12.4.7.3 Premium/Luxury
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Tops
- 12.5.7.2 Bottoms
- 12.5.7.3 Outerwear (coats, jackets, sweaters)
- 12.5.7.4 Intimates/Innerwear (bras, underwear)
- 12.5.7.5 Sleepwear/Loungewear
- 12.5.7.6 Activewear
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Maternity Apparel Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Maternity Apparel Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Maternity Apparel Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Seraphine
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 H&M Group (H&M Mama)
- 17.4 ASOS
- 17.5 Gap Inc.
- 17.6 Hatch Collection
- 17.7 Ingrid & Isabel
- 17.8 Isabella Oliver
- 17.9 FirstCry (BabyHug)
- 17.10 Hotmilk Lingerie
- 17.11 Pinkblush Maternity
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

