
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Meal Kit Market Size 2024 | USD 15981.25 million |
| Meal Kit Market, CAGR | 1.8% |
| Meal Kit Market Size 2032 | USD 18432.87 million |
Market Overview
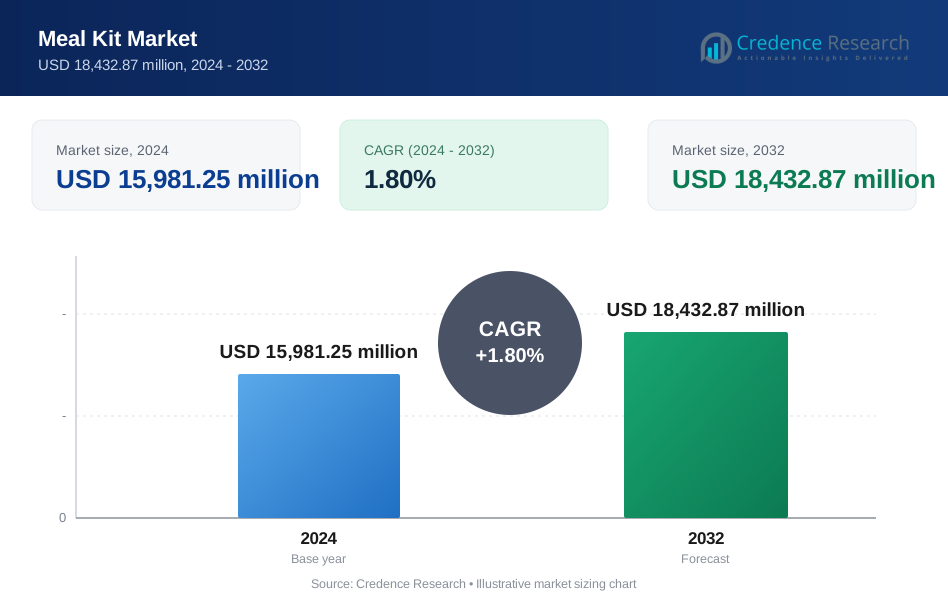
Meal Kit Market size was valued at USD 15981.25 million in 2024 and is anticipated to reach USD 18432.87 million by 2032, at a CAGR of 1.8% during the forecast period (2024-2032).
Key market drivers include the rising consumer preference for convenience, especially in the wake of the COVID-19 pandemic, which has led to an increased reliance on home meal solutions. This shift has fostered the growth of meal kit services, as consumers seek easy access to fresh, pre-portioned ingredients for home-cooked meals. The shift towards healthier eating, along with growing awareness of dietary preferences such as plant-based, gluten-free, and low-calorie options, further propels market demand. Consumers are increasingly opting for meal kits that cater to their specific dietary needs, contributing to product diversification. Additionally, the subscription-based model adopted by meal kit providers appeals to consumers' desire for hassle-free meal planning, ensuring consistent sales and growth. The convenience of subscription models, combined with flexibility in delivery frequency and meal choices, has strengthened customer loyalty. Innovations in packaging, ingredient sourcing, and recipe diversity continue to foster brand differentiation, further attracting a diverse customer base and driving competition among meal kit companies.
Regionally, North America holds the largest market share, driven by a high adoption rate in the United States and Canada, where meal kit subscriptions are widely integrated into the daily routines of consumers. The strong e-commerce infrastructure and the preference for online meal delivery services further boost market penetration in this region. Europe follows closely, with the growing demand for meal kits in the UK, Germany, and France. In these countries, increasing health-consciousness and interest in gourmet cooking experiences have fueled the market's growth. The Asia Pacific region is expected to witness significant growth, with increasing urbanization, rising disposable incomes, and a growing inclination toward Western-style diets contributing to the expansion of meal kit services. Additionally, a greater focus on convenience and time-saving solutions among busy urban populations in countries like China and Japan is expected to drive market expansion. Key players in the market are also focusing on regional expansion to cater to the diverse tastes and preferences of consumers globally, tailoring their offerings to specific regional demands.
Market Insights:
- The Meal Kit Market was valued at USD 15,981.25 million in 2024 and is expected to reach USD 18,432.87 million by 2032.
- Convenience-driven consumer demand, especially post-COVID-19, has significantly accelerated the growth of meal kit services, as consumers seek home-based meal solutions.
- Growing health-consciousness and dietary preferences, such as plant-based, gluten-free, and low-calorie options, are driving the demand for more specialized meal kits.
- Subscription-based models are thriving in the market, offering flexibility in meal choices and delivery frequency, which has strengthened customer retention.
- Technological advancements in packaging, meal personalization, and ingredient sourcing are fueling growth and enhancing differentiation between meal kit providers.
- North America dominates the market with a 40% share, driven by high adoption rates in the United States and Canada, alongside a robust e-commerce infrastructure.
- The Asia-Pacific region is the fastest-growing market, accounting for 15% of the global share, driven by urbanization, rising disposable incomes, and a shift toward Western dietary preferences.
Market Drivers:
Growing Demand for Convenience:
The increasing consumer preference for convenience remains one of the most significant drivers of growth in the meal kit market. With fast-paced lifestyles, particularly in urban areas, consumers are increasingly seeking ways to streamline their daily routines. Meal kits provide a convenient solution by delivering fresh, pre-portioned ingredients with step-by-step recipes, allowing consumers to prepare home-cooked meals without the time-consuming process of meal planning or grocery shopping. This demand for convenience has only intensified following the COVID-19 pandemic, as many individuals turned to home-based meal solutions, further solidifying the market’s growth trajectory. The desire for less time spent on meal preparation, combined with the growing reliance on home delivery services, makes meal kits an attractive option for busy consumers.
Health and Wellness Trends:
The shift towards healthier eating habits is another key driver in the meal kit market. As health-conscious consumers become more aware of the impact of their dietary choices, many are turning to meal kits that cater to their nutritional needs. For instance, the International Food Information Council (IFIC) reported in their 2024 Food and Health Survey that a significant portion of American consumers actively seek meals that are lower in processed ingredients and higher in fresh produce, which has encouraged meal kit providers to expand offerings that include plant-based, gluten-free, low-calorie, and keto-friendly options. Meal kit providers have adapted by offering meals with specific dietary considerations, such as plant-based, gluten-free, low-calorie, and keto-friendly options. This growing awareness around healthier eating has not only boosted demand for nutritious meal kits but also led to innovations in ingredient sourcing and recipe development. By offering balanced meals with fresh and organic ingredients, meal kit companies are tapping into the health-conscious consumer segment, which values clean, nutrient-dense food over heavily processed alternatives.
Subscription Model Popularity:
The rise of subscription-based meal delivery services has significantly contributed to the meal kit market's expansion. Subscription models offer consumers the flexibility of regular, home-delivered meals, eliminating the need for grocery shopping or meal planning while providing cost-effective pricing for recurring orders. This model creates a strong bond between the customer and the meal kit service, fostering brand loyalty and repeat business. Additionally, the option to customize meal preferences and delivery frequency aligns with consumer demands for flexibility, ensuring that meal kits cater to diverse tastes and schedules. For example, HelloFresh has reported substantial growth in its subscriber base by focusing on flexible subscription plans that let customers easily modify or pause their deliveries. As a result, the subscription model has become a major driver in market growth, with many companies expanding their offerings to include a broader range of meal options and dietary preferences.
Technological Innovations and Sustainability:
Technological advancements in packaging, ingredient sourcing, and meal personalization continue to propel the meal kit market forward. Innovations such as eco-friendly packaging and efficient delivery logistics help meal kit companies reduce waste and improve their sustainability profiles. As consumers become more environmentally conscious, these green initiatives play an important role in attracting and retaining customers. Furthermore, technology enables companies to offer more personalized meal plans, using data and consumer preferences to recommend meals tailored to individual tastes, dietary restrictions, and lifestyle choices. These technological innovations are not only enhancing customer experiences but also differentiating brands in a highly competitive market, further fueling growth.
Market Trends:
Health-Conscious and Specialized Meal Options:
As consumers increasingly prioritize health and wellness, the demand for specialized meal options within the meal kit market has grown substantially. Providers are catering to a diverse range of dietary preferences, including plant-based, keto, gluten-free, and low-calorie meals. This trend aligns with the growing interest in clean eating and sustainable food choices. Meal kit companies are focusing on sourcing organic ingredients, reducing preservatives, and offering nutritionally balanced meals that cater to health-conscious consumers. By offering these specialized options, companies not only meet the demand for healthy living but also foster loyalty among consumers who prioritize dietary restrictions and preferences.
Eco-Friendly and Sustainable Packaging:
Sustainability has become a key trend in the meal kit market, driven by increasing consumer awareness about environmental impacts. Meal kit companies are increasingly adopting eco-friendly packaging solutions, such as recyclable materials, compostable containers, and minimalistic packaging designs. These efforts align with consumer demand for brands that prioritize environmental responsibility. For instance, Sun Basket uses fully recyclable and compostable packaging materials, including boxes, insulating materials, and ice packs, while sourcing ingredients from suppliers who employ sustainable farming and fishing methods. Additionally, many companies are working to reduce food waste by offering more precise portion sizes and utilizing ingredients that are sourced sustainably. This trend reflects the broader consumer movement towards reducing ecological footprints and supports the market’s growth among eco-conscious consumers.
Technological Advancements in Personalization:
The use of technology in meal kit services has significantly advanced in recent years, particularly in the area of meal personalization. Companies are leveraging consumer data to offer tailored meal plans based on individual preferences, dietary restrictions, and even health goals. For example, Feat Food uses machine learning to create fully customized ready-to-eat meals, allowing customers to specify nutrition profiles down to ingredient quantities, thereby promoting healthier eating habits tailored to unique needs. This personalized approach enhances the customer experience, driving satisfaction and repeat business. Additionally, meal kit providers are integrating mobile apps and AI-driven tools that allow consumers to easily adjust meal selections, delivery times, and subscription options. These technological advancements are improving customer convenience and enabling meal kit companies to offer more flexible, customized solutions.
Expansion into New Markets:
Meal kit services are expanding rapidly into new geographical markets, particularly in regions where the demand for convenient, home-cooked meals is rising. While North America and Europe remain the dominant markets, companies are increasingly focusing on Asia-Pacific, Latin America, and other emerging markets. As urbanization grows and disposable incomes rise, more consumers in these regions are seeking time-saving food solutions like meal kits. By tailoring offerings to local tastes and ingredients, meal kit companies are able to tap into new customer bases and drive further market expansion.
Market Challenges Analysis:
High Operational Costs:
One of the primary challenges faced by meal kit companies is the high operational costs associated with sourcing fresh ingredients, packaging, and logistics. For instance, TasteBox emphasizes sourcing local and seasonal ingredients, which helps maintain high quality and freshness, though it requires careful planning and investment to manage costs effectively. Meal kits require precise portioning of ingredients and timely delivery to ensure freshness, which adds significant operational expenses. Furthermore, the need for sustainable and eco-friendly packaging solutions increases costs, as these materials often come at a premium. These rising costs can reduce profit margins for meal kit providers, especially as the market becomes more competitive and companies are pressured to offer lower prices to attract consumers. As the demand for premium, organic, and locally sourced ingredients grows, the associated costs may continue to climb. Efficient supply chain management and cost-effective packaging solutions are critical for meal kit businesses to maintain profitability and stay competitive in an increasingly price-sensitive market.
Customer Retention and Market Saturation:
As the meal kit market grows, customer retention has become a significant challenge. While the initial appeal of meal kits is strong, many consumers may eventually cancel their subscriptions due to factors such as pricing, lack of variety, or the desire for more personalized meal experiences. Consumer loyalty is difficult to achieve when new meal kit providers continuously enter the market, offering competitive pricing or new meal options. With the market becoming increasingly saturated, companies face intense competition to maintain their customer base. Additionally, consumer preferences are rapidly evolving, requiring meal kit providers to constantly innovate and offer new, exciting meal options. The challenge of retaining customers in such a competitive landscape is compounded by the growing availability of alternative meal solutions, such as prepared meal delivery services and grocery delivery platforms, which can offer similar convenience without the need for subscription models. As a result, companies must focus on enhancing the customer experience, providing exceptional value, and ensuring product differentiation to retain long-term customers.
Market Opportunities:
The meal kit market presents several promising opportunities driven by changing consumer preferences and the growing demand for convenience. As more individuals seek healthier and time-saving meal options, meal kit companies have the opportunity to diversify their offerings to cater to specific dietary needs. The growing popularity of plant-based diets, keto, gluten-free, and other specialized meal plans creates a significant opportunity for meal kit providers to expand their product range and attract health-conscious consumers. By sourcing organic and locally produced ingredients, companies can tap into the increasing consumer demand for clean and sustainable food choices, further differentiating their products in a competitive market. Additionally, the rise of online shopping and home delivery services presents an ongoing opportunity for meal kit services to reach a broader audience, particularly through subscription models that foster customer loyalty.
As meal kit services expand into new geographic regions, particularly in emerging markets, there is ample opportunity for growth. The Asia-Pacific region, with its rapidly urbanizing population and rising disposable income, presents significant untapped potential for meal kit companies. By localizing their offerings to suit regional tastes and preferences, companies can effectively penetrate these markets. Moreover, technological advancements such as AI-driven meal personalization and improved logistics for delivery efficiency provide opportunities to enhance the consumer experience. Meal kit companies can also explore partnerships with health and wellness brands or large grocery chains to expand their market presence and reach new consumer segments, further driving growth and brand awareness.
Market Segmentation Analysis:
By Demographic
The meal kit market segments its consumer base primarily by age, income, and household type. Young professionals, busy families, and millennials are the largest consumers, seeking convenience and time-saving solutions in meal preparation. High-income households tend to favor premium meal kits, including organic or specialty diets, while middle-income households gravitate toward more affordable meal options. Additionally, urban dwellers with limited access to time-intensive cooking methods are a significant target segment due to their busy lifestyles and reliance on home delivery services.
By Psychographic
The meal kit market is also segmented based on psychographic characteristics, such as lifestyle, values, and dietary preferences. Health-conscious consumers, individuals focused on sustainability, and those following specific diets (e.g., plant-based, gluten-free, or keto) form distinct segments. As consumer awareness about nutrition and sustainable living grows, meal kit companies increasingly cater to these needs with customized meal options. This segment values convenience but is also highly motivated by health benefits and environmental responsibility.
By Meal Type
Meal kit services are further categorized by the type of meal offered, including dinner kits, breakfast kits, lunch kits, and snacks. Dinner kits are the most popular segment, offering a range of cuisines and dietary preferences. Providers also introduce options like dessert kits and family-sized meal options to cater to various needs. This segmentation allows companies to target specific meal times and consumer requirements, expanding their customer base while enhancing customer satisfaction with personalized choices.
Segmentations:
- By Demographic:
- Young Professionals
- Millennials
- Families
- Seniors
- High-Income Households
- Middle-Income Households
- Budget-Conscious Consumers
- Single-Person Households
- Couples
- By Psychographic:
- Health-Conscious Consumers
- Eco-Conscious Consumers
- Plant-Based Consumers
- Keto Diet Followers
- Gluten-Free Diet Followers
- Low-Calorie Diet Followers
- Organic Product Seekers
- Convenience Seekers
- Time-Sensitive Consumers
- By Meal Type:
- Dinner Kits
- Lunch Kits
- Breakfast Kits
- Snack Kits
- Family-Sized Meal Kits
- Gourmet Meal Kits
- Specialty Diet Kits (e.g., Vegan, Paleo, Keto)
- By Behavioral:
- Subscription-Based Users
- One-Time Purchase Users
- Frequent Meal Kit Users
- Occasional Meal Kit Users
- Meal Customization Seekers
- Loyalty Program Members
- By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
- North America
Regional Analysis:
North America
North America dominates the global meal kit market, accounting for 40% of the market share in 2024. The United States, in particular, is the leading market due to high consumer demand for convenience and the rapid adoption of meal kit subscription services. In this region, factors such as fast-paced lifestyles, an increasing focus on health and wellness, and the growing popularity of plant-based diets have significantly fueled the demand for meal kits. Additionally, technological advancements in logistics and mobile app services have enhanced the customer experience, making meal kit delivery more efficient and accessible. The subscription-based business model has seen strong success in North America, with major players such as HelloFresh, Blue Apron, and Home Chef establishing a strong foothold. As the market matures, companies are focusing on regional expansion and diversifying their offerings to cater to a broader consumer base, including those seeking specialty and diet-specific meals.
Europe
Europe holds a significant share of the meal kit market, capturing 35% of the global market share in 2024. The region has seen substantial growth, particularly in countries like the United Kingdom, Germany, and France. In Europe, meal kits are gaining traction as consumers increasingly prioritize convenience and healthier eating options. The demand for organic, locally sourced ingredients and diverse meal plans, including vegetarian and vegan options, has contributed to the market's expansion. Additionally, Europe’s well-developed e-commerce infrastructure and growing adoption of home delivery services have enabled meal kit companies to reach a wider audience. The rise of sustainable practices, such as eco-friendly packaging and reducing food waste, is another trend driving growth in this region. Leading meal kit providers such as Marley Spoon and Gousto have become prominent players in Europe, tailoring their services to meet the region’s diverse culinary preferences.
Asia-Pacific
The Asia-Pacific region is the fastest-growing market for meal kits, contributing 15% to the global market share in 2024. The increasing urbanization, rising disposable incomes, and changing dietary habits in countries like China, Japan, and India are driving the expansion of meal kit services. Consumers in these markets are increasingly adopting Westernized food habits, contributing to the growing demand for meal kits. However, there is a strong emphasis on adapting the meal offerings to local tastes and ingredients, which presents both a challenge and an opportunity for meal kit providers. As the region becomes more urbanized, there is a greater demand for time-saving solutions like meal kits, particularly among busy professionals and young families. With the growing middle class and rising health consciousness, the Asia-Pacific market is expected to continue its rapid growth. Companies such as HelloFresh and Blue Apron are exploring regional partnerships and tailoring meal kits to local preferences to capture this emerging demand.
Key Player Analysis:
- Blue Apron
- Hello Fresh
- Plated
- Sun Basket
- Green Chef
- Purple Carrot
- Home Chef
- Abel & Cole
- Riverford
- Blue Apron
- Quitoque
- Kochhaus
- Marley Spoon
- Middagsfrid
Competitive Analysis:
The meal kit market is highly competitive, with several prominent players vying for market share. HelloFresh remains the market leader, dominating with a substantial global presence and a diverse range of meal options catering to various dietary preferences. Blue Apron is another major player, known for its premium offerings and strong brand recognition in North America. Home Chef, which emphasizes customization and flexibility, has gained a strong foothold by offering a wider variety of meal plans. Green Chef appeals to health-conscious consumers with organic and keto-friendly meals. Emerging players like Gobble and Factor focus on delivering gourmet or ready-to-eat meals, targeting consumers seeking convenience without compromising on quality. Competition is further intensified by the increasing number of new entrants offering subscription-based services with localized offerings, making differentiation and innovation critical for long-term success. The focus on customer retention, sustainability, and meal personalization is key for maintaining a competitive edge.
Recent Developments:
- In April 2024, HelloFresh launched Ready-to-Eat meal service Factor in Sweden and Denmark as part of its global multi-tier brand strategy.
- In February 2025, Home Chef partnered with Ayesha Curry to offer exclusive recipes featuring bold flavors in various meal kit formats.
- In April 2023, Green Chef partnered with One Tree Planted to plant a tree for every new meal kit box sold during Earth Month, emphasizing sustainability with new menu items featuring sustainably sourced seafood, organic proteins, and upcycled ingredients.
Market Concentration & Characteristics:
The meal kit market is moderately concentrated, with a few dominant players such as HelloFresh, Blue Apron, and Home Chef commanding a significant share of the global market. These leading companies benefit from strong brand recognition, established customer bases, and extensive distribution networks. Despite this concentration, the market is characterized by a high degree of competition, driven by both established companies and emerging players offering innovative solutions and diverse meal options. Companies are focusing on product differentiation through specialized diets, such as plant-based, keto, and gluten-free options, to cater to evolving consumer preferences. Additionally, subscription-based models have become a prominent feature, encouraging customer loyalty. The market is also increasingly driven by consumer demand for convenience, sustainability, and personalized meal experiences. As a result, meal kit providers are investing heavily in technological advancements, such as mobile apps, AI-driven meal recommendations, and efficient delivery systems to stay competitive.
Report Coverage:
The research report offers an in-depth analysis based on Demographic, Psychographic, Meal Type, Behavioral and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Companies are targeting regions like Asia-Pacific and Latin America, where urbanization and rising disposable incomes are increasing demand for convenient meal solutions.
- The adoption of AI and machine learning is enhancing personalized meal recommendations, improving customer satisfaction and retention.
- Meal kit providers are implementing eco-friendly packaging and sourcing practices to meet growing consumer demand for environmentally responsible products.
- There's a noticeable shift towards offering a wider variety of meal types, including vegan, keto, and gluten-free options, to cater to diverse dietary preferences.
- Companies are introducing more flexible subscription plans, allowing customers to customize delivery frequencies and meal selections to better fit their lifestyles.
- Strategic alliances with grocery chains and celebrity chefs are expanding market reach and enhancing brand credibility.
- The demand for ready-to-eat meal kits is increasing, driven by consumers' desire for convenience and time-saving solutions.
- There's a growing emphasis on nutritionally balanced meals, with meal kits offering portion-controlled and calorie-conscious options.
- Investment in user-friendly mobile applications and efficient delivery systems is improving the overall customer experience.
- The industry is witnessing mergers and acquisitions, leading to a more consolidated market with stronger, more resourceful players.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Convenience-Driven Lifestyles
Busy urban consumers increasingly seek meal solutions that save time on planning, shopping, and preparation, making meal kits an attractive option for home-cooked meals with minimal effort.
Health and Dietary Awareness
Rising consumer focus on health, wellness, and specific dietary needs - such as plant-based, gluten-free, and low-calorie diets - drives demand for specialized meal kits that cater to these preferences.
Subscription Model Adoption
The popularity of flexible subscription-based services ensures recurring revenue for providers and appeals to consumers seeking hassle-free, customizable meal planning and delivery.
Technological and Packaging Innovations
Advancements in eco-friendly packaging, ingredient sourcing, and personalized meal recommendations enhance customer experience, support sustainability, and differentiate brands in a competitive market.
Regional Expansion and Localization
Meal kit providers are expanding into new markets, especially in Asia-Pacific and Latin America, and tailoring offerings to local tastes and preferences, unlocking new growth opportunities.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size of the Meal Kit Market?
What is the projected market size by 2032?
Which region holds the largest market share?
What trends are driving the Meal Kit Market's expansion in the Asia Pacific region?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Meal Type
- 1.2.1 Dinner Kits
- 1.2.2 Lunch Kits
- 1.2.3 Breakfast Kits
- 1.2.4 Snack Kits
- 1.2.5 Family-Sized Meal Kits
- 1.3 By Behavioral
- 1.3.1 Subscription-Based Users
- 1.3.2 One-Time Purchase Users
- 1.3.3 Frequent Meal Kit Users
- 1.3.4 Meal Customization Seekers
- 1.4 By Demographic
- 1.4.1 Young Professionals
- 1.4.2 Millennials
- 1.4.3 Families
- 1.4.4 Seniors
- 1.4.5 Single-Person Households
- 1.5 By Psychographic
- 1.5.1 Health-Conscious Consumers
- 1.5.2 Eco-Conscious Consumers
- 1.5.3 Plant-Based Diet Followers
- 1.5.4 Keto Diet Followers
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 15,981.25 million → 2032: USD 18,432.87 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Meal Kit Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Meal Kit Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Meal Kit Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Meal Kit Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Meal Kit Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Meal Kit Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Meal Kit Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Meal Kit Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 15,981.25 million → 2032: USD 18,432.87 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Meal Kit Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Meal Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Dinner Kits
- 12.3.7.2 Lunch Kits
- 12.3.7.3 Breakfast Kits
- 12.3.7.4 Snack Kits
- 12.3.7.5 Family-Sized Meal Kits
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Behavioral - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Subscription-Based Users
- 12.4.7.2 One-Time Purchase Users
- 12.4.7.3 Frequent Meal Kit Users
- 12.4.7.4 Meal Customization Seekers
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Demographic - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Young Professionals
- 12.5.7.2 Millennials
- 12.5.7.3 Families
- 12.5.7.4 Seniors
- 12.5.7.5 Single-Person Households
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Psychographic - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Health-Conscious Consumers
- 12.6.7.2 Eco-Conscious Consumers
- 12.6.7.3 Plant-Based Diet Followers
- 12.6.7.4 Keto Diet Followers
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Meal Kit Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Meal Kit Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Meal Kit Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 HelloFresh
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Blue Apron
- 17.4 Home Chef
- 17.5 Sun Basket
- 17.6 Green Chef
- 17.7 Marley Spoon
- 17.8 Gousto
- 17.9 Purple Carrot
- 17.10 Abel & Cole
- 17.11 Quitoque
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

