
Market Overview
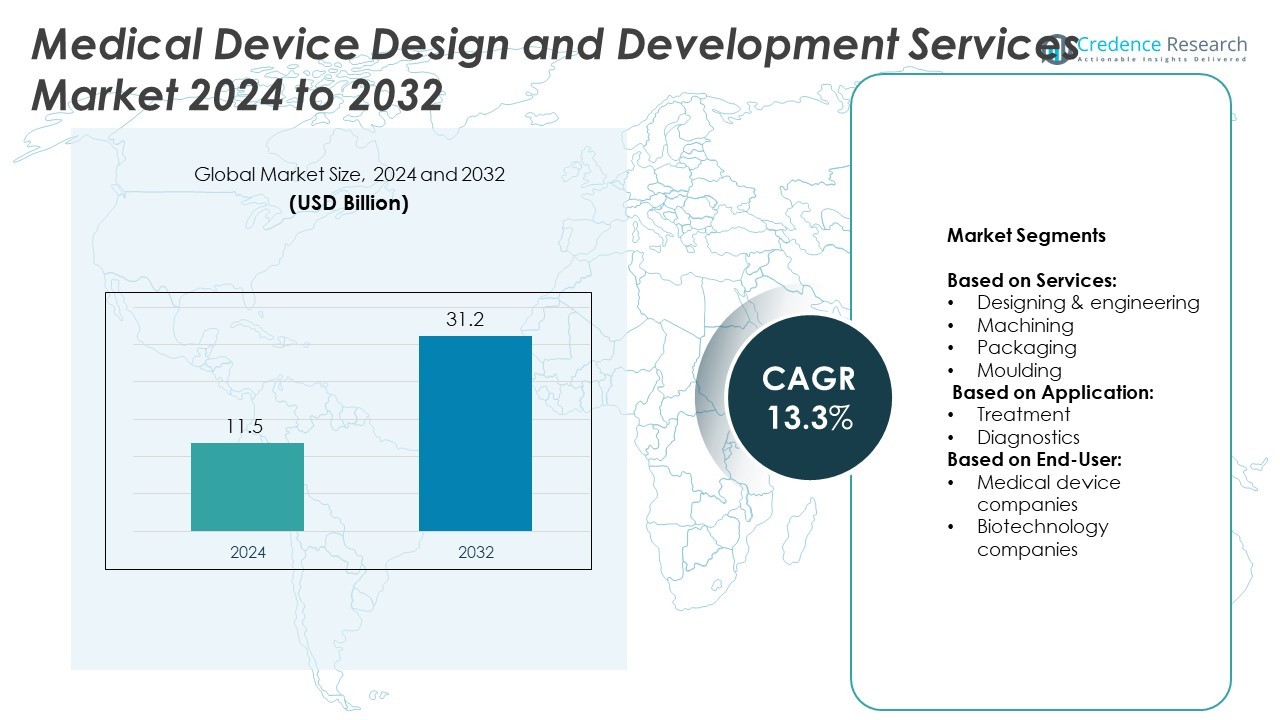
Medical Device Design and Development Services market size was valued at USD 11.5 billion in 2024 and is anticipated to reach USD 31.2 billion by 2032, at a CAGR of 13.3% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Medical Device Design and Development Services Market Size 2024 | USD 11.5 Billion |
| Medical Device Design and Development Services Market, CAGR | 13.3% |
| Medical Device Design and Development Services Market Size 2032 | USD 31.2 Billion |
The Medical Device Design and Development Services market is driven by rising demand for advanced, user-centric devices, growing regulatory complexity, and increased outsourcing by OEMs and startups. Companies seek faster time-to-market, cost efficiency, and compliance support, fueling service provider demand. Key trends include the adoption of digital engineering tools, human-centered design, and eco-friendly product strategies. Wearable technologies and personalized healthcare devices also boost innovation, making full-cycle design services a critical part of modern medtech development.
North America leads the Medical Device Design and Development Services market due to strong healthcare infrastructure and high R&D activity. Europe follows with strict regulatory standards and growing demand for quality-compliant devices. Asia-Pacific shows rapid growth driven by manufacturing expansion and rising healthcare investments. Latin America and the Middle East & Africa show steady potential through local development and regional partnerships. Key players active across these regions include Jabil, Integer Holdings Corporation, Cambridge Design Partnership, and Celestica.
Market Insights
- The Medical Device Design and Development Services market was valued at USD 11.5 billion in 2024 and is projected to reach USD 31.2 billion by 2032, growing at a CAGR of 13.3%.
- Demand is rising due to the push for advanced, patient-focused devices and the need for regulatory compliance support.
- Key trends include adoption of digital simulation tools, sustainability in design, and development of wearable and connected medical technologies.
- Market competition is shaped by full-service providers offering rapid prototyping, regulatory expertise, and scalable production solutions.
- Challenges include navigating complex global regulatory environments and the high cost of design services for startups and smaller firms.
- North America leads in innovation and infrastructure, while Europe emphasizes quality compliance; Asia-Pacific grows fast through local production and healthcare expansion.
- Players like Jabil, Celestica, Cambridge Design Partnership, and Integer Holdings strengthen the market with integrated design and development capabilities.
Market Drivers
Rising Demand for Advanced Medical Technologies and Devices
The growing need for innovative diagnostic and therapeutic devices drives demand for design and development services. Healthcare systems are adopting minimally invasive tools, wearables, and AI-integrated systems to enhance patient outcomes. Companies seek expert partners to help speed up product development and reduce risk. This shift benefits service providers offering design, prototyping, and engineering support. The Medical Device Design and Development Services market gains traction from this strong focus on tech-driven healthcare solutions. It supports product pipelines from ideation to market entry. This trend is expected to sustain growth across all medical device categories.
- For instance, Flex, a global manufacturing and technology partner, has collaborated with numerous health and medical companies to help manufacture over 25 connected health devices. These include biosensors and drug-delivery wearables, which are sometimes integrated with mobile telemetry apps developed by their clients.
Stringent Regulatory Compliance and Quality Requirements
Medical device manufacturers face complex regulations across global markets. Regulatory agencies such as the FDA and EMA demand high levels of documentation, safety testing, and validation. These compliance needs push companies to outsource services to experts in regulatory science and product testing. Service providers help ensure faster approval timelines and reduce costly redesigns. The Medical Device Design and Development Services market benefits from this push for quality and traceability. It positions service firms as strategic partners rather than just technical vendors. Their role is critical in meeting evolving global standards.
- For instance, Carbon has developed certified resins like Medical Polyurethane 100 (MPU 100) for use in 3D-printed medical devices. This resin has been tested for biocompatibility and is durable, allowing it to withstand sterilization using methods such as ethylene oxide, e-beam, and gamma irradiation.
Increasing Outsourcing by OEMs and Startups Alike
Original equipment manufacturers and medtech startups increasingly rely on external partners to handle design and development phases. Startups often lack in-house expertise, while large OEMs seek to reduce internal R&D costs. This dynamic drives consistent demand for full-cycle development solutions including industrial design, prototyping, and usability engineering. The Medical Device Design and Development Services market expands as firms specialize in scalable, efficient support models. It creates a flexible and cost-effective way for device developers to bring innovations to market. Growth in startup funding and venture capital also supports this outsourcing trend.
Growing Importance of User-Centered and Value-Based Design
Healthcare providers emphasize improved usability and clinical value in selecting devices. Designers now focus on ergonomics, safety, and human factors engineering. Service firms help integrate these elements from the earliest design stages. This shift reflects a broader healthcare move toward value-based care. The Medical Device Design and Development Services market aligns with user-centered strategies to improve both outcomes and satisfaction. It ensures devices meet real-world clinical needs while reducing user error. This design focus adds long-term value to medical device innovations
Market Trends
Adoption of Digital Engineering and Simulation Tools Across Development Phases
Companies are integrating advanced software tools such as CAD, CFD, and FEA to improve product design. These digital solutions help visualize and test performance before physical prototypes are built. Simulation allows teams to detect design flaws early, cutting time and development costs. The Medical Device Design and Development Services market benefits from clients demanding precision and reduced failure rates. It supports virtual prototyping, reducing reliance on physical iteration. Digital tools also support design validation under regulatory standards. This trend is shaping how new devices reach market readiness.
- For instance, Modine used Simcenter STAR-CCM+ to cut CAD cleanup time from three days down to one is accurate and supported by a Siemens case study.
Rising Focus on Human-Centered and Inclusive Design
Medical devices now must serve diverse populations with different needs and abilities. Service providers are aligning their design strategies to meet patient-centric goals. Usability engineering, inclusive features, and feedback-based iterations play a larger role. The Medical Device Design and Development Services market advances by focusing on intuitive use and patient safety. It meets growing expectations from clinicians, patients, and caregivers. Firms specialize in research-driven design that supports both function and accessibility. This trend helps reduce usage errors and improve patient outcomes.
- For instance, RQM+ supported over 1,000 MedTech clients. RQM+ is a partner to 19 of the top 20 medical device companies.
Shift Toward Eco-Friendly and Sustainable Design Practices
Medical device companies face pressure to lower environmental impact and adopt greener manufacturing methods. Designers now consider materials, recyclability, and energy efficiency during early product planning. Regulations and hospital purchasing policies increasingly favor sustainable options. The Medical Device Design and Development Services market responds by offering services aligned with life cycle sustainability goals. It helps clients choose bio-compatible, non-toxic, and low-carbon materials. Sustainability adds value across both compliance and brand positioning. Service firms that integrate eco-friendly strategies gain a competitive edge.
Expansion of Wearables and Home-Based Monitoring Devices
Healthcare delivery is shifting toward outpatient and home care settings. This drives demand for wearable and remote monitoring devices that support real-time data collection. Service providers help design compact, durable, and connected solutions. The Medical Device Design and Development Services market adapts to this shift by focusing on wireless integration and mobile compatibility. It supports firms developing devices used outside traditional clinical settings. Market demand is high for devices that ensure comfort, accuracy, and battery life. This trend is reshaping product specifications and user experience priorities.
Market Challenges Analysis
Complex Regulatory Landscape Slows Development and Increases Risk
Navigating diverse global regulatory frameworks remains one of the toughest challenges for device developers. Each region enforces its own requirements for design validation, clinical trials, and documentation. Delays in approvals or non-compliance can lead to costly redesigns or market rejection. The Medical Device Design and Development Services market must adapt to changing guidelines from authorities like the FDA, EMA, and MDR. It requires continuous expertise in global standards and timely updates to design protocols. Service providers face growing pressure to ensure documentation and testing meet every jurisdiction's criteria. This complexity increases timelines and resource needs during development.
High Cost and Resource Intensity Limits Entry for Smaller Players
Medical device design demands skilled professionals, expensive tools, and advanced testing facilities. Smaller companies and startups often struggle to afford full-scale development services. This limits innovation from new entrants who lack access to capital or technical teams. The Medical Device Design and Development Services market faces gaps in service affordability and customization. It must balance cost with quality to remain accessible to all segments of the industry. High R&D costs also impact pricing models and client retention. These challenges may slow growth if not addressed through scalable and flexible service models.
Market Opportunities
Growing Demand for Personalized and Connected Healthcare Devices
The rise of personalized medicine and remote care creates new opportunities in device design. Patients expect tools that match individual health needs and integrate with mobile platforms. Service providers can help develop wearable, IoT-enabled, and data-driven devices that support real-time monitoring. The Medical Device Design and Development Services market benefits by offering design capabilities tailored to connected and custom-fit products. It enables clients to bring differentiated solutions to market that improve patient engagement. Demand grows for designs that combine clinical accuracy with ease of use. This shift encourages innovation across diagnostics, therapy, and rehabilitation tools.
Expansion of Healthcare Access in Emerging Markets
Emerging economies are investing in healthcare infrastructure and expanding medical access to underserved populations. These regions seek cost-effective, durable, and user-friendly devices suited to local needs. Design service providers can support companies entering these markets by adapting products to meet regional constraints. The Medical Device Design and Development Services market sees growth through localization, frugal innovation, and support for scalable production. It allows global manufacturers to customize solutions for varied clinical settings. Opportunities arise from government-backed health programs and rising private sector involvement. These trends open new channels for growth in both design complexity and volume.
Market Segmentation Analysis:
By Services:
Designing and engineering hold the leading share due to high demand for product innovation. Companies rely on external partners for concept development, technical drawings, prototyping, and validation. It improves device performance, usability, and compliance from early stages. The Medical Device Design and Development Services market benefits from growing complexity in medical technology, which requires expert-led planning and design. Machining also contributes significantly by supporting precision manufacturing for surgical instruments and implants. Moulding and packaging services remain essential for delivering functional and regulatory-compliant products ready for distribution.
- For instance, in 2024, Phillips-Medisize helped its biopharma customers develop over 441 million lifesaving and life-enhancing drug delivery devices.
By Application:
Treatment-related devices dominate the market due to rising global disease burdens. Devices such as surgical systems, infusion pumps, and therapeutic implants require consistent design support and safety validation. The Medical Device Design and Development Services market meets this demand by offering expertise in function-specific engineering and testing. Diagnostics also holds a strong position as providers develop imaging tools, sensors, and rapid diagnostic kits. Growth in point-of-care testing and personalized health monitoring fuels development across this application segment.
- In November 2022, Donatella announced it had opened a new 2,600-square-foot ISO 7 clean-room. This expansion boosted its capacity to assemble Class I, II, and III medical devices and added to its high-volume production capabilities.
By End-User:
Medical device companies form the core customer base due to their broad product pipelines and regulatory exposure. These firms seek outsourced support to reduce R&D timelines and ensure quality control. The Medical Device Design and Development Services market aligns well with their need for integrated, full-cycle solutions. Biotechnology companies show increasing engagement as they expand into diagnostic platforms and combination products. Their reliance on precision design and compact formats creates opportunity for service providers offering advanced design, prototyping, and usability studies.
Segments:
Based on Services:
- Designing & engineering
- Machining
- Packaging
- Moulding
Based on Application:
- Treatment
- Diagnostics
Based on End-User:
- Medical device companies
- Biotechnology companies
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America
North America holds the highest share in the Medical Device Design and Development Services market at 39.4%. The region benefits from a strong presence of leading medical device companies, advanced healthcare infrastructure, and a favorable regulatory framework. High R&D investment and access to a skilled engineering workforce strengthen its market position. Companies in the United States and Canada actively outsource design services to improve efficiency and reduce product launch times. FDA guidance encourages early involvement of design control processes, which supports service provider demand. The region continues to lead in innovative product development, especially in digital health and wearable medical devices. Robust collaboration between contract design firms and OEMs also supports steady growth.
Europe
Europe accounts for 26.8% of the global market share, driven by strict regulatory standards and strong demand for quality-compliant devices. The region’s focus on product safety and risk management supports demand for expert-led design services. Countries such as Germany, France, and the United Kingdom have large medtech sectors that rely on outsourced partners. MDR (Medical Device Regulation) implementation has intensified demand for design documentation and usability validation. The Medical Device Design and Development Services market in Europe benefits from companies aiming to meet high clinical and safety benchmarks. Collaborative R&D networks and public-private partnerships continue to support service providers. Growing interest in sustainable design also shapes demand across European markets.
Asia-Pacific
Asia-Pacific holds a market share of 21.3%, with strong growth potential due to expanding manufacturing capacity and rising healthcare needs. Countries like China, Japan, India, and South Korea are investing in medtech innovation and digital healthcare. Domestic firms and global players are increasing design outsourcing to reduce cost and accelerate product localization. The Medical Device Design and Development Services market in Asia-Pacific gains support from government initiatives, startup growth, and an expanding clinical trial base. Japan maintains a leadership role in high-tech diagnostics, while India offers cost-effective development hubs. Regulatory modernization across the region enhances service demand for compliance-oriented design.
Latin America
Latin America represents 7.2% of the global market, supported by gradual improvements in healthcare infrastructure and medtech investments. Brazil and Mexico lead regional development, with local firms and subsidiaries of global players investing in product customization. The Medical Device Design and Development Services market benefits from increasing interest in portable, low-cost medical solutions suited to rural populations. Challenges remain in regulatory variation and cost constraints, but the long-term outlook stays positive. Local partnerships and regional trade agreements may further accelerate adoption of outsourced design models.
Middle East and Africa
The Middle East and Africa region holds a share of 5.3%, reflecting early-stage growth and infrastructure expansion. Countries such as the UAE, Saudi Arabia, and South Africa show rising demand for diagnostic and home-based devices. Local and international firms are seeking support to adapt products to regional needs and regulatory expectations. The Medical Device Design and Development Services market here remains small but promising, with increased government support for healthcare access and medtech innovation. Public-private initiatives and local manufacturing development may drive future market gains.
Key Player Analysis
- StarFish Product Engineering
- Cambridge Design Partnership
- Integer Holdings Corporation
- Jabil
- Donatelle
- Sanmina Corporation
- Veranex
- Creation Technologies
- Planet Innovation
- Cirtec Medical
- Nordson Corporation
- Quest Global
- Celestica
- Plexus Corporation
- Flex
Competitive Analysis
Key players in the Medical Device Design and Development Services market include Celestica, Cambridge Design Partnership, Creation Technologies, Cirtec Medical, Donatelle, Flex, Integer Holdings Corporation, Jabil, Nordson Corporation, Planet Innovation, Plexus Corporation, Quest Global, Sanmina Corporation, StarFish Product Engineering, and Veranex. These companies compete by offering integrated solutions that span the full product lifecycle-from concept and prototyping to testing, regulatory support, and manufacturing. Each firm invests in advanced engineering capabilities, ISO-certified facilities, and cross-functional teams to meet client-specific needs. Strategic differentiation is achieved through specialization in complex device categories such as implants, drug delivery systems, and wearable monitors. Global players focus on scale and geographic reach, while niche firms target innovation and speed-to-market. Competitive advantage also comes from regulatory expertise and track records in FDA and CE approvals. Long-term partnerships with OEMs help ensure repeat contracts and stable revenue. Leading service providers maintain strong investment in digital engineering tools and sustainability practices. The market remains fragmented, with both large contract manufacturers and innovation-focused design studios coexisting. Successful players balance cost-efficiency, design precision, and compliance support, positioning themselves as strategic partners in a fast-evolving medtech landscape.
Recent Developments
- In July 2025, Celestica the company highlighted its Value Analysis/Value Engineering (VAVE) approach to help customers design innovative medical products more swiftly and cost‑effectively.
- In May 2025, Creation Technologies the company celebrated a ribbon-cutting of its expanded Denver Product Realization Center.
- In April 2025, Cirtec announced a Costa Rica expansion, more than doubling its manufacturing footprint and boosting global production for neuromodulation and structural heart device markets
Report Coverage
The research report offers an in-depth analysis based on Services, Application, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Growth will follow demand for AI‑integrated and remote monitoring medical devices.
- Service providers will adopt digital twins and cloud-based simulation tools to accelerate design cycles.
- Regulators will drive stronger collaboration with providers to streamline compliance and approval processes.
- Market entry will increase for firms offering modular and scalable design platforms.
- Demand will rise for eco-conscious design methods using biodegradable and recyclable materials.
- Providers will expand into personalized device development through patient-specific modeling.
- Cross-industry partnerships will grow, combining expertise from wearable tech and medtech sectors.
- Providers will invest in near-patient manufacturing to support rapid deployment and localization.
- Adoption of remote usability testing and virtual validation will improve design efficiency.
- Market competition will shift toward firms with integrated services-from concept through post‑market surveillance.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Demand for Advanced, User-Centric Devices
Healthcare providers and patients increasingly expect devices that are intuitive, ergonomic, and tailored to specific clinical needs, driving companies to seek expert design and development services to differentiate their products and improve outcomes.
Growing Regulatory Complexity
Stringent and evolving global regulations require specialized expertise in compliance, documentation, and validation, prompting manufacturers to outsource design and development to service providers with proven regulatory track records.
Increased Outsourcing by OEMs and Startups
Both established manufacturers and startups are turning to external partners to accelerate time-to-market, reduce R&D costs, and access specialized skills, fueling demand for comprehensive design and development services.
Adoption of Digital Engineering and Simulation Tools
The integration of advanced digital tools such as CAD, simulation, and virtual prototyping enables faster, more precise product development, encouraging companies to leverage service providers with these capabilities.
Expansion of Wearables and Personalized Healthcare Devices
The shift toward remote monitoring, wearable technologies, and personalized medicine is creating new opportunities for service providers to design innovative, connected, and patient-specific medical devices.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Medical Device Design and Development Services market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Medical Device Design and Development Services Market projected to grow between 2025 and 2032?
Which Medical Device Design and Development Services market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Medical Device Design and Development Services market?
Who are the leading companies in the Medical Device Design and Development Services Market?
Which region commanded the largest share of the Medical Device Design and Development Services market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-User
- 1.2.1 Medical device companies
- 1.2.2 Biotechnology companies
- 1.3 By Services
- 1.3.1 Designing & engineering
- 1.3.2 Machining
- 1.3.3 Packaging
- 1.3.4 Moulding
- 1.4 By Application
- 1.4.1 Treatment
- 1.4.2 Diagnostics
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 11.5 billion → 2032: USD 31.2 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Medical Device Design and Development Services Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Medical Device Design and Development Services Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Medical Device Design and Development Services Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Medical Device Design and Development Services Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Medical Device Design and Development Services Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Medical Device Design and Development Services Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Medical Device Design and Development Services Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Medical Device Design and Development Services Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 11.5 billion → 2032: USD 31.2 billion)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Medical Device Design and Development Services Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Base-Year Market Share, 2024
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Medical device companies
- 12.3.6.2 Biotechnology companies
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Services - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Base-Year Market Share, 2024
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Designing & engineering
- 12.4.6.2 Machining
- 12.4.6.3 Packaging
- 12.4.6.4 Moulding
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Base-Year Market Share, 2024
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Treatment
- 12.5.6.2 Diagnostics
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Medical Device Design and Development Services End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Medical Device Design and Development Services Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Medical Device Design and Development Services Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Energy Efficiency and Resource Management
- 15.7 Sustainability, Recycling and Circularity
- 15.8 Technology Roadmap, 2024-2032
- 15.9 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Medical Device Design and Development Services Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Jabil
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 Integer Holdings Corporation
- 18.4 Cambridge Design Partnership
- 18.5 Celestica
- 18.6 Flex
- 18.7 Sanmina Corporation
- 18.8 Plexus Corporation
- 18.9 Cirtec Medical
- 18.10 Donatelle
- 18.11 StarFish Product Engineering
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

