
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
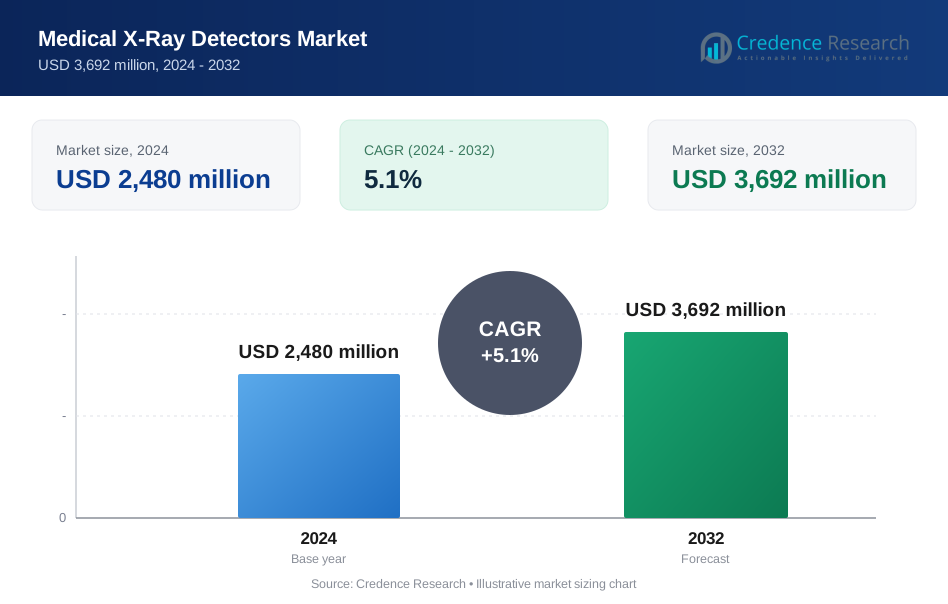
| Medical X-Ray Detectors Market Size 2024 | USD 2480 million |
| Medical X-Ray Detectors Market , CAGR | 5.1% |
| Medical X-Ray Detectors Market Size 2032 | USD 3692.09 million |
Market Overview:
The Medical X-Ray Detectors Market is projected to grow from USD 2480 million in 2024 to an estimated USD 3692.09 million by 2032, with a compound annual growth rate (CAGR) of 5.1% from 2024 to 2032.
Key drivers of the Medical X-Ray Detectors Market include the increasing prevalence of age-related diseases, such as osteoporosis and arthritis, which demand advanced diagnostic imaging for effective management. Additionally, a growing geriatric population globally is expected to fuel demand, as older populations typically require more frequent imaging services. Technological advancements in X-ray detector materials, such as the introduction of flat-panel detectors and complementary metal-oxide semiconductors (CMOS), also drive market growth by providing higher image quality and faster processing times. Moreover, the rising adoption of portable and wireless X-ray detectors enables better point-of-care diagnostics, particularly in remote or underserved areas, where access to high-quality medical imaging is often limited. Supportive government initiatives and increased healthcare spending further encourage healthcare facilities to upgrade their radiology departments with advanced X-ray detectors, driving market expansion.
Regionally, North America dominates the Medical X-Ray Detectors Market, supported by well-established healthcare infrastructure, high healthcare expenditure, and strong demand for advanced imaging technologies. The United States, in particular, leads the market due to its large base of healthcare facilities and increased focus on early disease diagnosis. Europe holds a significant market share, driven by a rising aging population and government initiatives promoting healthcare modernization. Meanwhile, the Asia-Pacific region is anticipated to witness the fastest growth during the forecast period, propelled by rising healthcare investments in countries like China and India, growing awareness regarding early diagnostics, and an increasing number of imaging centers. Additionally, expanding medical tourism in the Asia-Pacific region further contributes to market demand for X-ray detectors, as many patients seek high-quality, affordable healthcare services in this region.
Market Drivers:
Rising Prevalence of Chronic Diseases:
The increasing incidence of chronic diseases, including cardiovascular disorders, cancer, and respiratory illnesses, significantly drives the demand for medical X-ray detectors. As these conditions often require routine imaging for monitoring and diagnosis, healthcare providers increasingly rely on advanced diagnostic tools. X-ray detectors play a critical role in enabling timely and accurate diagnoses, thereby supporting better patient outcomes. This demand is further propelled by a globally aging population that is more susceptible to chronic conditions and requires frequent medical imaging. Consequently, the rising prevalence of these diseases drives substantial demand in the medical X-ray detectors market.
Technological Advancements in Detector Materials:
Recent advancements in X-ray detector technologies, such as flat-panel detectors and complementary metal-oxide semiconductors (CMOS), are transforming the landscape of medical imaging. Flat-panel detectors, for example, offer high-resolution images with lower radiation doses, enhancing safety and diagnostic accuracy. Siemens Healthineers has developed advanced flat-panel detectors that provide high-quality imaging with reduced radiation exposure. Their Ysio Max digital radiography system, equipped with flat-panel detectors, has been installed in over 10,000 healthcare facilities worldwide. CMOS detectors provide faster processing speeds, which help healthcare facilities improve workflow efficiency and patient throughput. These advanced detector materials also offer portability and wireless capabilities, making them ideal for point-of-care applications in emergency rooms or remote healthcare settings. The continuous improvement in detector technology not only improves diagnostic quality but also expands the applicability of X-ray imaging, thereby fueling market growth.
Increasing Demand for Digital Imaging Solutions:
The shift from traditional analog imaging systems to digital X-ray systems is another key driver for the medical X-ray detectors market. Digital systems offer several advantages, including higher image quality, lower radiation exposure, and faster image processing, making them more suitable for modern healthcare needs. Additionally, digital X-ray systems integrate seamlessly with hospital information systems, allowing easy storage, access, and sharing of images, which is essential for efficient diagnosis and treatment planning. As a result, healthcare facilities are increasingly investing in upgrading their imaging infrastructure to digital systems, further propelling the adoption of advanced X-ray detectors. The shift towards digitalization in medical imaging is particularly evident in developed regions, where healthcare providers prioritize efficiency and image quality to enhance patient care.
Government Initiatives and Rising Healthcare Expenditure:
Government initiatives aimed at modernizing healthcare infrastructure, along with increasing healthcare expenditure globally, further contribute to the growth of the medical X-ray detectors market. Many governments are investing in healthcare facilities, especially in developing regions, to improve diagnostic and therapeutic capabilities. For instance, the Indian government has increased its healthcare budget to support the adoption of advanced medical technologies, including X-ray detectors. The budget for FY 2024-25 under the National Health Mission (NHM) was increased by approximately ₹4,000 crore, reaching a total of ₹36,000 crore. Financial incentives and subsidies to support healthcare providers in upgrading to advanced imaging technologies help boost market growth. Additionally, as healthcare spending increases, providers have more resources to invest in high-quality imaging equipment, including advanced X-ray detectors. This trend is particularly prevalent in countries like the United States and China, where significant healthcare budgets allow for the adoption of state-of-the-art imaging technologies to support a high standard of patient care.
Market Trends:
Growth in Digital and Wireless X-Ray Detectors:
One of the most notable trends in the medical X-ray detectors market is the rapid adoption of digital and wireless X-ray detectors. These systems offer significant advantages over traditional analog systems, including enhanced image quality, improved workflow efficiency, and reduced radiation exposure for patients. Wireless X-ray detectors provide additional convenience by eliminating the need for wired connections, making them particularly valuable in emergency and mobile healthcare settings. As healthcare facilities increasingly recognize the benefits of wireless and digital X-ray technology, investments in these systems are rising. This shift aligns with broader healthcare digitalization trends, pushing digital and wireless X-ray detectors into the mainstream.
Integration with Artificial Intelligence (AI) and Machine Learning (ML):
AI and ML technologies are increasingly being integrated into X-ray detectors, enhancing the diagnostic process by enabling advanced image analysis. These technologies allow for faster and more accurate detection of abnormalities by assisting radiologists with image interpretation, reducing human error, and improving diagnostic accuracy. AI-enabled X-ray detectors can identify patterns and provide predictive analytics, which are especially useful in early disease detection and decision-making. This integration of AI and ML not only improves diagnostic quality but also supports radiologists in handling high patient volumes, meeting the rising demand for efficient imaging solutions. As AI continues to advance, its role in the X-ray detector market is expected to grow, driving adoption further.
Increasing Adoption of Portable X-Ray Systems:
The demand for portable X-ray systems is on the rise, driven by the need for point-of-care diagnostics and the growing importance of home healthcare. Portable X-ray detectors allow for on-the-spot imaging, making them highly valuable in emergency situations, rural healthcare facilities, and field settings. The compact design and high efficiency of portable X-ray systems make them ideal for mobile applications, enabling healthcare providers to deliver high-quality diagnostics outside of traditional hospital settings. For example, Shimadzu's MobileDaRt Evolution MX8, a compact, maneuverable mobile X-ray system with a wireless flat panel detector, suitable for various clinical environments including operating rooms and intensive care units. This trend has gained further traction with the COVID-19 pandemic, which emphasized the importance of flexible healthcare solutions that can adapt to changing patient needs. As a result, portable X-ray systems are expected to remain in high demand, contributing to market growth.
Focus on Dose Reduction Technologies:
Another prominent trend in the medical X-ray detectors market is the focus on dose reduction technologies. With growing awareness around radiation exposure risks, healthcare providers are increasingly prioritizing patient safety by adopting X-ray systems designed to minimize radiation doses while maintaining high image quality. Advances in detector materials and design have allowed for significant improvements in dose efficiency, enabling healthcare providers to deliver safer diagnostics. For instance, A study by Nesterets et al. revealed that dose reduction factors in the tens of thousands are theoretically possible without loss in image quality, which would have a profound impact on medical and industrial imaging applications. This trend is particularly significant in pediatrics and oncology, where minimizing radiation exposure is critical. The emphasis on dose reduction aligns with regulatory pressures to improve safety standards, pushing manufacturers to innovate and develop detectors that meet these evolving requirements.
Market Restraints and Challenges:
High Costs of Advanced X-Ray Detectors:
One of the primary restraints in the medical X-ray detectors market is the high cost associated with advanced digital and wireless X-ray detectors. These systems, particularly those equipped with the latest technologies such as flat-panel detectors and complementary metal-oxide semiconductors (CMOS), require significant capital investment. Smaller healthcare facilities, especially those in developing regions, may struggle to afford these advanced detectors, limiting their adoption. Additionally, the costs associated with maintenance, software updates, and personnel training can further deter facilities from investing in the latest X-ray technology, particularly if their budgetary constraints are significant.
Stringent Regulatory Standards:
The medical X-ray detectors market is subject to strict regulatory requirements, as these devices are crucial for patient diagnostics and safety. Regulatory bodies, such as the U.S. Food and Drug Administration (FDA) and the European Medicines Agency (EMA), have stringent standards for approval, focusing on radiation safety, diagnostic accuracy, and equipment durability. Meeting these standards often requires rigorous testing, which increases both development time and costs for manufacturers. Furthermore, regulatory updates or changes in safety guidelines can delay product launches, complicating market entry and slowing growth. These regulatory hurdles present a significant challenge for companies seeking to innovate while maintaining compliance.
Limited Skilled Personnel for Advanced Systems:
Another key challenge for the market is the shortage of skilled personnel trained to operate advanced X-ray detector systems. As these systems become increasingly digital and technologically complex, radiology departments require specialized training to maximize efficiency and diagnostic accuracy. In regions where healthcare facilities struggle with staffing shortages, this lack of skilled personnel can limit the adoption of advanced X-ray detectors. The learning curve associated with new technologies also adds to training costs, creating an additional barrier for smaller facilities that may lack the resources for continuous education and training programs.
Market Segmentation Analysis:
The Medical X-Ray Detectors Market is segmented by product type, panel size, modality, module type, and end-user, each playing a distinct role in driving growth.
By product, the market includes indirect flat-panel detectors, direct flat-panel detectors, and computed radiography (CR) detectors. Indirect flat-panel detectors currently dominate due to their widespread usage and cost-effectiveness, though direct flat-panel detectors are gaining traction for their improved image quality and lower radiation dose.
By Panel size segmentation divides the market into large-area and small-area flat-panel detectors. Large-area detectors are preferred in settings requiring comprehensive imaging, such as hospitals, while small-area detectors are popular for specific diagnostic needs.
By modality, the market comprises portable and fixed detectors. Portable detectors are experiencing high demand, particularly in point-of-care and emergency scenarios, given their mobility and ease of use.
By module type, the market is categorized into digital X-ray systems and retrofit X-ray systems. Digital X-ray systems lead due to their efficiency and integration capabilities with digital health records, while retrofit systems are adopted in facilities looking to upgrade existing analog equipment without a complete system overhaul.
By end-user segment includes hospitals and clinic and diagnostic centers, with hospitals holding the largest share due to high patient volumes and comprehensive imaging needs. Diagnostic centers, however, are expanding as they offer specialized imaging services and adopt advanced technology for precise diagnostics.
Segmentation:
By Product:
- Indirect flat-panel detectors,
- Direct flat-panel detectors
- Computed radiography (CR) detectors.
By Panel Size:
- Large-area flat-panel detectors
- Small-area flat-panel detectors.
By Modality:
- Portable detectors
- Fixed detectors.
By Module Type:
- Digital X-ray systems
- Retrofit X-ray systems.
By End User:
- Hospitals and clinic
- Diagnostic centers.
By Regional
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds the largest share of the global medical X-ray detectors market, driven by advanced healthcare infrastructure, high healthcare expenditure, and strong demand for cutting-edge diagnostic technology. The United States, with its well-established hospitals and diagnostic centers, dominates the region’s market share. Additionally, the presence of key industry players and a high adoption rate of digital and portable X-ray systems contribute to market growth. In 2023, North America accounted for approximately 35% of the global market share. Supportive regulatory frameworks and substantial government investments in healthcare modernization further fuel demand, positioning North America as a leader in adopting new X-ray detector technologies.
Europe
Europe is the second-largest market for medical X-ray detectors, with an estimated 30% share of the global market. The region's market is primarily driven by a growing elderly population, which requires frequent imaging for managing age-related health conditions, and government initiatives that encourage the adoption of digital imaging technologies. Countries like Germany, France, and the UK are the main contributors, as they continuously invest in healthcare advancements and infrastructure upgrades. The EU's strict regulatory standards for medical imaging devices have also led to increased demand for safer, low-radiation detectors. Rising healthcare spending and the strong focus on early diagnosis are expected to sustain growth in this region.
Asia-Pacific
Asia-Pacific represents the fastest-growing region in the medical X-ray detectors market, holding around 25% of the global share and anticipated to capture an even greater share in the coming years. The market is driven by increasing healthcare investments, the growing burden of chronic diseases, and rising awareness of the benefits of early diagnosis. China and India, with their expanding healthcare infrastructures and large patient populations, are the main drivers of growth in the region. Additionally, medical tourism, particularly in countries like Thailand and Malaysia, is fueling demand for advanced diagnostic imaging solutions. The Asia-Pacific region is also witnessing increasing adoption of digital and portable X-ray systems as governments prioritize healthcare modernization.
Latin America
Latin America holds a smaller share of the medical X-ray detectors market, accounting for approximately 5% of the global market. Growth in this region is driven by expanding healthcare infrastructure and increasing investment in diagnostic imaging. Brazil and Mexico are leading contributors, with both public and private healthcare facilities gradually adopting digital X-ray systems. While challenges such as limited healthcare budgets persist, the region's rising healthcare demand, coupled with supportive government initiatives, offers opportunities for growth.
Middle East and Africa
The Middle East and Africa account for around 5% of the global market share. This region faces challenges such as limited access to healthcare in rural areas and budgetary constraints in some countries. However, demand is rising in affluent regions like the UAE and Saudi Arabia, where governments are investing in healthcare infrastructure. As the focus on healthcare development continues to grow, there is potential for increased adoption of advanced X-ray detector technology in urban centers across the region.
Key Player Analysis:
- Apteryx Imaging Inc. (Canada)
- Canon Inc. (Japan)
- Carestream Health. (US)
- (US)
- FUJIFILM Holdings Corporation (Japan)
- GENERAL ELECTRIC COMPANY (US)
- GMM PFAUDLER. (India)
- Hamamatsu Photonics K.K. (Japan)
- KA Imaging (Canada)
- Koninklijke Philips N.V. (Netherlands)
- Midmark Corporation. (US)
- PLANMECA OY (Finland)
- Shenzhen Mindray Bio-Medical Electronics Co.
- TOSHIBA CORPORATION (Japan)
- Varian Medical Systems
- VATECH (India)
- Villa Sistemi Medicali Spa. (Italy)
- Ziehm Imaging GmbH (Germany)
Competitive Analysis:
The medical X-ray detectors market is highly competitive, with major players focused on technological innovation and expanding their product portfolios. Key companies, including Canon Inc., Agfa-Gevaert Group, FUJIFILM Holdings Corporation, Koninklijke Philips N.V., and Siemens Healthineers, lead the market by offering advanced digital and wireless X-ray detector solutions that meet increasing demands for high-resolution imaging and efficient diagnostic tools. These companies invest heavily in R&D to improve image quality, reduce radiation dose, and integrate AI capabilities, which enhance diagnostic accuracy and streamline workflows. Smaller and regional players also contribute to market competitiveness by providing cost-effective solutions, particularly in developing markets where affordability is crucial. Strategic partnerships, mergers, and acquisitions are common, as companies aim to broaden their geographic reach and strengthen their market presence. With continuous innovation and a strong focus on healthcare modernization, competition in the medical X-ray detectors market is expected to remain intense
Recent Developments:
- In February 2022, KA Imaging Inc. obtained a license to sell its Reveal 35C dual-energy X-ray detector in the Taiwan market, enabling access to this advanced imaging technology in Taiwan.
- In May 2022, EXAMION partnered with Systemhaus GmbH & Co. KG to expand its product offerings. This collaboration highlights both companies' expertise in the healthcare sector and reinforces their commitment to enhancing customer value through a broader product range.
Market Concentration & Characteristics:
The medical X-ray detectors market exhibits moderate to high concentration, with a few dominant players, including Canon Inc., FUJIFILM Holdings Corporation, and Siemens Healthineers, controlling a substantial share. These leading companies drive market innovation, leveraging extensive R&D resources to develop advanced technologies like digital, wireless, and AI-enabled detectors, which set high standards for image quality and diagnostic precision. Despite this concentration, smaller and regional companies also play a role by offering cost-effective solutions tailored to emerging markets, where affordability and accessibility are primary concerns. The market is characterized by rapid technological advancements, regulatory scrutiny, and a strong focus on safety and efficiency. Strategic alliances, partnerships, and mergers are common as companies seek to enhance their product portfolios and geographic reach. Overall, the market’s competitive landscape is shaped by a continuous push toward digitalization, improved patient safety, and streamlined diagnostic workflows.
Report Coverage:
The research report offers an in-depth analysis based on By Product, By Panel Size, By Modality, By Module Type and By End User. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand for digital X-ray detectors will rise as healthcare facilities prioritize high-resolution imaging and workflow efficiency.
- Integration of AI and machine learning into detectors will enhance diagnostic accuracy and streamline radiologist workflows.
- Portable X-ray detectors will experience increased adoption in point-of-care and remote healthcare settings.
- The focus on low-dose technologies will continue to grow, addressing patient safety concerns around radiation exposure.
- Emerging markets in Asia-Pacific, Latin America, and the Middle East will drive significant growth through healthcare infrastructure investments.
- Continuous technological advancements in detector materials, like CMOS, will enhance image quality and speed.
- Retrofitting analog systems to digital detectors will remain popular for cost-effective facility upgrades in developing regions.
- Strategic partnerships and acquisitions will accelerate, allowing companies to expand their geographic and product reach.
- Regulatory requirements for safety and efficacy will intensify, pushing manufacturers to innovate while maintaining compliance.
- Rising prevalence of chronic diseases and aging populations will increase demand for X-ray detectors in diagnostic imaging.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Medical X-Ray Detectors Market?
What are the main drivers of market growth?
Which region holds the largest market share?
What challenges does the Medical X-Ray Detectors Market face?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Medical X-Ray Detectors Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Medical X-Ray Detectors Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 2,480 million → 2032: USD 3,692 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Medical X-Ray Detectors Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Medical X-Ray Detectors Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Medical X-Ray Detectors Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Medical X-Ray Detectors Market Drivers
- 3.3 Medical X-Ray Detectors Market Restraints & Challenges
- 3.4 Medical X-Ray Detectors Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Medical X-Ray Detectors Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Medical X-Ray Detectors Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Medical X-Ray Detectors category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Medical X-Ray Detectors Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Medical X-Ray Detectors Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Medical X-Ray Detectors market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Medical X-Ray Detectors Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Medical X-Ray Detectors Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Medical X-Ray Detectors Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Medical X-Ray Detectors (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Medical X-Ray Detectors Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Medical X-Ray Detectors Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Medical X-Ray Detectors Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Medical X-Ray Detectors Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Medical X-Ray Detectors Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Medical X-Ray Detectors Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Medical X-Ray Detectors Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Medical X-Ray Detectors Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Medical X-Ray Detectors Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
