
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Mexico Powder Metallurgy Market Size 2024 | USD 68.6 million |
| Mexico Powder Metallurgy Market, CAGR | 5.29% |
| Mexico Powder Metallurgy Market Size 2032 | USD 113.25 million |
Market Overview:
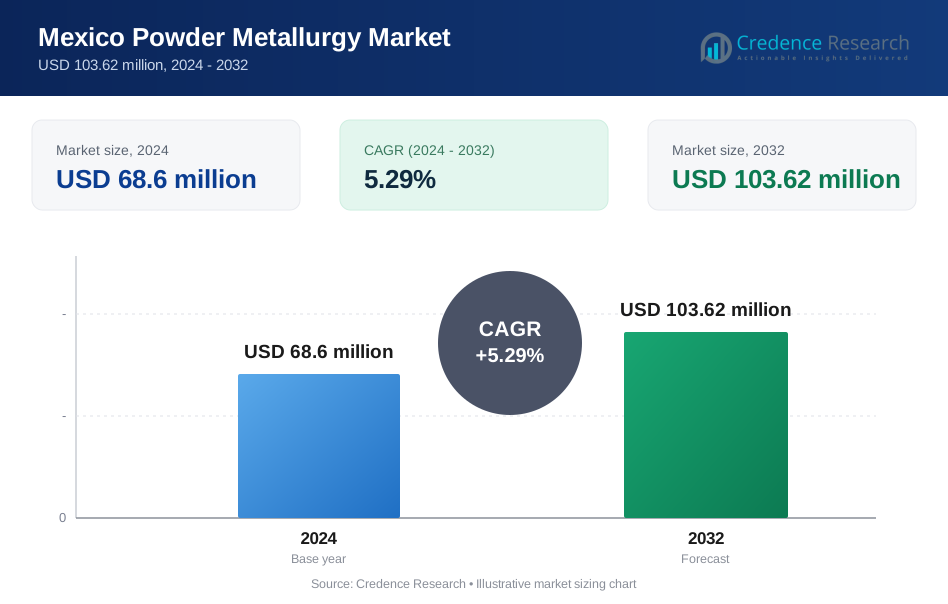
The Mexico Powder Metallurgy Market is projected to grow from USD 68.6 million in 2024 to an estimated USD 103.62 million by 2032, with a compound annual growth rate (CAGR) of 5.29% from 2024 to 2032.
The growth of the powder metallurgy market in Mexico is driven by several key factors. Firstly, the expansion of the automotive industry plays a crucial role. Mexico is a major manufacturing hub for automotive components, with powder metallurgy being a preferred method due to its cost-effectiveness, efficiency, and ability to produce lightweight, durable parts. The demand for sustainable and fuel-efficient vehicles has further accelerated the adoption of this technology. Secondly, technological advancements, particularly in additive manufacturing (3D printing), have significantly enhanced the capabilities of powder metallurgy. These innovations enable the production of complex and precise components, broadening the range of applications and increasing manufacturing efficiency. The aerospace sector also contributes to market growth, as powder metallurgy is essential for producing high-strength, lightweight components, aligning with the industry's performance requirements.
Regionally, Mexico's strategic geographical position and economic agreements have strengthened its role in the global powder metallurgy market. As part of the North American region, Mexico benefits from proximity to the United States and Canada, key markets for powder metallurgy components. The country's competitive manufacturing landscape and access to skilled labor make it an attractive destination for global manufacturers. Moreover, trade agreements like the United States-Mexico-Canada Agreement (USMCA) facilitate seamless trade, enhancing Mexico's export potential. This strategic integration into global supply chains positions Mexico as a vital player in the growth and development of the powder metallurgy sector.
Market Insights:
- The Mexico Powder Metallurgy Market is projected to grow from USD 68.6 million in 2024 to USD 103.62 million by 2032, registering a CAGR of 5.29%.
- The expansion of Mexico’s automotive sector significantly contributes to market growth, with powder metallurgy favored for its efficiency, cost-effectiveness, and ability to produce lightweight, durable components.
- Technological advancements, particularly in additive manufacturing (3D printing), are broadening the application scope by enabling the production of complex and precise components across industries.
- The aerospace industry presents growth opportunities, with increasing demand for high-strength, lightweight components aligning with powder metallurgy’s capabilities.
- Government initiatives to enhance local manufacturing capabilities, attract investments, and simplify regulations are bolstering market expansion.
- Mexico's strategic geographical position and economic agreements, like the USMCA, strengthen its role in the global supply chain, enhancing its export potential.
- Diversification into emerging sectors such as medical devices, electronics, and industrial machinery is mitigating industry risks and ensuring long-term market resilience.
Market Drivers:
Automotive Industry Expansion
Mexico's automotive industry stands as a pivotal force propelling the growth of the powder metallurgy market. The nation's strategic location, coupled with favorable trade agreements, has attracted significant investments from global automotive manufacturers. Powder metallurgy offers cost-effective solutions for producing complex and high-performance automotive components such as gears, bearings, and pistons. The increasing emphasis on lightweight and fuel-efficient vehicles further amplifies the demand for powder metallurgy, as it enables the production of durable yet lightweight parts essential for enhancing vehicle efficiency. For example, investments in electric vehicle (EV) manufacturing are expanding, with plans to build a new EV hub in Sonora, which is already a leader in lithium production for EV batteries.
Technological Advancements in Manufacturing
The advent of advanced manufacturing technologies, notably additive manufacturing (3D printing), has revolutionized the powder metallurgy landscape in Mexico. For instance, ultra-high-temperature sintering, as demonstrated by Höganäs' research, improves material properties like tensile strength and bending fatigue, making it ideal for high-performance applications where materials like Astaloy CrM are used. These technologies facilitate the creation of intricate geometries and customized components that are challenging to produce using traditional methods. The ability to rapidly prototype and manufacture complex parts has opened new avenues for powder metallurgy applications across various industries, including aerospace, medical devices, and consumer electronics. This technological progression not only enhances production efficiency but also reduces material waste, aligning with sustainable manufacturing practices.
Government Initiatives and Economic Policies
The Mexican government's proactive economic policies and initiatives play a crucial role in bolstering the powder metallurgy market. Efforts to position Mexico as a leading global economy by enhancing local manufacturing capabilities and reducing import dependencies have created a conducive environment for industrial growth. Initiatives aimed at attracting investments, simplifying regulatory frameworks, and fostering innovation have stimulated the manufacturing sector, thereby increasing the adoption of powder metallurgy techniques. These policies not only strengthen domestic industries but also enhance Mexico's competitiveness in the global market. For instance, the plan includes immediate tax deductions for new investments and additional deductions for employee training and innovation projects, which help businesses reduce costs and invest in growth.
Diversification into Emerging Sectors
Beyond traditional applications, powder metallurgy in Mexico is experiencing growth through diversification into emerging sectors. For example, the renewable energy sector benefits from powder metallurgy in the production of components for wind turbines and solar panels, where lightweight yet durable materials are essential. Similarly, the medical sector's need for precise and biocompatible implants and instruments aligns with the capabilities of powder metallurgy. The electronics industry also benefits from powder metallurgy in the production of components like magnetic materials and conductive parts. This diversification not only broadens the market scope but also mitigates risks associated with dependency on a single industry, ensuring sustained growth and resilience of the powder metallurgy market in Mexico.
Market Trends:
Integration of Additive Manufacturing Technologies
The Mexican powder metallurgy market is witnessing a significant trend towards the integration of additive manufacturing technologies, particularly 3D printing. This advancement enables the production of complex geometries and customized components with high precision, which were previously challenging to achieve through traditional manufacturing methods. For example, the use of metal powders in 3D printing allows for rapid prototyping and manufacturing of intricate parts, enhancing production efficiency and reducing material waste. Industries such as aerospace, medical devices, and consumer electronics are increasingly adopting these technologies to improve their manufacturing processes. Industries such as aerospace, medical devices, and consumer electronics are increasingly adopting these technologies to enhance production efficiency and reduce material waste. The ability to rapidly prototype and manufacture intricate parts is opening new avenues for powder metallurgy applications in Mexico.
Diversification into Emerging Sectors
Beyond traditional applications, powder metallurgy in Mexico is experiencing growth through diversification into emerging sectors. The aerospace industry, for instance, demands high-strength, lightweight components, which are efficiently produced using powder metallurgy processes. Similarly, the medical sector's need for precise and biocompatible implants and instruments aligns with the capabilities of powder metallurgy. The electronics industry also benefits from powder metallurgy in the production of components like magnetic materials and conductive parts. This diversification not only broadens the market scope but also mitigates risks associated with dependency on a single industry, ensuring sustained growth and resilience of the powder metallurgy market in Mexico.
Emphasis on Sustainable Manufacturing Practices
Sustainability has become a pivotal focus in Mexico's manufacturing landscape, influencing the powder metallurgy market significantly. Powder metallurgy inherently supports sustainable practices by minimizing material waste and enabling the recycling of metal powders. Manufacturers are increasingly adopting these processes to align with environmental regulations and meet the growing consumer demand for eco-friendly products. This emphasis on sustainability is not only enhancing the industry's environmental footprint but also contributing to cost savings and operational efficiency. For instance, the precise control over material usage in powder metallurgy processes reduces waste generation compared to traditional manufacturing methods.
Advancements in Material Development
Continuous advancements in material development are shaping the powder metallurgy market in Mexico. Researchers and manufacturers are focusing on developing new metal powders and alloys with enhanced properties such as increased strength, corrosion resistance, and thermal stability. These innovations are expanding the application possibilities of powder metallurgy across various industries, including automotive, aerospace, and medical sectors. The development of specialized materials is enabling the production of components that meet specific performance requirements, thereby driving the market's growth and competitiveness. For example, advancements in sintering processes allow for the creation of complex structures with improved mechanical properties, further enhancing the versatility of powder metallurgy applications.
Market Challenges Analysis:
High Costs of Metal Powders
The elevated cost of metal powders poses a significant challenge to the growth of the powder metallurgy market in Mexico. Compared to traditional manufacturing materials, metal powders used in additive manufacturing can be substantially more expensive. For instance, stainless steel powder for additive manufacturing can cost around USD 8.0 per square centimeter, which is over 100 times the cost of commercial-grade stainless steel used in conventional manufacturing. This substantial cost disparity can deter manufacturers from adopting powder metallurgy techniques, especially when operating under tight budget constraints.
Quality Consistency and Material Limitations
Ensuring consistent quality in powder metallurgy products remains a pressing concern. Challenges such as achieving uniform density and mechanical properties across components can affect the reliability of the final products. Additionally, the limited availability of materials suitable for powder metallurgy restricts its application scope. While advancements are being made, the current range of materials does not yet match the diversity available in traditional manufacturing processes, thereby limiting the versatility of powder metallurgy.
Environmental and Regulatory Challenges
Environmental compliance presents another layer of challenges for the powder metallurgy industry in Mexico. Instances of improper handling and storage of hazardous materials have raised concerns about environmental contamination and public health risks. For example, authorities discovered 30,000 tons of improperly stored hazardous materials at a plant in Monterrey, leading to regulatory actions and increased scrutiny of industry practices. Such incidents highlight the need for stringent adherence to environmental regulations to prevent potential ecological and health hazards.
Technological and Workforce Adaptation
The rapid evolution of manufacturing technologies necessitates continuous adaptation within the powder metallurgy sector. Challenges include integrating new technologies, such as additive manufacturing, and addressing the generational shift in the workforce. As newer generations enter the workforce, their differing perspectives and expectations require companies to adapt their management and operational strategies. Additionally, the transition towards sustainable energy sources and the need for enhanced connectivity pose further challenges that the industry must navigate to remain competitive.
Market Opportunities:
The Mexico powder metallurgy market presents significant growth opportunities, driven by the expanding industrial landscape and increasing demand for advanced manufacturing solutions. The automotive sector, a cornerstone of Mexico's manufacturing industry, continues to offer vast potential for powder metallurgy applications. As the global automotive industry shifts towards electric vehicles (EVs) and demands more lightweight and fuel-efficient components, powder metallurgy stands out for its ability to produce complex, durable, and lightweight parts. The growing trend of adopting sustainable manufacturing processes further enhances the appeal of powder metallurgy. Its capacity for material recycling and minimal waste generation aligns with the industry's sustainability goals, positioning it as a favorable manufacturing method for future automotive advancements.
Beyond the automotive sector, the aerospace and medical industries offer additional opportunities for powder metallurgy growth. The increasing demand for high-precision, lightweight components in the aerospace industry is driving the adoption of powder metallurgy techniques. Similarly, the medical sector's need for biocompatible and intricate components for implants and devices aligns well with the strengths of powder metallurgy. Additionally, advancements in additive manufacturing technologies open new avenues for producing customized and complex components, broadening the application scope of powder metallurgy. Mexico's strategic location, skilled labor force, and participation in international trade agreements further enhance its attractiveness as a manufacturing hub. These factors collectively create a conducive environment for the growth of the powder metallurgy market, offering promising opportunities for both domestic and international players to expand their operations and innovate within the sector.
Market Segmentation Analysis:
By Material Segment
In Mexico's powder metallurgy market, ferrous metals, including iron and steel powders, dominate due to their mechanical properties and cost-effectiveness. These materials are extensively utilized in producing automotive components such as gears and bearings. Non-ferrous metals, such as aluminum and copper powders, are gaining traction, particularly in applications requiring lightweight and corrosion-resistant properties, like aerospace and electronics. The 'Others' category encompasses specialized materials like tungsten and titanium powders, which are employed in niche applications demanding high-performance characteristics.
By Application Segment
The automotive industry is the primary consumer of powder metallurgy components in Mexico, driven by the need for efficient production of complex parts. The aerospace sector is also expanding its use of powder metallurgy, leveraging its ability to produce lightweight, high-strength components essential for aircraft performance. Industrial machinery applications benefit from powder metallurgy's precision and material efficiency, enhancing the durability and functionality of machinery parts. In the electrical and electronics sector, powder metallurgy facilitates the production of components like soft magnetic materials, contributing to improved performance of electronic devices. The 'Others' category includes diverse applications such as medical devices and consumer products, where powder metallurgy offers customization and material advantages.
By End-Use Industry Segment
The transportation sector, encompassing automotive and aerospace industries, is the largest end-user of powder metallurgy in Mexico, driven by the demand for lightweight and durable components. The consumer goods industry utilizes powder metallurgy for producing various products, benefiting from its cost-effectiveness and design flexibility. The industrial sector employs powder metallurgy in manufacturing machinery and equipment, taking advantage of its ability to produce wear-resistant and precise components.
By Process Segment
The powder metallurgy process in Mexico involves several key stages: blending, compaction, and sintering. Blending ensures a homogeneous mixture of metal powders, critical for achieving consistent material properties. Compaction forms the blended powders into desired shapes under high pressure, creating 'green' parts with sufficient handling strength. Sintering involves heating these compacted parts below their melting point, bonding the particles and enhancing mechanical properties. Each process stage is integral to producing high-quality powder metallurgy components, contributing to the efficiency and competitiveness of Mexico's manufacturing industries.
Segmentation:
By Material Segment:
- Ferrous Metals
- Non-Ferrous Metals
- Others
By Application Segment:
- Automotive
- Aerospace
- Industrial Machinery
- Electrical & Electronics
- Others
By End-Use Industry Segment:
- Transportation
- Consumer Goods
- Industrial
By Process Segment:
- Blending
- Compaction
- Sintering
Regional Analysis:
The powder metallurgy market in Mexico is influenced by its integration within the broader North American market, characterized by robust industrial activities and a well-established manufacturing infrastructure. In 2023, North America emerged as the leading region in the global powder metallurgy market, accounting for approximately 38% of the total market share. This dominance is attributed to the region's strong automotive and aerospace sectors, which are major consumers of powder metallurgy components.
Mexico's Strategic Position within North America
Within North America, Mexico plays a pivotal role due to its strategic location, cost-competitive labor force, and favorable trade agreements, such as the United States-Mexico-Canada Agreement (USMCA). These factors have attracted significant foreign direct investment in the manufacturing sector, particularly in automotive and aerospace industries. Mexico's integration into the North American supply chain enhances its contribution to the regional powder metallurgy market.
Automotive Industry as a Growth Driver
The automotive industry is a key driver of powder metallurgy demand in Mexico. The country's position as a leading automobile manufacturer, combined with the global shift towards lightweight and fuel-efficient vehicles, has increased the adoption of powder metallurgy techniques. This process enables the production of complex, high-strength components essential for modern vehicles.
Aerospace Sector Expansion
Mexico's aerospace sector has experienced substantial growth, further boosting the powder metallurgy market. The demand for lightweight, durable components in aerospace applications aligns with the advantages offered by powder metallurgy. The establishment of aerospace clusters in regions like Querétaro has solidified Mexico's position as a key player in this industry.
Key Player Analysis:
- GKN Powder Metallurgy
- Carpenter Technology Corporation
- Rio Tinto Metal Powders
- ATI Specialty Materials
- Advanced Materials Technologies
- American Axle & Manufacturing Holdings, Inc.
- Ametek Specialty Metal Products
- Höganäs AB
- Praxair Surface Technologies, Inc.
- Kennametal Inc.
Competitive Analysis:
The powder metallurgy market in Mexico is characterized by a high level of concentration, as indicated by the Herfindahl-Hirschman Index (HHI). In 2023, the HHI stood at 7,004, reflecting a highly concentrated market dominated by a few key players. Major global companies such as Höganäs AB, Melrose Industries PLC, Sumitomo Electric Industries, Ltd., ATI, and Showa Denko Materials Co., Ltd. have established a significant presence in Mexico's powder metallurgy sector. These companies leverage advanced technologies and extensive distribution networks to maintain their competitive edge. For instance, Höganäs AB is known for its innovative metal powder solutions, which are crucial for various industrial applications. The market's competitiveness is further influenced by the growing demand for powder metallurgy components in the automotive and aerospace industries. This demand encourages continuous innovation and efficiency improvements among market participants. Additionally, the increasing adoption of additive manufacturing technologies presents both opportunities and challenges, pushing companies to adapt and innovate to maintain their market positions.
Recent Developments:
- In January 2025, GKN Powder Metallurgy, along with GKN Automotive, was set to be acquired by American Axle & Manufacturing Holdings, Inc. (AAM) in a $1.44 billion deal. This acquisition aims to create a leading driveline and metal-forming supplier for the global automotive industry, enhancing innovation and sustainability efforts.
- In March 2025, Höganäs AB announced a strategic partnership with Porite to supply near zero sponge iron powder, a product designed to minimize carbon emissions during production and lifecycle. This partnership highlights Höganäs' commitment to sustainable manufacturing practices.
Market Concentration & Characteristics:
The Mexico powder metallurgy market is characterized by high market concentration, with a few dominant players holding significant market shares. This is reflected by a high Herfindahl-Hirschman Index (HHI), indicating that major global companies, such as Höganäs AB, Sumitomo Electric Industries, and ATI, command a substantial portion of the market. These key players leverage advanced technologies, strong research and development capabilities, and well-established distribution networks to maintain their competitive edge. The market is defined by characteristics such as a strong focus on technological innovation, sustainability, and process efficiency. The automotive and aerospace sectors primarily drive the demand for powder metallurgy components, owing to the need for lightweight, durable, and cost-effective materials. Additionally, advancements in additive manufacturing have introduced new dynamics, encouraging manufacturers to invest in modern technologies. The market’s concentrated structure emphasizes the importance of innovation, strategic collaborations, and efficient supply chain management for sustained growth.
Report Coverage:
The research report offers an in-depth analysis based on material type, application, end-use industry and process. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Mexico powder metallurgy market is expected to experience steady growth, driven by increasing demand for lightweight and durable automotive components.
- Advancements in additive manufacturing and 3D printing technologies will expand the application scope of powder metallurgy.
- Growing investments in the aerospace sector will enhance the demand for high-performance, precision-engineered metal components.
- The rise of electric vehicles (EVs) will create new opportunities for powder metallurgy in battery and motor component production.
- Sustainable manufacturing practices will drive greater adoption of powder metallurgy due to its low waste and energy-efficient processes.
- Expansion of industrial machinery and consumer electronics sectors will boost demand for complex and customized components.
- Technological innovations in metal powder materials will enhance product durability and expand industrial applications.
- Government initiatives to strengthen local manufacturing capabilities will attract investments and support market growth.
- Enhanced integration into North American supply chains will improve export potential and international collaborations.
- Companies focusing on research and development will gain a competitive edge by offering advanced and cost-effective solutions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Mexico Powder Metallurgy Market?
What factors are driving the growth of the Mexico Powder Metallurgy Market?
What are some challenges faced by the Mexico Powder Metallurgy Market?
Who are the major players in the Mexico Powder Metallurgy Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Mexico Powder Metallurgy Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Mexico Powder Metallurgy Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 68.6 million → 2032: USD 103.62 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Mexico Powder Metallurgy Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Mexico Powder Metallurgy Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Mexico Powder Metallurgy Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Mexico Powder Metallurgy Market Drivers
- 3.3 Mexico Powder Metallurgy Market Restraints & Challenges
- 3.4 Mexico Powder Metallurgy Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Mexico Powder Metallurgy Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Mexico Powder Metallurgy Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Mexico Powder Metallurgy category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Mexico Powder Metallurgy Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Mexico Powder Metallurgy Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Mexico Powder Metallurgy market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Mexico Powder Metallurgy Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Mexico Powder Metallurgy Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Mexico Powder Metallurgy Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Mexico Powder Metallurgy (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Mexico Powder Metallurgy Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Mexico Powder Metallurgy Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Mexico Powder Metallurgy Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Mexico Powder Metallurgy Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Mexico Powder Metallurgy Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Mexico Powder Metallurgy Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Mexico Powder Metallurgy Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Mexico Powder Metallurgy Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Mexico Powder Metallurgy Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
