
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Mexico Processed Beef Product Market Size 2023 | USD 1,330.99 million |
| Mexico Processed Beef Product Market, CAGR | 4.09% |
| Mexico Processed Beef Product Market Size 2032 | USD 1,910.78 million |
Market Overview:
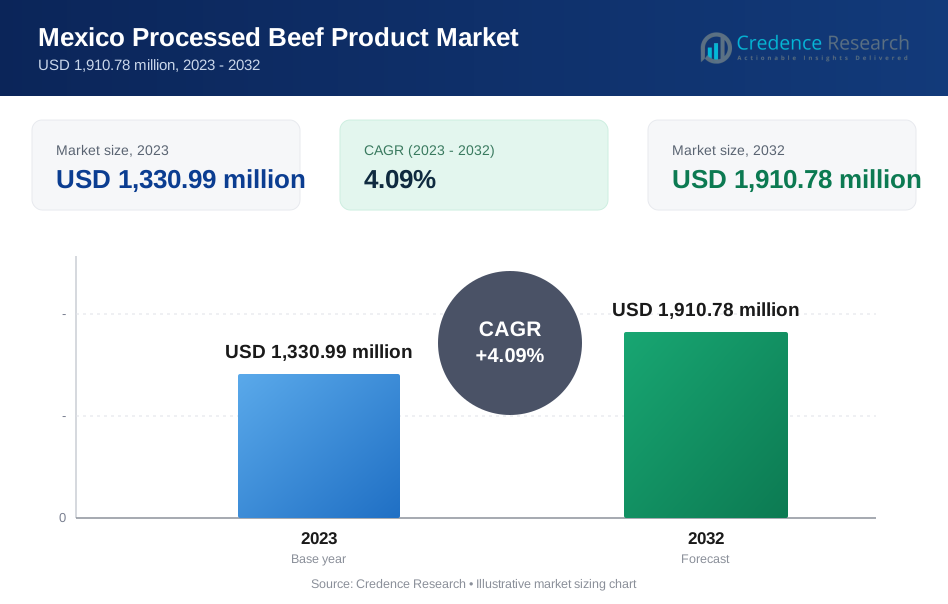
Mexico Processed Beef Product Market size was valued at USD 1,330.99 million in 2023 and is anticipated to reach USD 1,910.78 million by 2032, at a CAGR of 4.09% during the forecast period (2023-2032).
Several factors contribute to the robust expansion of Mexico's processed beef market. Rapid urbanization and the increasing prevalence of dual-income households have fueled a shift toward convenient, ready-to-eat food solutions. As a result, processed beef products—including sausages, deli meats, canned beef, and frozen ready-to-cook meals—have gained significant traction among urban consumers seeking quick and hassle-free meal options. The growing influence of Western dietary trends and fast-food culture has further boosted demand for processed beef, particularly among younger demographics. Additionally, aggressive marketing strategies and continuous product innovation by key industry players have heightened consumer awareness and acceptance of these products. Companies are investing in attractive packaging, improved shelf-life technologies, and value-added formulations that cater to evolving consumer preferences. Notably, the increasing emphasis on health-conscious consumption trends is reshaping the market landscape. With rising concerns over sodium levels, preservatives, and artificial additives, manufacturers are actively developing low-fat, reduced-sodium, and organic processed beef alternatives to appeal to health-conscious consumers.
Mexico's processed beef market exhibits regional disparities in consumption patterns, influenced by demographics, economic factors, and dietary traditions. Urban centers such as Mexico City, Guadalajara, and Monterrey dominate the market, driven by high population densities, increasing disposable incomes, and the prevalence of modern retail channels. Consumers in these metropolitan areas exhibit a strong inclination toward convenient, packaged meat products, particularly in the quick-service restaurant (QSR) sector, supermarkets, and hypermarkets. Furthermore, international fast-food chains and modern retail formats have expanded their footprint in urban areas, reinforcing the demand for processed beef products. In contrast, rural and semi-urban regions exhibit lower per capita consumption, largely due to traditional dietary habits and limited penetration of processed food retailing. Many rural consumers still prefer fresh, locally sourced meat over pre-packaged processed alternatives. Additionally, lower purchasing power and limited access to cold storage infrastructure pose challenges to market expansion in these areas.
Market Insights:
- The Mexico Processed Beef Product Market was valued at USD 1,330.99 million in 2023 and is projected to reach USD 1,910.78 million by 2032, growing at a CAGR of 4.09% during the forecast period.
- Urbanization and dual-income households are increasing the demand for ready-to-eat processed beef products, including sausages, deli meats, and canned beef, as consumers prioritize convenience.
- The foodservice industry, particularly quick-service restaurants (QSRs) and fast-food chains, is a major driver, with rising demand for processed beef in burgers, tacos, and sandwiches.
- Product innovation and health-conscious trends are reshaping the market, with manufacturers introducing low-fat, reduced-sodium, and organic processed beef options to appeal to health-conscious consumers.
- Cold chain logistics and modern retail infrastructure are expanding, improving product availability in semi-urban and rural areas, while e-commerce and direct-to-consumer sales gain traction.
- Regulatory pressures and rising health concerns over sodium content and preservatives are driving manufacturers to reformulate products, impacting production costs and pricing strategies.
- Regional consumption disparities remain, with Mexico City, Guadalajara, and Monterrey dominating sales due to higher disposable incomes and modern retail access, while rural areas exhibit lower demand due to traditional dietary habits and limited distribution networks.
Market Drivers:
Rising Urbanization and Changing Lifestyles
The increasing rate of urbanization in Mexico has significantly impacted consumer food preferences, fostering greater demand for convenience-oriented food products, including processed beef. As more people migrate to metropolitan areas, their lifestyles have become faster-paced, reducing the time available for traditional meal preparation. Dual-income households are now more common, further amplifying the need for ready-to-eat and easy-to-prepare meals. For instance, processed beef products, such as cooked sausages, deli meats, canned beef, and frozen ready-to-cook options, cater to these changing consumer behaviors by offering time-saving and accessible meal solutions. The expansion of retail chains, supermarkets, and online grocery platforms has further reinforced accessibility, ensuring that processed beef products remain a convenient and widely available choice for urban dwellers.
Expanding Quick-Service Restaurants and Foodservice Sector
The growth of quick-service restaurants (QSRs), fast-food chains, and the broader foodservice industry has been a crucial driver for Mexico’s processed beef market. Fast-food consumption is on the rise, particularly in urban centers, where global franchises and local QSR brands have expanded their presence. For instance, Burger King and McDonald's, These are leading quick-service restaurants in Mexico, with Burger King being the favorite. Processed beef is a key ingredient in many popular fast-food items, including burgers, tacos, sandwiches, and ready-made meat toppings, driving consistent demand from restaurant operators. The increasing penetration of food delivery services and app-based meal ordering platforms has further boosted the consumption of processed beef, as consumers seek quick and affordable dining options. Moreover, changing consumer habits, particularly among younger demographics, have led to a preference for protein-rich, flavorful, and globally influenced beef-based meals, strengthening the processed beef industry’s foothold in the foodservice segment.
Product Innovation and Health-Oriented Offerings
Innovation in processed beef formulations, packaging, and nutritional content has played a significant role in attracting new consumer segments. Growing awareness of health and wellness trends has led to a rising demand for low-fat, reduced-sodium, and preservative-free processed beef products. Manufacturers are responding by reformulating products to align with consumer expectations for clean-label, organic, and high-protein meat products. The incorporation of functional ingredients such as plant-based additives, collagen, and essential vitamins has also emerged as a strategy to enhance product appeal. Additionally, advancements in food processing technology, extended shelf-life solutions, and eco-friendly packaging have allowed manufacturers to cater to both health-conscious consumers and environmentally aware buyers. These innovations not only improve consumer trust but also create a competitive edge for brands looking to differentiate themselves in the market. For instance, Micro Meat: Mexico's first cultivated meat startup, focused on developing technologies to scale up cultured meat production
Expanding Cold Chain Logistics and Retail Infrastructure
The continuous expansion of cold storage facilities, refrigerated transport, and modern retail infrastructure has been instrumental in driving the processed beef market’s growth. For instance, Mexico imported 2.4 million tons of beef, pork, chicken, and turkey during a recent period, surpassing the previous year's imports by 176,000 tons. The improvement of logistics networks ensures that processed meat products maintain their quality, safety, and shelf-life, allowing greater penetration into new markets, including semi-urban and rural regions. Additionally, the increasing presence of supermarkets, hypermarkets, and convenience stores has made processed beef products more accessible to a broader consumer base. The emergence of e-commerce platforms and direct-to-consumer delivery services has further strengthened the market, providing consumers with convenient purchasing options. As logistics infrastructure continues to advance, processed beef manufacturers can expand their distribution networks, reaching previously underserved regions and diversifying their consumer base.
Market Trends:
Growing Demand for Premium and Specialty Processed Beef
Consumers in Mexico are increasingly gravitating toward premium and specialty processed beef products, driven by rising disposable incomes and evolving taste preferences. There is a noticeable shift toward higher-quality meat cuts, artisanal cured beef, and gourmet deli meats, particularly in urban markets. For instance, La Chona, A meat and dairy brand that offers a wide variety of Mexican cheeses, creams, and packaged meats, bringing traditional Mexican flavors to the table. This trend is fueled by affluent consumers seeking better taste, texture, and nutritional value in processed meat products. Additionally, demand for ethnic and international flavors is rising, with more consumers exploring global culinary influences such as Argentinian-style cured meats, American smoked beef, and Italian-style pastrami. The increasing presence of premium butcher shops, gourmet supermarkets, and online specialty meat retailers has further reinforced this trend by offering a wider selection of high-quality processed beef products.
Expansion of Plant-Based and Hybrid Meat Alternatives
The processed beef market in Mexico is witnessing growing interest in plant-based and hybrid meat alternatives, reflecting shifting consumer preferences toward healthier and more sustainable diets. Although traditional processed beef remains dominant, an increasing number of consumers—particularly in younger demographics—are opting for plant-forward alternatives that combine beef with plant-derived proteins to enhance nutrition while reducing environmental impact. Food manufacturers are responding by introducing hybrid beef products blended with soy, pea protein, or mushroom-based ingredients, offering a balance of taste, protein content, and sustainability. For instance, NotCo: A Chilean company that produces plant-based alternatives and has partnered with major chains in Mexico like Burger King, Chilli’s, and Starbucks. While the plant-based meat segment is still in its early stages in Mexico, the rising awareness of flexitarian diets and concerns over the environmental impact of traditional meat production are expected to drive steady growth in this area.
E-commerce and Direct-to-Consumer Sales on the Rise
The rapid expansion of e-commerce platforms and direct-to-consumer (DTC) delivery models is reshaping how processed beef products are purchased in Mexico. Consumers are increasingly shopping for processed meat online, attracted by the convenience, competitive pricing, and exclusive product offerings available through digital channels. Major supermarkets, specialty meat brands, and independent producers are investing in user-friendly online stores, For instance, Oxxo's Processed Meat Sales Growth: Oxxo is Mexico's largest convenience store chain, and its sales data is often referenced in retail and market analyses. subscription-based meat delivery services, and partnerships with food delivery platforms to enhance customer reach. The adoption of cold-chain logistics and advanced packaging solutions has enabled safer and more efficient online distribution of processed beef, ensuring freshness and quality upon delivery. This trend is particularly significant in metropolitan areas where time-strapped consumers prefer the ease of home delivery over traditional in-store shopping.
Emphasis on Sustainability and Ethical Sourcing
Sustainability concerns and ethical sourcing practices are becoming more influential in consumer decision-making within Mexico’s processed beef market. Consumers are increasingly aware of issues related to livestock farming practices, deforestation, carbon emissions, and animal welfare, prompting many to seek out ethically sourced and environmentally friendly processed beef options. In response, meat processors and retailers are prioritizing sustainable sourcing, regenerative farming, and carbon-neutral meat production to align with these evolving expectations. Labels such as "grass-fed," "organic," and "certified humane" are gaining popularity as consumers associate them with superior quality and responsible production methods. As sustainability gains traction, companies that implement transparent supply chains and promote eco-friendly packaging will have a competitive advantage in the market. For instance, SuKarne: This leading Mexican meat company is constructing a large beef production/processing complex in Durango with cutting-edge environmental protection technology and adherence to international sanitary standards
Market Challenges Analysis:
Rising Health Concerns and Regulatory Pressures
One of the primary challenges facing the Mexico processed beef market is the increasing consumer awareness of health risks associated with processed meat consumption. Studies linking high sodium content, preservatives, and processed meat additives to health issues such as cardiovascular diseases and obesity have led to shifting dietary preferences. Consumers are becoming more cautious about their processed meat intake, prompting a growing preference for fresh and minimally processed alternatives. Additionally, the Mexican government has implemented stricter food labeling and health regulations, such as warning labels on high-sodium and high-fat products. These regulatory pressures require manufacturers to reformulate products, reduce artificial additives, and develop healthier variants, which can increase production costs and impact profit margins.
Supply Chain Disruptions and Price Volatility
The processed beef industry in Mexico faces ongoing challenges related to supply chain inefficiencies and raw material price volatility. Fluctuations in cattle feed prices, import restrictions, and transportation costs significantly impact the pricing of processed beef products. Mexico’s heavy dependence on both domestic cattle production and imported meat supplies makes the market vulnerable to global trade fluctuations, disease outbreaks, and climate-related disruptions affecting livestock production. Additionally, inefficiencies in cold storage infrastructure and transportation logistics, especially in rural and semi-urban areas, can lead to increased spoilage rates and higher distribution costs. These challenges create barriers for manufacturers looking to expand into underserved regions, making it difficult to maintain consistent product availability and affordability.
Market Opportunities:
The Mexico processed beef market presents a significant opportunity for manufacturers to develop and market healthier, high-quality processed meat products. With increasing consumer awareness of nutrition and food safety, there is a growing demand for low-sodium, organic, preservative-free, and protein-enriched beef products. Companies that invest in clean-label formulations, functional ingredients, and premium meat cuts can capture a lucrative segment of health-conscious consumers. Additionally, the expansion of premium and gourmet processed beef options, including artisanal cured meats and internationally inspired flavors, provides further opportunities for differentiation. By emphasizing quality, transparency, and innovation, brands can appeal to urban professionals and affluent consumers willing to pay a premium for superior taste and healthier alternatives.
The rise of modern retail formats, foodservice expansion, and e-commerce platforms presents another key growth avenue for processed beef manufacturers. Supermarkets, hypermarkets, and convenience stores are increasing their processed meat offerings, making it easier for brands to expand their presence and reach diverse consumer segments. Additionally, the rapid adoption of online grocery shopping and direct-to-consumer (DTC) delivery services has created new sales channels, particularly in urban areas where digital purchasing is gaining momentum. Companies that leverage digital marketing, subscription-based meat delivery models, and customized product offerings can gain a competitive edge in an increasingly digitized retail landscape. These opportunities position the processed beef industry for sustained growth by aligning with consumer demand for convenience, accessibility, and product diversity.
Market Segmentation Analysis:
The Mexico processed beef market is segmented based on product, type, end-user, packaging, and distribution channel, each playing a critical role in shaping market demand and consumer preferences.
By Product, the market is divided into cured processed and uncured processed beef, with cured processed beef dominating due to its extended shelf life and widespread use in deli meats and sausages. However, uncured processed beef is gaining popularity as consumers seek healthier, preservative-free options.
By Type, the segment includes beef meat, mechanically recovered meat, burgers/sausages, and by-products such as skin, bones, ligaments, and tendons. Burgers and sausages account for a substantial share, driven by fast-food consumption and retail availability, while mechanically recovered meat is widely used in processed formulations for affordability.
By End-user, the market is categorized into commercial/institutional and household consumers. The commercial sector, including restaurants, hotels, and institutional buyers, holds a dominant share due to bulk purchasing, while household consumption is growing with the increasing preference for ready-to-cook processed beef.
By Packaging, key formats include fresh meat packaging, vacuum packaging, and modified atmosphere packaging (MAP). Vacuum and MAP technologies are expanding due to their ability to extend shelf life and maintain product freshness, making them highly preferred in modern retail.
By Distribution Channel, retail outlets, food services, and e-commerce drive sales. Supermarkets and hypermarkets remain primary sales points, while e-commerce is witnessing rapid growth, fueled by increasing online grocery adoption. Food services, including quick-service restaurants (QSRs), further contribute significantly to overall market demand.
Segmentation:
By Product
- Cured Processed
- Uncured Processed
- Others
By Type
- Beef meat
- Mechanically recovered meat
- Burgers/sausages
- Skin, bones, ligaments and tendons
- Others
By End-user
- Commercial/Institutional
- Household/Consumers
By Packaging
- Fresh Meat Packaging
- Vaccum Packaging
- Modified Atmosphere packaging
By Distribution Channel
- Retail
- Food Services
- E-Commerce
Regional Analysis:
The processed beef product market in Mexico exhibits distinct regional variations influenced by factors such as population density, economic development, and cultural preferences. Urban centers, notably Mexico City, Guadalajara, and Monterrey, dominate the market due to their substantial populations and higher disposable incomes. These cities have a pronounced demand for convenient, ready-to-eat processed beef products, driven by fast-paced lifestyles and the prevalence of modern retail outlets. The widespread availability of supermarkets, hypermarkets, and convenience stores in these urban areas facilitates consumer access to a diverse range of processed meat products.
In contrast, rural regions of Mexico present a different market dynamic. Here, consumption of processed beef products is comparatively lower, primarily due to traditional dietary habits that favor fresh, locally sourced meats. Economic constraints and limited access to modern retail infrastructure further contribute to the subdued demand in these areas. However, with ongoing infrastructure development and efforts to improve cold chain logistics, there is potential for market expansion. Companies aiming to penetrate these regions must consider tailored marketing strategies and product offerings that align with local preferences and purchasing power.
Key Player Analysis:
- JBS SA
- National Beef Packing Company, LLC
- American Foods Group, LLC.
- Agri Beef Co.
- Perdue Farms Inc.
- Tyson Foods, Inc
- Strauss Brands LLC
- Cargill, Incorporated
- Central Valley Meat
- Danish Crown A/S
- JS Ol Meat Co., Ltd
- Sunnong Life Co.,Ltd
- Company 13
- Company 14
Competitive Analysis:
The Mexico processed beef product market is highly competitive, with a mix of domestic and international players vying for market share. Leading companies differentiate themselves through product innovation, extensive distribution networks, and brand positioning. Established brands dominate supermarket shelves, leveraging strong brand recognition and strategic partnerships with retailers and foodservice providers to maintain their competitive edge. For instance, SuKarne: Is one of the largest private meat and poultry companies in Mexico2. They hold the most market share in the Meat, Beef, & Poultry Processing industry in Mexico. Additionally, companies are investing in premium product lines, healthier formulations, and value-added offerings to cater to evolving consumer preferences. International meat processors benefit from advanced processing technologies and large-scale production capabilities, while local producers capitalize on regional supply chains and cost efficiencies to remain competitive. The growing influence of private-label brands and artisanal meat processors is also reshaping the competitive landscape, as consumers seek quality, transparency, and niche product offerings. As competition intensifies, companies that adapt to changing consumer demands, enhance sustainability efforts, and expand digital sales channels will secure long-term market growth.
Recent Developments:
- Central Valley Meathas acquired a beef processing plant from Cargill as of May 9, 2024. This strategic acquisition is intended to enhance Central Valley's capacity to meet market demands while supporting local cattle and dairy industries in California.
- Tyson Foods, Inc.has been proactive in preparing for potential market disruptions due to trade tariffs affecting U.S. imports into Mexico. On February 5, 2025, Tyson's CEO Donnie King stated that the company is developing contingency plans to identify alternative markets for their products should Mexican imports be curtailed.
- Duravant LLChas announced its acquisition of Pattyn Group BV, which is expected to close in the second quarter of 2025, pending regulatory approvals. This acquisition will enhance Duravant's packaging machinery portfolio and allow Pattyn to expand into new markets while maintaining its commitment to customer service.
- Chompsannounced plans to open a new state-of-the-art manufacturing facility in Mexico, Missouri, slated for completion in 2025.
Market Concentration & Characteristics:
The Mexico processed beef product market is moderately concentrated, with a few dominant players holding a significant share, while numerous smaller and regional producers contribute to market diversity. Large multinational companies and established domestic brands control a major portion of the market through extensive distribution networks, strong brand recognition, and economies of scale. These companies leverage advanced processing technologies, product innovation, and strategic retail partnerships to maintain their competitive position. Despite the presence of leading players, regional and independent meat processors continue to gain traction by offering specialized, locally sourced, and artisanal products. The market is characterized by a growing demand for premium, health-conscious, and convenient processed beef options, influencing manufacturers to innovate with clean-label, organic, and functional meat products. Additionally, the expansion of e-commerce and direct-to-consumer sales is reshaping market dynamics, allowing new entrants to compete effectively against established brands.
Report Coverage:
The research report offers an in-depth analysis based on By Product, By Type, By End-user, By Packaging and By Distribution Channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Mexico processed beef market is expected to grow steadily, driven by urbanization and increasing demand for convenient food options.
- Manufacturers will focus on low-sodium, preservative-free, and high-protein processed beef to meet health-conscious consumer preferences.
- The demand for gourmet, artisanal, and specialty beef products will rise, particularly among affluent consumers.
- E-commerce, direct-to-consumer models, and modern retail formats will expand, increasing market accessibility.
- The foodservice sector, including quick-service restaurants (QSRs) and meal delivery platforms, will drive higher consumption.
- Advancements in processing technology, sustainable packaging, and extended shelf-life solutions will enhance industry efficiency.
- Cold storage logistics and distribution infrastructure improvements will enable market expansion into semi-urban and rural areas.
- Sustainable sourcing, regenerative farming, and eco-friendly processing will gain importance to meet consumer and regulatory expectations.
- Competition will intensify as both domestic and international players introduce differentiated and innovative products.
- Stricter health and labeling regulations, along with shifting dietary habits, will push manufacturers to reformulate products and comply with evolving standards.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Mexico Processed Beef Product Market?
What factors are driving the growth of the Mexico Processed Beef Product Market?
What are the key segments within the Mexico Processed Beef Product Market?
What are some challenges faced by the Mexico Processed Beef Product Market?
Who are the major players in the Mexico Processed Beef Product Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Mexico Processed Beef Product Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Mexico Processed Beef Product Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 1,330.99 million → 2032: USD 1,910.78 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Mexico Processed Beef Product Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Mexico Processed Beef Product Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Mexico Processed Beef Product Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Mexico Processed Beef Product Market Drivers
- 3.3 Mexico Processed Beef Product Market Restraints & Challenges
- 3.4 Mexico Processed Beef Product Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Mexico Processed Beef Product Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Mexico Processed Beef Product Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Mexico Processed Beef Product category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Mexico Processed Beef Product Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Mexico Processed Beef Product Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Mexico Processed Beef Product market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Mexico Processed Beef Product Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Mexico Processed Beef Product Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Mexico Processed Beef Product Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Mexico Processed Beef Product (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Mexico Processed Beef Product Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Mexico Processed Beef Product Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Mexico Processed Beef Product Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Mexico Processed Beef Product Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Mexico Processed Beef Product Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Mexico Processed Beef Product Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Mexico Processed Beef Product Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Mexico Processed Beef Product Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Mexico Processed Beef Product Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
