
Global Micro Electrode Array Market Overview:
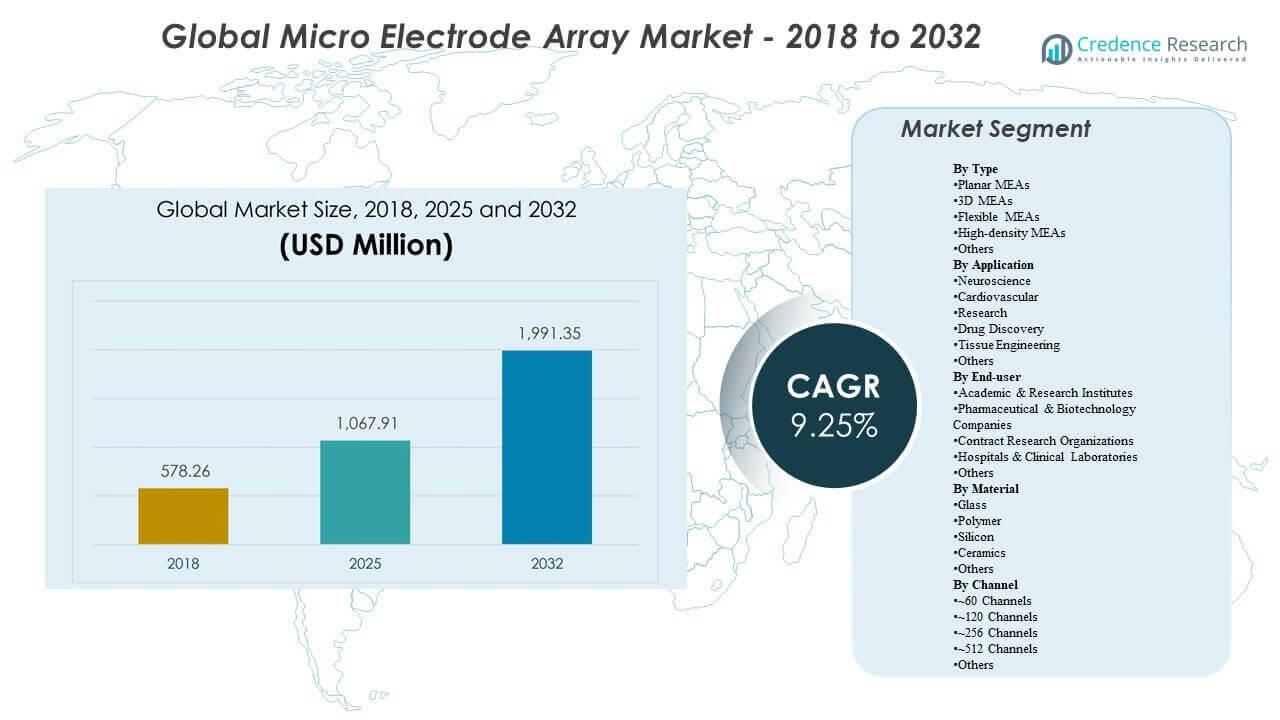
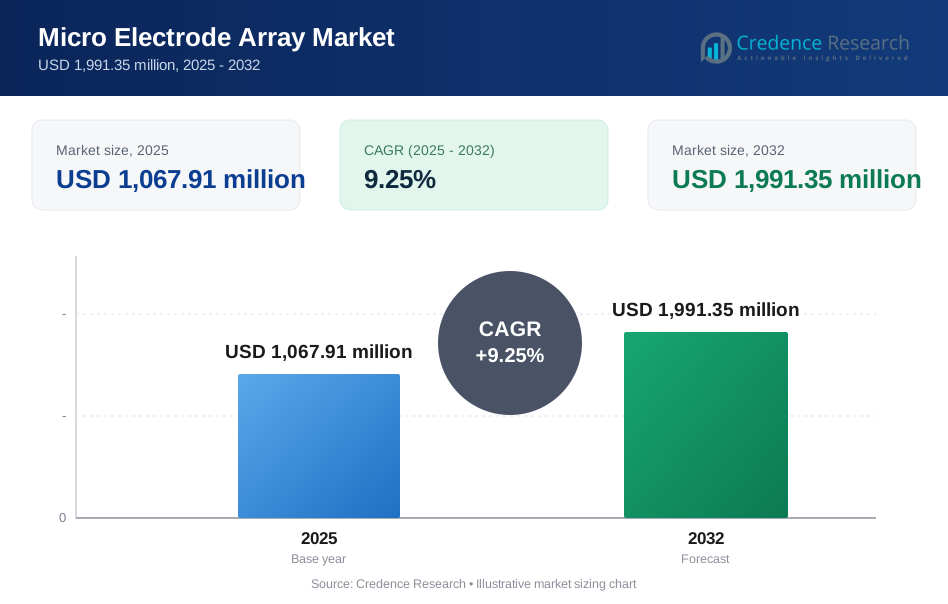
The Global Micro Electrode Array Market size was USD 578.26 million in 2018, reached USD 1,067.91 million in 2025, and is expected to reach USD 1,991.35 million by 2032, growing at a CAGR of 9.25% from 2025 to 2032. Growth is primarily driven by expanding use of MEA platforms in neuroscience workflows, where labs increasingly rely on network-level electrophysiology readouts for disease modeling, functional phenotyping, and longitudinal monitoring of iPSC-derived neuronal systems. Over the forecast period, faster growth momentum in Asia Pacific, supported by rising research capacity and adoption of advanced in-vitro models, is expected to strengthen demand for both entry-level systems and higher-density platforms.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Micro Electrode Array Market Size 2025 | USD 1,067.91 million |
| Micro Electrode Array Market, CAGR | 9.25% |
| Micro Electrode Array Market Size 2032 | USD 1,991.35 million |
Key Market Trends & Insights
- The market is projected to expand from USD 1,067.91 million in 2025 to USD 1,991.35 million by 2032 at a CAGR of 9.25% (2025–2032).
- Market scale-up from USD 578.26 million in 2018 to USD 1,067.91 million in 2025 indicates sustained multi-year adoption across research and translational use cases.
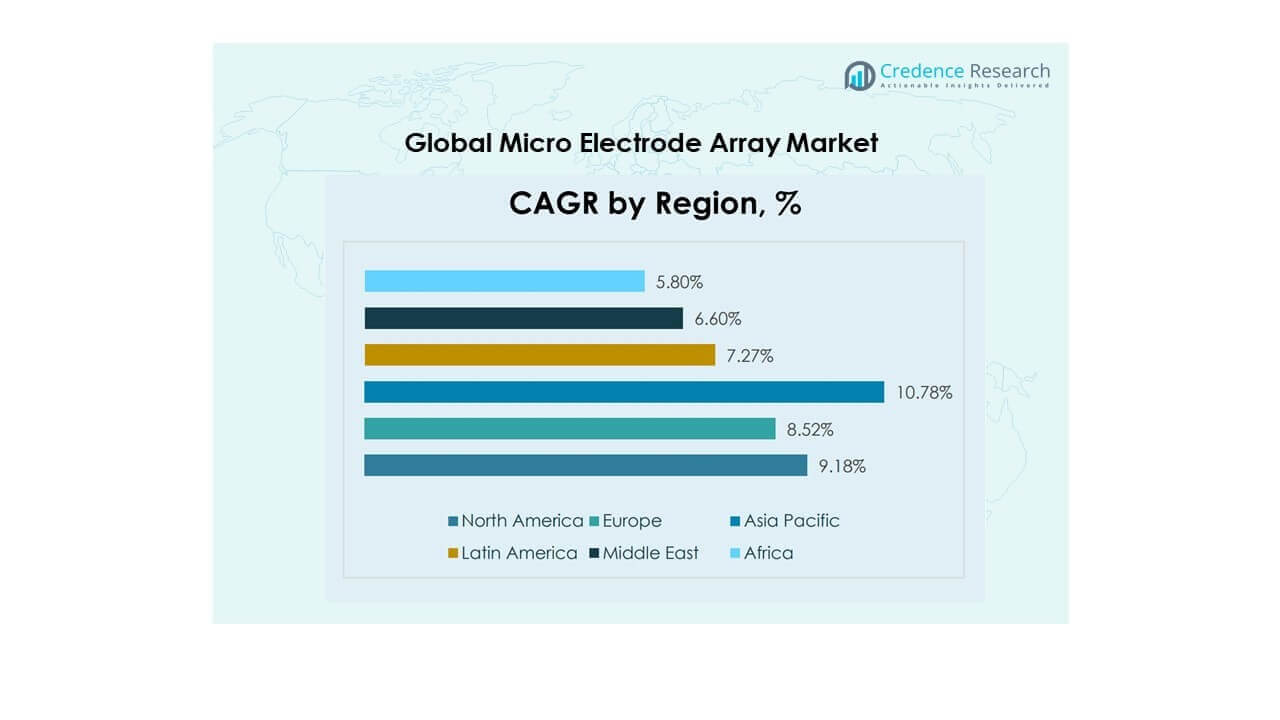
- Asia Pacific is expected to be the fastest-growing region with a CAGR of 10.78% during 2025–2032, reflecting accelerating platform adoption and research expansion.
- North America is forecast to grow at a CAGR of 9.18% from 2025–2032, supported by a large installed base and continued upgrades in academic and translational labs.
- Technology differentiation continues to widen, with high-density systems scaling to 26,400 electrodes per well in some multi-well HD-MEA configurations, enabling finer spatial mapping and stimulation.
Segment Analysis
Demand patterns in the micro electrode array market are shaped by how well platforms align with core electrophysiology workflows in neuroscience and adjacent functional screening applications. Buyers typically prioritize reproducibility of recordings, stability of electrode performance, and the maturity of the surrounding ecosystem, including plates/chips availability, analysis software, and assay protocols. As model complexity increases-especially with iPSC-derived neuronal systems, organoids, and long-term culture workflows-labs increasingly evaluate higher-density configurations and more specialized formats that can deliver richer spatial and temporal information.
Adoption also depends on practical deployment factors such as training burden, throughput requirements, and total cost of ownership. Academic and research institutes often anchor the installed base by adopting standardized systems and building protocols that later diffuse into broader translational use. In parallel, drug discovery and safety-oriented programs favor configurations that balance signal richness with manageable data complexity and scalable workflows, reinforcing demand for mid-range channel systems and platforms that support semi-automated operation.
By Type Insights
Planar MEAs lead by type because they are widely standardized, easier to integrate into established lab protocols, and supported by broad consumables and workflow availability. Their familiarity across neuroscience and cardiac labs reduces implementation risk and shortens time-to-data for new users. Planar formats also fit routine multiwell workflows where reproducibility and throughput are prioritized over maximum spatial resolution. As a result, they often serve as the preferred entry point before some labs selectively upgrade to higher-density, flexible, or 3D architectures for advanced assays.
By Application Insights
Neuroscience leads by application as MEAs enable network-level activity monitoring that is central to functional phenotyping, disease modeling, and mechanism studies. Neuronal networks often require longitudinal observation and repeated stimulation/recording cycles, which aligns well with MEA platform capabilities. Higher-density approaches further strengthen neuroscience use by enabling finer spatial mapping of circuits and more detailed activity signatures. These factors collectively reinforce neuroscience as the most consistent demand driver across both academic and translational settings.
By End-user Insights
Academic & Research Institutes lead by end-user due to sustained grant-funded neuroscience and electrophysiology research programs that build and maintain the installed base. Universities and research institutes also act as early adopters of new formats, expanding applications and establishing validated protocols. Their multi-year projects support recurring purchases of plates/chips and ongoing software usage. In addition, academic training pipelines help standardize MEA workflows, which supports continued utilization and broader ecosystem adoption.
By Material Insights
Glass leads by material because it is strongly compatible with combined electrophysiology and imaging workflows that are common in neuroscience and cardiomyocyte research. Glass substrates support stable surface properties and well-established fabrication approaches, which helps maintain consistency across chip and plate formats. Practical handling and compatibility with standard microscopy workflows further reinforce adoption in research labs. These attributes make glass a dependable baseline material choice for many widely deployed MEA configurations.
By Channel Insights
~256 channels lead by channel as this configuration typically balances data richness with manageable complexity, enabling robust assays without the highest computational or storage burden. It aligns well with many core neuroscience and cardiac workflows where higher signal density improves interpretation but must remain practical for routine execution. Mid-range channel counts also suit procurement realities because they provide strong functional performance without pushing costs to maximum-density tiers. This balance makes ~256-channel systems a common choice for broad deployment across research environments.
Micro Electrode Array Market Drivers
Expansion of neuroscience research and advanced in-vitro models
MEA demand increases as neuroscience programs scale functional phenotyping, disease modeling, and network-level activity profiling. Laboratories increasingly use iPSC-derived neuronal models that benefit from repeatable, longitudinal electrophysiology endpoints. This supports ongoing purchases of MEA plates/chips and upgrades to platforms with richer mapping and stimulation capability. As protocols become more standardized, MEAs move from specialist use toward broader adoption across research teams. This shift also increases demand for turnkey assay workflows that reduce setup time and improve cross-lab comparability.
- For instance, MaxWell Biosystems’ MaxTwo HD-MEA platform provides 26,400 electrodes per well and is offered in both 6-well and 24-well formats, while maintaining single-cell and subcellular resolution for in-vitro electrophysiology studies.
Growing use of functional assays in drug discovery workflows
Drug discovery groups are placing greater emphasis on functional endpoints that complement molecular and imaging readouts. MEAs provide label-free electrophysiology measurements that can improve confidence in mechanism and response characterization. This supports demand for configurations that balance throughput and signal content, including mid-range channel systems and multiwell formats. Over time, workflow integration and automation can widen use across screening and translational programs. As adoption expands, buyers increasingly prioritize platforms with scalable data handling and standardized analysis outputs.
Ecosystem maturation and workflow simplification
Platform ecosystems continue to mature through improved software, easier analysis pipelines, and better compatibility across plates/chips and assay formats. Reduced training burden and clearer protocols shorten implementation time and improve reproducibility. These advances make MEA deployment more feasible for labs that previously relied on outsourced electrophysiology or lower-content endpoints. As usability improves, installed base expansion supports recurring consumables demand. Vendor-led application support and validated protocols further accelerate adoption by lowering experiment failure risk.
- For instance, Multi-Channel Systems’ MEA2100 headstage can be configured for one 60-electrode, one 120-electrode, one 256-electrode, or two 60-electrode MEAs, and it includes 3 independent stimulation channels per MEA slot, helping labs change formats without replacing the rest of the setup.
Technology improvements in density and throughput
Higher-density architectures and improved multiwell workflows enable richer spatial mapping and more scalable experimentation. Increased electrode density supports fine-grained phenotyping and more targeted stimulation, which is valuable in complex neural models and organoid work. At the same time, throughput-oriented designs help labs standardize experiments across larger sample sets. This combination supports both premium platform upgrades and broader adoption in research-heavy environments. Continued improvements in electrode stability and signal quality also strengthen confidence in long-duration and repeat-measurement studies.
Micro Electrode Array Market Challenges
Cost and procurement constraints remain a key barrier, particularly for smaller labs that must balance capital budgets across multiple instrumentation categories. MEA platforms can require additional spending for compatible plates/chips, maintenance, and software, increasing total cost of ownership beyond the initial system price. Funding cycles and purchasing approvals can lengthen adoption timelines and delay upgrades. These factors can be especially limiting where demand is episodic or tied to short-duration grants. Budget pressure can also push buyers toward lower-spec systems even when higher-density capabilities would improve assay value.
Operational complexity also limits wider adoption because MEA experiments require careful cell culture preparation, assay standardization, and reliable signal processing. Data volume and analysis requirements increase with channel count and density, adding compute, storage, and workflow overhead. Variability in protocols across sites can reduce reproducibility and slow cross-lab standardization. In some cases, limited trained personnel can constrain utilization even after platforms are installed. Integration challenges with existing lab informatics and inconsistent quality control steps can further slow routine deployment.
- For instance, 3Brain’s BioCAM DupleX can simultaneously record from 4,096 channels at 20 kHz per electrode, supports 1 to 4 region-of-interest subsets at up to 64 kHz, and uses a 13 Gbps FPGA with 2 GB DDR4, which shows how higher-density MEA systems can sharply increase downstream data-handling and analysis demands.
Market Trends and Opportunities
High-density MEA adoption is expanding as labs seek richer functional signatures for complex neuronal systems, including organoids and long-term cultures. Increased electrode density supports higher-resolution mapping and more precise stimulation workflows, strengthening demand among advanced users. As analysis toolchains improve, high-content electrophysiology becomes more accessible to non-specialist teams. This trend creates opportunities for vendors offering integrated hardware-software ecosystems and validated assay bundles. Demand is also growing for HD-MEA-compatible plates and consumables that support standardized, repeatable experiments at scale.
Workflow automation and multiwell standardization represent another opportunity area as users prioritize throughput and repeatability. Semi-automated measurement approaches can reduce hands-on time, improve consistency, and make routine screening more feasible. This supports adoption in settings where MEAs must fit within standardized lab operations rather than bespoke research setups. Vendors that reduce setup time, simplify data interpretation, and provide robust support can gain share as adoption broadens. Over time, automation-friendly workflows can also improve utilization rates and strengthen the business case for multi-system deployments.
- For instance, Axion Biosystems states that its Maestro Edge supports 6- and 24-well MEA throughput with 384 simultaneous live recordings, uses a “one button setup” that automatically adjusts temperature and CO₂ on plate docking, and includes automatic barcode-based plate tracking; its hardware guide also lists 12.5 kHz sampling across 384 channels, built-in 0–10% CO₂ control with ±0.1% resolution, and an MEA Automation API for integration with liquid-handling platforms.
Regional Insights
North America
North America is expected to grow at a CAGR of 9.18% from 2025 to 2032, supported by a strong installed base across neuroscience and translational research environments. The region benefits from high research intensity, established electrophysiology expertise, and continued uptake of advanced in-vitro models that require functional readouts. Upgrade cycles toward higher-density platforms and workflow-optimized multiwell systems support sustained demand. Collaboration between academia, industry, and specialized research centers helps standardize protocols, reinforcing recurring consumable use.
Europe
Europe is projected to expand at a CAGR of 8.52% during 2025–2032, driven by established electrophysiology hubs and cross-institution research networks. Adoption remains anchored in neuroscience programs and expanding functional assay usage in translational settings. Multi-site collaboration supports demand for reproducible platforms and consistent consumables supply. Growth is also supported by ongoing modernization of research infrastructure and deeper integration of electrophysiology into advanced cell model workflows.
Asia Pacific
Asia Pacific is forecast to be the fastest-growing region with a CAGR of 10.78% from 2025 to 2032. Growth is underpinned by expanding research capacity, increasing investment in advanced in-vitro and iPSC-based models, and wider adoption of functional screening approaches. Laboratories in the region are scaling both entry-level deployments and upgrades to higher-density systems as model complexity rises. As standardization improves and training capacity expands, demand for MEA systems and associated consumables is expected to accelerate.
Latin America
Latin America is expected to grow at a CAGR of 7.27% over 2025–2032, reflecting measured expansion centered on leading academic institutions and selective translational programs. Procurement tends to be more budget-sensitive, which favors standardized, practical configurations with clear workflow fit. Adoption often concentrates in a limited number of research-intensive centers that can support training and protocol development. Over time, increased collaboration and greater emphasis on functional endpoints can support broader uptake.
Middle East & Africa
The Middle East is expected to grow at a CAGR of 6.60% from 2025 to 2032, while Africa is projected to grow at a CAGR of 5.80% over the same period. Adoption is typically concentrated in select research-intensive universities, specialty programs, and centers with access to advanced instrumentation budgets. Growth is supported by gradual expansion of biomedical research capacity and increased interest in advanced cell models. However, procurement constraints and limited trained personnel can slow diffusion beyond top-tier institutions.
Competitive Landscape
Competition in the micro electrode array market is shaped by differentiation in electrode density, throughput design, and the usability of integrated software and analytics workflows. Vendors compete on the maturity of their ecosystem, including availability of plates/chips, stability and reproducibility of recordings, and the ease of integrating MEAs into standardized lab protocols. Product positioning often balances accessibility for broader academic deployment with premium performance for advanced neuroscience and screening workflows. Ongoing innovation also focuses on improving scalability and reducing operational complexity to widen adoption beyond specialist teams.
Axion BioSystems, Inc. has focused on expanding accessibility through workflow-oriented systems that can fit academic lab needs, including options positioned to lower adoption barriers. This approach supports wider installed-base growth and can strengthen downstream demand for consumables and software workflows. By aligning platform design with routine lab operations and training realities, the company can support repeat usage rather than episodic experimentation. Such positioning is particularly relevant in environments where procurement and ease-of-use strongly influence purchasing decisions.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- Axion BioSystems, Inc
- Multi Channel Systems MCS GmbH
- 3Brain AG
- NeuroNexus Technologies, Inc.
- Blackrock Neurotech
- MaxWell Biosystems AG
- Microprobes for Life Science
- MicruX Technologies
- Nanion Technologies GmbH
- BMSEED
- Alpha MED Scientific Inc.
- Others
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Developments
- In June 2025, Sony Semiconductor Solutions, SCREEN Holdings, and VitroVo announced a jointly developed trial microelectrode array system powered by high-density CMOS-MEA technology with approximately 237,000 electrodes, combining a new product introduction with a partnership focused on drug discovery and neuronal and cardiac disease research.
- In September 2024, Axion BioSystems and STEMCELL Technologies announced a strategic partnership that enabled STEMCELL to sell Axion’s Maestro Pro and Maestro Edge multielectrode array systems in North America and Europe, expanding access to MEA-based tools for neural and cardiac research.
Report Scope
| Report Attribute | Details |
| Market size value in 2025 | USD 1,067.91 million |
| Revenue forecast in 2032 | USD 1,991.35 million |
| Growth rate (CAGR) | 9.25% (2025–2032) |
| Base year | 2025 |
| Forecast period | 2025–2032 |
| Quantitative units | USD million |
| Segments covered | By Type Outlook: Planar MEAs, 3D MEAs, Flexible MEAs, High-density MEAs, Others; By Application Outlook: Neuroscience, Cardiovascular, Research, Drug Discovery, Tissue Engineering, Others; By End-user Outlook: Academic & Research Institutes, Pharmaceutical & Biotechnology Companies, Contract Research Organizations, Hospitals & Clinical Laboratories, Others; By Material Outlook: Glass, Polymer, Silicon, Ceramics, Others; By Channel Outlook: ~60 Channels, ~120 Channels, ~256 Channels, ~512 Channels, Others |
| Regional scope | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
| Key companies profiled | Axion BioSystems, Inc; Multi Channel Systems MCS GmbH; 3Brain AG; NeuroNexus Technologies, Inc.; Blackrock Neurotech; MaxWell Biosystems AG; Microprobes for Life Science; MicruX Technologies; Nanion Technologies GmbH; BMSEED; Alpha MED Scientific Inc.; Others |
| No. of Pages | 332 |
Segmentation
By Type
- Planar MEAs
- 3D MEAs
- Flexible MEAs
- High-density MEAs
- Others
By Application
- Neuroscience
- Cardiovascular
- Research
- Drug Discovery
- Tissue Engineering
- Others
By End-user
- Academic & Research Institutes
- Pharmaceutical & Biotechnology Companies
- Contract Research Organizations
- Hospitals & Clinical Laboratories
- Others
By Material
- Glass
- Polymer
- Silicon
- Ceramics
- Others
By Channel
- ~60 Channels
- ~120 Channels
- ~256 Channels
- ~512 Channels
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the Global Micro Electrode Array Market in 2025 and its forecast for 2032?
What is the CAGR for the Global Micro Electrode Array Market during 2025–2032?
What is the largest segment in the Global Micro Electrode Array Market?
What factors are driving growth in the Global Micro Electrode Array Market?
Which companies are leading in the Global Micro Electrode Array Market?
Which region is expected to grow the fastest in the Global Micro Electrode Array Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Micro Electrode Array Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2025; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Micro Electrode Array Market Snapshot
- 2.1.1 Market Size – Historical (2025) & Forecast (2025-2032) (2025: USD 1,067.91 million → 2032: USD 1,991.35 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Micro Electrode Array Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2025 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2025
- 2.3.2 Top 10 Players by Volume Share – 2025
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Micro Electrode Array Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Micro Electrode Array Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Micro Electrode Array Market Drivers
- 3.3 Micro Electrode Array Market Restraints & Challenges
- 3.4 Micro Electrode Array Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Micro Electrode Array Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Micro Electrode Array Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Micro Electrode Array category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Micro Electrode Array Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Micro Electrode Array Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2025)
- 5.1.2 Global Export Volume by Country (2025)
- 5.1.3 Global Import Value by Country (2025)
- 5.1.4 Global Import Volume by Country (2025)
- 5.1.5 Net Trade Balance by Country (2025)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2025)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Micro Electrode Array market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Micro Electrode Array Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2025
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Micro Electrode Array Market Share Analysis – 2025
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2025)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Micro Electrode Array Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Micro Electrode Array (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Micro Electrode Array Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Micro Electrode Array Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2025 & 2032)
- 7.1.2 Channel Mix Evolution (2025-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Micro Electrode Array Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Micro Electrode Array Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Micro Electrode Array Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Micro Electrode Array Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Micro Electrode Array Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Micro Electrode Array Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Micro Electrode Array Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
