
Market Overview
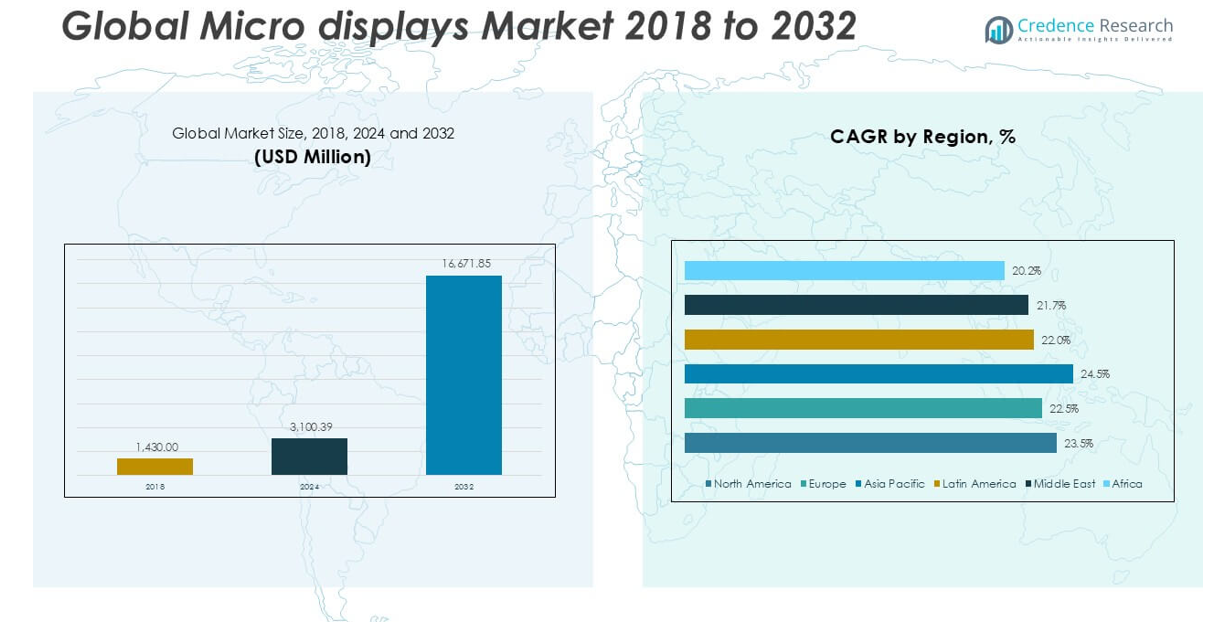
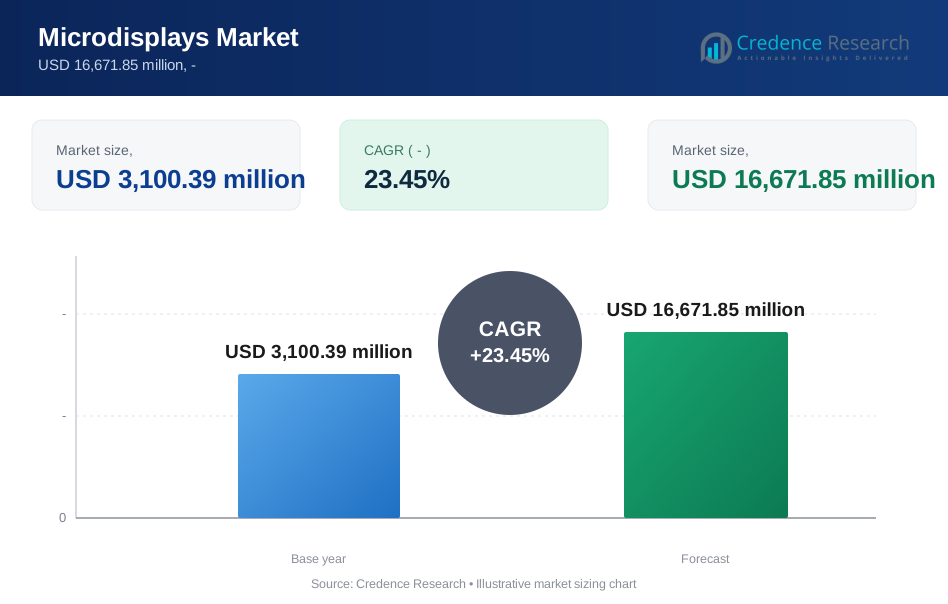
The Microdisplays Market size was valued at USD 1,430.00 million in 2018, reached USD 3,100.39 million in 2024, and is anticipated to reach USD 16,671.85 million by 2032, growing at a CAGR of 23.45% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Microdisplays Market Size 2024 | USD 3,100.39 million |
| Microdisplays Market, CAGR | 23.45% |
| Microdisplays Market Size 2032 | USD 16,671.85 million |
The microdisplays market is highly competitive, with key players such as LG Display Co., Ltd., eMagin (Samsung Display), Sony Corporation, Kopin, AUO Corporation, Micron Technology, Inc., Himax Technologies, Inc., Syndiant, Universal Display, and MicroVision driving innovation and market growth. These companies are focusing on advanced OLED, LCoS, and high-resolution technologies to meet the rising demand across AR/VR, military, medical, and consumer applications. Regionally, Asia-Pacific dominates the market, accounting for approximately 48.5% of the global share in 2024, supported by strong manufacturing capabilities, increasing adoption of AR/VR devices, and substantial investments from leading display manufacturers. North America and Europe follow, driven by technological advancements and growing defense applications.
Market Insights
- The Microdisplays market was valued at USD 1,430.00 million in 2018, reached USD 3,100.39 million in 2024, and is projected to reach USD 16,671.85 million by 2032, growing at a CAGR of 23.45% during the forecast period.
- Increasing demand for AR/VR devices in consumer electronics, military, and medical sectors is driving market growth, with the near-to-eye segment holding the largest share due to rising adoption in smart glasses and head-mounted displays.
- OLED microdisplays dominate the technology segment, supported by trends like miniaturization, high resolution, and lightweight design, while Asia-Pacific leads regionally with approximately 48.5% market share in 2024.
- The market faces challenges such as high production costs, limited battery life in portable devices, and competition from alternative display technologies like mini-LEDs.
- Key players including LG Display, Sony, eMagin, and Kopin are focusing on strategic partnerships, technological innovation, and expanding product portfolios to maintain competitiveness.
Market Segmentation Analysis:
By Product
In the microdisplays market, the Near-To-Eye segment holds the largest market share, accounting for a significant portion of the global revenue. This dominance is primarily driven by the rising adoption of near-to-eye devices in virtual reality (VR) and augmented reality (AR) applications across consumer electronics, healthcare, and military sectors. Increasing demand for compact, lightweight, and high-resolution displays for smart glasses, head-mounted displays, and AR/VR headsets further supports the growth of this segment. The Projection and Others segments continue to grow steadily but remain secondary to Near-To-Eye products in market influence.
- For instance, Sony Corporation’s ECX339A OLED microdisplay used in VR headsets offers a resolution of 1600 x 1200 pixels with a response time of 0.01 milliseconds, providing a significant advantage in reducing motion blur for near-to-eye applications.
By Application
Consumer Electronics emerged as the dominant application segment in the microdisplays market, capturing the largest market share. The growth is fueled by the rapid proliferation of AR/VR devices, smart glasses, and portable entertainment systems that rely on high-quality microdisplays for enhanced visual experiences. Military & Defense is another key application, driven by demand for head-mounted displays and advanced training simulators. Medical Applications, Industrial Systems, and Automotive segments also contribute to market expansion, but Consumer Electronics remains the primary driver due to escalating consumer interest and continuous advancements in immersive technologies.
- For instance, eMagin’s OLED microdisplays are widely used in consumer electronics and defense applications, offering brightness levels up to 5,000 nits, which supports superior visibility in both indoor and outdoor environments.
By Technology
The Organic Light-emitting Diode (OLED) segment leads the microdisplays market by technology, holding the largest market share due to its superior image quality, high contrast ratios, and flexibility. OLED microdisplays are widely preferred in near-to-eye applications for AR/VR headsets and smart glasses, offering thinner and lighter designs compared to LCD and LCoS alternatives. While Liquid Crystal Display (LCD) and Liquid Crystal on Silicon (LCoS) technologies remain relevant in cost-sensitive and projection applications, the growing demand for energy-efficient, high-resolution displays continues to drive OLED adoption as the dominant technology in this sector.
Market Overview
Rising Demand for AR/VR Devices
The microdisplays market is experiencing strong growth driven by the rising adoption of augmented reality (AR) and virtual reality (VR) devices across consumer and enterprise sectors. These devices rely heavily on high-performance microdisplays for immersive, high-resolution visual experiences. Increasing applications in gaming, healthcare, education, and industrial training are further fueling demand. As AR/VR technology becomes more affordable and accessible, microdisplays are poised to see sustained growth, particularly in head-mounted displays, smart glasses, and other near-to-eye systems.
- For instance, LG Display supplies high-resolution microdisplays with pixel densities exceeding 3,500 pixels per inch (ppi) for premium AR/VR devices, significantly enhancing visual clarity and reducing the screen door effect.
Technological Advancements in Display Technologies
Continuous advancements in display technologies, particularly OLED and LCoS microdisplays, are significantly propelling market growth. Improvements in brightness, resolution, energy efficiency, and miniaturization have made microdisplays more suitable for compact, high-performance devices. OLED microdisplays, in particular, offer superior contrast, faster response times, and reduced power consumption, enhancing their appeal for consumer electronics, medical imaging, and military applications. These innovations are expanding the capabilities of microdisplays, enabling their integration into a broader range of devices and driving market expansion.
- For instance, Kopin Corporation’s Lightning OLED microdisplays achieve refresh rates up to 120 Hz and support resolutions up to 2048 x 2048 pixels, which significantly enhances visual performance in fast-moving VR content.
Growing Military and Defense Applications
The microdisplays market is benefiting from increased adoption in military and defense applications, where they are integral to head-up displays (HUDs), night vision systems, and advanced training simulators. Microdisplays provide soldiers with real-time situational awareness, precision targeting, and enhanced field communications. Rising defense budgets and continuous investments in soldier modernization programs across various countries are further accelerating demand. The need for lightweight, durable, and high-resolution display solutions in rugged environments ensures that military applications remain a significant growth driver.
Key Trends & Opportunities
Expanding Use in Medical and Industrial Applications
Microdisplays are gaining traction in the medical and industrial sectors, creating new growth opportunities for market players. In healthcare, microdisplays support high-precision surgical procedures and diagnostic equipment, enhancing visualization for surgeons and specialists. In industrial settings, they are used in smart helmets, augmented reality tools for assembly lines, and training modules. The integration of microdisplays in these sectors improves accuracy, operational efficiency, and user experience, positioning them as valuable tools beyond traditional consumer markets.
- For instance, Kopin Corporation’s Pupil OLED microdisplay delivers a resolution of 1280 x 720 pixels with a brightness of 7000 nits, which is effectively used in medical headsets to provide clear, high-contrast images during minimally invasive surgeries and industrial inspection processes.
Rising Popularity of Wearable Smart Devices
The growing popularity of wearable smart devices, including smart glasses and fitness-focused AR tools, is presenting significant opportunities for the microdisplays market. Consumers increasingly seek compact, hands-free display solutions that offer real-time data visualization and interactive features. Technology companies are investing heavily in developing lighter, more energy-efficient wearable displays to meet this demand. The convergence of microdisplay innovation and the wearable device trend is expected to generate substantial growth potential in the coming years.
- For instance, AUO Corporation has introduced microdisplays with ultra-low power consumption below 30 milliwatts, specifically optimized for continuous-use smart glasses and other wearable applications.
Key Challenges
High Production Costs and Complex Manufacturing
One of the major challenges in the microdisplays market is the high production cost associated with advanced display technologies, particularly OLED and LCoS. Manufacturing microdisplays involves complex processes that demand precise engineering and quality control, leading to elevated production expenses. These costs can limit adoption in price-sensitive markets and restrict mass production. Addressing scalability and cost-efficiency remains essential for manufacturers aiming to broaden their consumer base and capitalize on emerging market opportunities.
Limited Battery Life in Portable Devices
Microdisplays, particularly those used in AR/VR headsets and wearable devices, often face the challenge of limited battery life. High-resolution displays with advanced functionalities tend to consume significant power, which can shorten device usage time and hinder user experience. Prolonged battery life is crucial for consumer adoption, especially in applications requiring extended periods of use. Manufacturers need to focus on energy-efficient designs and battery optimization to overcome this limitation and support wider market penetration.
Competition from Alternative Display Technologies
The microdisplays market faces increasing competition from alternative display technologies, such as mini-LED and direct-view displays, which offer high brightness and scalability at potentially lower costs. These technologies are making inroads in applications traditionally dominated by microdisplays, especially in projection and near-to-eye segments. As display technology continues to evolve rapidly, microdisplay manufacturers must continuously innovate to maintain their competitive edge and address the threat of technology substitution.
Regional Analysis
North America
In the Microdisplays market, North America accounted for USD 426.14 million in 2018 and is projected to reach USD 4,886.55 million by 2032, growing at a CAGR of 23.5%. The region holds approximately 29.3% market share in 2024, driven by the strong presence of key technology companies, increasing adoption of AR/VR devices, and expanding military applications. The growing use of microdisplays in consumer electronics, coupled with rising investments in advanced defense equipment and medical visualization tools, supports steady market growth. North America's focus on technological innovation and strategic partnerships continues to shape its competitive position in the global landscape.
Europe
Europe’s Microdisplays market was valued at USD 350.35 million in 2018 and is expected to reach USD 3,680.36 million by 2032, growing at a CAGR of 22.5%. In 2024, Europe holds 23.5% of the global market share. The region’s growth is supported by increasing demand for AR/VR devices in automotive, healthcare, and consumer sectors, along with rising defense investments. European companies are focusing on advanced display integration in smart glasses and head-up displays, particularly in luxury automotive brands. The market benefits from technological progress and supportive regulatory frameworks encouraging the adoption of innovative visual technologies.
Asia Pacific
Asia Pacific leads the Microdisplays market with a market size of USD 507.65 million in 2018, projected to reach USD 6,540.38 million by 2032, growing at a CAGR of 24.5%. The region holds the largest share, accounting for 36.6% of the global market in 2024. Growth is driven by high-volume manufacturing, increasing consumer adoption of AR/VR devices, and significant investments from major display producers. Countries like China, Japan, and South Korea dominate production and contribute to rapid regional growth. The expanding use of microdisplays in consumer electronics, military training, and wearable devices reinforces Asia Pacific’s market leadership.
Latin America
The Microdisplays market in Latin America was valued at USD 71.21 million in 2018 and is forecasted to reach USD 744.73 million by 2032, growing at a CAGR of 22.0%. Latin America represents 4.9% of the global market share in 2024. The region’s growth is supported by the increasing penetration of AR/VR technologies in consumer electronics and training applications across various industries. Governments and private sectors are gradually adopting advanced visual systems in healthcare and education. Although smaller in size compared to other regions, Latin America shows steady potential with expanding adoption in niche applications.
Middle East
The Middle East Microdisplays market was valued at USD 49.34 million in 2018 and is estimated to reach USD 476.91 million by 2032, with a CAGR of 21.7%. The region holds approximately 3.2% market share in 2024. Growth is supported by rising investments in defense and security sectors, where microdisplays are increasingly used in head-up displays, night vision systems, and advanced training solutions. Consumer electronics adoption is gradually rising, particularly in the premium product segment. The Middle East’s strategic investments in modernizing defense capabilities continue to drive the demand for high-performance microdisplays.
Africa
Africa’s Microdisplays market stood at USD 25.31 million in 2018 and is projected to reach USD 342.93 million by 2032, growing at a CAGR of 20.2%. Africa accounts for 2.4% of the global market share in 2024. Market growth is relatively slower compared to other regions due to limited technological infrastructure, but rising consumer interest in AR/VR devices and improving healthcare systems offer emerging opportunities. The increasing use of microdisplays in educational tools and defense applications is gradually enhancing market visibility. Africa’s microdisplays sector remains in its early growth phase, supported by incremental technology adoption.
Market Segmentations:
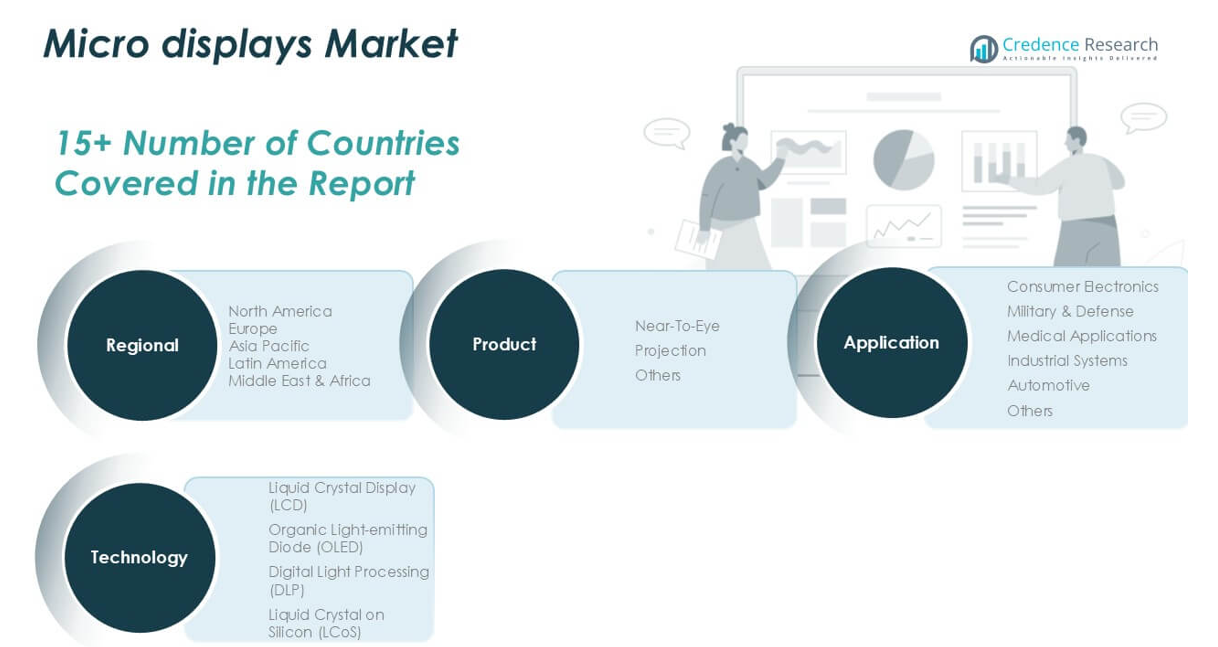
By Product
- Near-To-Eye
- Projection
- Others
By Application
- Consumer Electronics
- Military & Defense
- Medical Applications
- Industrial Systems
- Automotive
- Others
By Technology
- Liquid Crystal Display (LCD)
- Organic Light-emitting Diode (OLED)
- Digital Light Processing (DLP)
- Liquid Crystal on Silicon (LCoS)
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the microdisplays market is characterized by the presence of several key players actively focusing on technological advancements, strategic partnerships, and product innovation to strengthen their market positions. Leading companies such as LG Display Co., Ltd., Sony Corporation, eMagin (Samsung Display), and Kopin are heavily investing in research and development to offer high-resolution, energy-efficient, and compact microdisplay solutions tailored for AR/VR, military, medical, and consumer electronics applications. Strategic collaborations, mergers, and acquisitions are common as players seek to expand their product portfolios and geographic reach. Additionally, companies like AUO Corporation, Micron Technology, Inc., and Himax Technologies, Inc. are leveraging advancements in OLED and LCoS technologies to gain competitive advantages. Market competition is further intensified by the entry of innovative players like MicroVision and Universal Display, which are introducing cutting-edge display technologies. Overall, the market remains highly dynamic, with continuous innovation and evolving customer demands shaping the competitive strategies.
Key Player Analysis
- LG Display Co., Ltd.
- eMagin (Samsung Display)
- Sony Corporation
- KOPIN
- AUO Corporation
- Micron Technology, Inc.
- Himax Technologies, Inc.
- Syndiant
- Universal Display
- MicroVision
Recent Developments
- In April 2024, Kopin Corporation increased its customer base by winning the third production order for their Organic Light-Emitting Diode (OLED) microdisplays. These screens will be used in the Indian Army's mounted and handheld thermal imaging vision systems. According to the terms of the most recent production order, which comprises approximately 1,200 units, deliveries will take place over a six-month period.
- In June 2024, LG Display, an innovation-based organization operating in display technologies, announced the beginning of mass production for the world's first 13-inch Tandem OLED panel of laptops. The company is focusing on the OLED market by utilizing the superior performance and reduced power consumption of Tandem OLED technology.
- In February 2024, Kopin Corporation received a new Small Business Innovation Research (SBIR) contract from the Naval Air Warfare Center. Under this contract, Kopin will use its over 30-years of experience in US-based microdisplay research to produce superior microdisplays for lens less computational imaging.
- In August 2023, Sony Semiconductor Solutions Corporation (SSS) launched the ECX344A, high-definition 1.3-type OLED microdisplay with 4K resolution that is intended to give more realistic space recreations which are designed specifically for AR/VR applications.
- In January 2023, Seiko Epson and Universal Display entered into an agreement for researching OLEDs. Universal Display will provide Epson with its unique phosphorescent OLED materials and technology for AR/VR (augmented reality/virtual reality) display applications under the terms of the agreement.
Market Concentration & Characteristics
The Microdisplays Market demonstrates a moderately concentrated structure, with a few key players holding significant market shares due to their strong technological capabilities and established distribution networks. It is characterized by rapid innovation, high entry barriers, and a strong focus on research and development. The market demands consistent advancements in resolution, power efficiency, and compactness to meet the evolving needs of consumer electronics, defense, medical, and industrial applications. Price sensitivity, especially in consumer segments, and the complexity of manufacturing processes create substantial competitive pressure. Companies actively pursue strategic partnerships, product diversification, and regional expansions to strengthen their positions. The Microdisplays Market relies heavily on OLED and LCoS technologies, which require significant investment and technical expertise, limiting the number of viable new entrants. It maintains a dynamic competitive environment driven by evolving user expectations for high-performance, lightweight, and energy-efficient displays.
Report Coverage
The research report offers an in-depth analysis based on Product, Application, Technology and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Microdisplays Market will continue to grow driven by increasing demand for AR and VR devices across consumer and enterprise sectors.
- OLED microdisplays will remain the preferred technology due to their superior image quality and energy efficiency.
- The adoption of microdisplays in wearable smart devices will increase significantly, supporting the growth of compact and portable solutions.
- Military and defense applications will generate steady demand for microdisplays in head-up displays, night vision equipment, and advanced training systems.
- Healthcare will emerge as a key sector, with microdisplays supporting precision diagnostics and surgical visualization tools.
- Manufacturers will invest in improving power efficiency and battery optimization to enhance the usability of portable devices.
- Asia-Pacific will maintain its position as the leading regional market supported by strong production capabilities and high consumer adoption.
- Companies will focus on reducing production costs and simplifying manufacturing processes to expand their customer base.
- Competition from alternative display technologies like mini-LEDs will continue to challenge microdisplay manufacturers.
- Strategic partnerships and technological innovations will shape the long-term competitive landscape of the market.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Proliferation of AR/VR Devices
The rapid adoption of AR/VR headsets, smart glasses, and other near-to-eye devices in consumer electronics, healthcare, and military sectors is fueling demand for high-resolution, compact microdisplays that enable immersive visual experiences.
Advancements in OLED and LCoS Technologies
Continuous improvements in OLED and LCoS microdisplays, such as higher brightness, better energy efficiency, and miniaturization, are making microdisplays more suitable for a wide range of applications, driving market expansion.
Rising Military and Defense Applications
Increased use of microdisplays in head-up displays, night vision systems, and advanced training simulators for military and defense purposes is generating steady demand, supported by rising defense budgets and modernization programs.
Growth in Wearable Smart Devices
The surge in wearable technology, including smart glasses and fitness-focused AR tools, is creating new opportunities for microdisplays, as consumers seek lightweight, energy-efficient, and high-performance display solutions for real-time data visualization.
Expansion into Medical and Industrial Sectors
Microdisplays are increasingly being integrated into medical imaging equipment and industrial tools, supporting high-precision diagnostics, surgical visualization, and augmented reality applications that enhance operational efficiency and accuracy.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Microdisplays Market?
What are the key segments within the Microdisplays Market?
What are some challenges faced by the Microdisplays Market?
Who are the major players in the Microdisplays Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Near-To-Eye
- 1.2.2 Projection
- 1.2.3 Others
- 1.3 By Technology
- 1.3.1 Liquid Crystal Display (LCD)
- 1.3.2 Organic Light-emitting Diode (OLED)
- 1.3.3 Digital Light Processing (DLP)
- 1.3.4 Liquid Crystal on Silicon (LCoS)
- 1.4 By Application
- 1.4.1 Consumer Electronics
- 1.4.2 Military & Defense
- 1.4.3 Medical Applications
- 1.4.4 Industrial Systems
- 1.4.5 Automotive
- 1.4.6 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2018: USD 3,100.39 million → 2032: USD 16,671.85 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2018
- 2.6.2 Forecast Period: 2018-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2018
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Microdisplays Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Microdisplays Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2018-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2018-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Microdisplays Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2018-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Microdisplays Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Microdisplays Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Microdisplays Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Microdisplays Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Microdisplays Market Outlook, 2018-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2018: USD 3,100.39 million → 2032: USD 16,671.85 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2018
- 11.2 Market Forecast, 2018-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Microdisplays Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2018
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2018-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2018-2032
- 12.3.4 Volume Forecast, 2018-2032
- 12.3.5 Base-Year Market Share, 2018
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Near-To-Eye
- 12.3.7.2 Projection
- 12.3.7.3 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2018-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2018-2032
- 12.4.4 Volume Forecast, 2018-2032
- 12.4.5 Base-Year Market Share, 2018
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Liquid Crystal Display (LCD)
- 12.4.7.2 Organic Light-emitting Diode (OLED)
- 12.4.7.3 Digital Light Processing (DLP)
- 12.4.7.4 Liquid Crystal on Silicon (LCoS)
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2018-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2018-2032
- 12.5.4 Volume Forecast, 2018-2032
- 12.5.5 Base-Year Market Share, 2018
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Consumer Electronics
- 12.5.7.2 Military & Defense
- 12.5.7.3 Medical Applications
- 12.5.7.4 Industrial Systems
- 12.5.7.5 Automotive
- 12.5.7.6 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Microdisplays End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Microdisplays Geographic Market Outlook, 2018-2032
- 14.1 Regional Market Size and Share, 2018
- 14.2 Regional Market Forecast, 2018-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Microdisplays Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2018-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Microdisplays Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2018
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2018-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 LG Display Co., Ltd.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Sony Corporation
- 18.4 eMagin (Samsung Display)
- 18.5 Kopin
- 18.6 AUO Corporation
- 18.7 Micron Technology, Inc.
- 18.8 Himax Technologies, Inc.
- 18.9 Syndiant
- 18.10 Universal Display
- 18.11 MicroVision
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

