
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Military Aircraft Avionics Market Size 2024 | USD 37165 Million |
| Military Aircraft Avionics Market, CAGR | 3.74% |
| Military Aircraft Avionics Market Size 2032 | USD 49854.46 Million |
Market Overview:
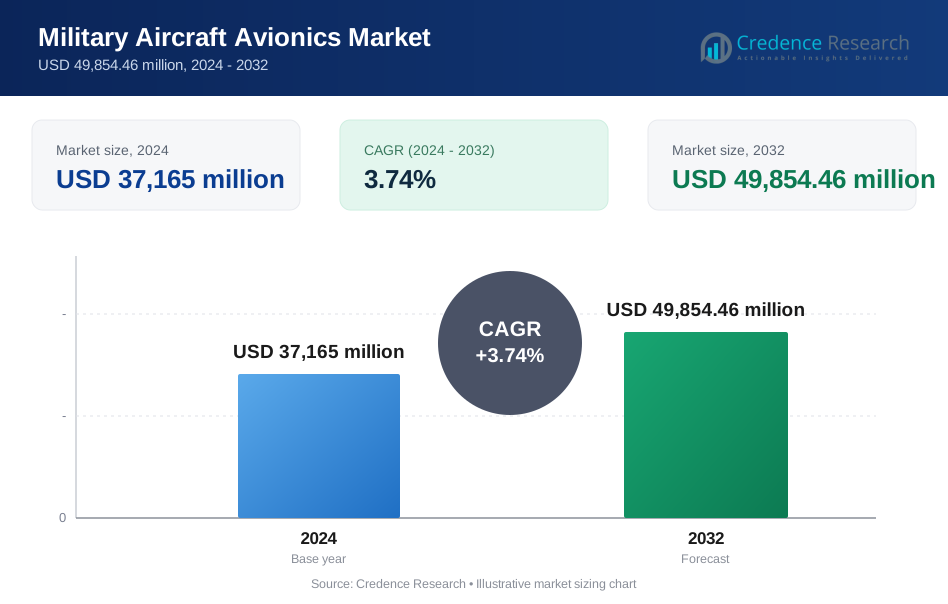
The Military Aircraft Avionics Market is projected to grow from USD 37165 million in 2024 to an estimated USD 49854.46 million by 2032, with a compound annual growth rate (CAGR) of 3.74% from 2024 to 2032.
The primary drivers of the military aircraft avionics market include heightened geopolitical tensions, increased defense spending by emerging and established military powers, and rapid technological advancements in avionics systems. Military forces globally are focusing on upgrading their fleets with advanced avionics to improve situational awareness, real-time data communication, and precision targeting. The demand for unmanned aerial vehicles (UAVs) and autonomous systems, which require sophisticated avionics, is also contributing to market growth. Moreover, innovations in electronic warfare (EW) systems, enhanced radar and surveillance capabilities, and the need for integrated avionics to support multi-role combat aircraft are further boosting the market. Governments are increasingly emphasizing the modernization of military aircraft to ensure air superiority and operational effectiveness in complex, dynamic battlefields.
North America holds the largest share of the military aircraft avionics market, driven by significant investments in military modernization programs by the United States, which leads in both procurement and development of advanced avionics systems. Europe follows closely, with countries like the UK, France, and Germany focusing on upgrading their defense capabilities in response to increasing security threats. The Asia-Pacific region is witnessing rapid growth, particularly in countries such as China, India, and Japan, where rising defense budgets and expanding military forces are fueling demand for state-of-the-art avionics systems. The Middle East and Africa also present potential growth opportunities, with increasing defense procurement initiatives in countries like Saudi Arabia and the UAE aiming to strengthen their air capabilities amidst regional conflicts.
Market Drivers:
Increased Defense Budgets and Geopolitical Tensions:
One of the key drivers of the military aircraft avionics market is the significant rise in defense budgets globally, driven by escalating geopolitical tensions and the need for modernized military forces. Nations are increasingly focused on strengthening their air forces to maintain strategic superiority and national security. For instance, The United States leads global defense spending, with India's defense budget reaching Rs 621,540.85 crore (approximately $74.7 billion) in 2024-25, constituting 13.04% of its total Union Budget. The growing emphasis on high-tech warfare, which requires advanced avionics for precision strikes, surveillance, and secure communication, is pushing defense ministries to invest heavily in upgrading their fleets. As a result, procurement of new aircraft equipped with state-of-the-art avionics systems has become a priority for several countries, particularly those involved in regional conflicts or engaged in military alliances like NATO.
Technological Advancements in Avionics Systems:
The rapid advancement in avionics technology is another significant factor driving the market. Modern avionics systems offer improved navigation, communication, and flight control capabilities, which enhance the overall efficiency and safety of military aircraft. These systems provide real-time data analysis, enabling pilots to make quick decisions in complex and dynamic combat environments. The integration of artificial intelligence (AI), machine learning (ML), and data analytics is further revolutionizing military avionics, enabling predictive maintenance, automated flight controls, and enhanced situational awareness. As technology continues to evolve, the demand for highly advanced and integrated avionics systems in military aircraft is expected to grow exponentially.
Rising Demand for Unmanned Aerial Vehicles (UAVs):
The increasing adoption of unmanned aerial vehicles (UAVs) in military operations is a critical driver for the military aircraft avionics market. UAVs rely heavily on sophisticated avionics systems to operate autonomously or remotely, ensuring precise navigation, communication, and mission execution. These aircraft are used for a range of applications, including surveillance, reconnaissance, and targeted strikes, especially in regions where direct human involvement may be too risky. As military forces worldwide shift towards integrating more UAVs into their fleets, the demand for advanced avionics systems that support autonomous operations is expected to rise. This trend is particularly prominent in countries with advanced military capabilities, such as the United States, China, and Israel.
Focus on Electronic Warfare (EW) and Cybersecurity:
The increasing importance of electronic warfare (EW) and cybersecurity in modern military strategies is also driving the demand for advanced avionics systems. Avionics systems in military aircraft play a crucial role in electronic warfare by detecting, disrupting, and neutralizing enemy radar and communication systems. For example, The United States has invested approximately $5 billion in electronic warfare technology in 2024 alone, representing 45% of global expenditure in this sector. These capabilities are essential for ensuring air superiority and protecting military assets from hostile attacks. Additionally, the growing threat of cyberattacks on defense systems has led to a greater focus on developing secure avionics systems with robust cybersecurity measures. This ensures that critical avionics systems remain functional and protected against potential breaches. As electronic warfare and cybersecurity continue to be central to military strategies, the demand for avionics systems capable of supporting these operations will continue to rise.
Market Trends:
Integration of Artificial Intelligence and Machine Learning in Avionics:
One of the prominent trends shaping the military aircraft avionics market is the integration of artificial intelligence (AI) and machine learning (ML) technologies. These advanced technologies are being used to enhance the capabilities of avionics systems, particularly in areas such as real-time data processing, automated decision-making, and predictive maintenance. AI-powered avionics systems can analyze vast amounts of data collected from sensors and radar in real-time, providing pilots with enhanced situational awareness and allowing for faster, more accurate decision-making in combat scenarios. Moreover, the incorporation of machine learning enables avionics systems to identify patterns and predict maintenance needs, reducing downtime and increasing the operational readiness of military aircraft.
Growing Adoption of Autonomous and Unmanned Systems:
The increasing reliance on autonomous systems and unmanned aerial vehicles (UAVs) is another significant trend driving the military aircraft avionics market. Military forces around the world are investing in UAVs and autonomous aircraft for various missions, such as surveillance, reconnaissance, and strike operations, due to their ability to operate in high-risk environments without endangering human lives. For instance, The U.S. military operates an extensive fleet of unmanned systems, including 7,362 RQ-11 Ravens, 246 MQ-1 Predators, 126 MQ-9 Reapers, and 33 RQ-4 Global Hawks. These systems require sophisticated avionics for navigation, flight control, and communication, as well as advanced sensors and data link systems to ensure mission success. As the use of UAVs continues to expand, there is a growing demand for avionics solutions that support autonomous operations, including systems capable of operating in contested or GPS-denied environments.
Emphasis on Cybersecurity in Avionics Systems:
With the increasing digitalization of avionics systems, cybersecurity has become a critical focus in the military aircraft avionics market. Modern military avionics systems are highly interconnected and rely on a variety of data links and communication networks, making them vulnerable to cyber threats. As a result, defense organizations are placing greater emphasis on the development of avionics systems with enhanced cybersecurity measures to protect against potential cyberattacks. These measures include encryption of communication systems, secure data transfer protocols, and systems capable of detecting and mitigating cyber intrusions in real time. The growing concern over cyber warfare and the need to protect critical avionics infrastructure is driving the demand for secure, resilient avionics systems.
Advancements in Electronic Warfare Capabilities:
Electronic warfare (EW) has become increasingly important in modern military operations, and advancements in EW capabilities are shaping the future of military aircraft avionics. Avionics systems are playing a key role in enabling aircraft to detect, jam, and neutralize enemy radar, communication, and electronic systems. With the evolution of EW tactics and technologies, avionics systems are becoming more sophisticated, featuring integrated electronic support measures (ESM), electronic countermeasures (ECM), and electronic attack (EA) capabilities. These advancements allow military aircraft to conduct operations in highly contested environments, ensuring the success of missions while minimizing the risk of detection or engagement by enemy forces. For instance, Boeing and BAE Systems are at the forefront of implementing advanced electronic warfare capabilities through the F-15 Eagle Passive/Active Warning and Survivability System (EPAWSS). This $824.7 million program replaces analog systems with digital integrated EW suites, enabling F-15s to operate effectively in dense radio-frequency environments. The ongoing development of electronic warfare capabilities is expected to continue driving demand for advanced avionics systems.
Market Restraints and Challenges:
High Development and Procurement Costs:
One of the key restraints in the military aircraft avionics market is the high cost associated with the development and procurement of advanced avionics systems. Military avionics require state-of-the-art technology, rigorous testing, and compliance with stringent safety and performance standards. The cost of integrating such complex systems into military aircraft, including hardware and software upgrades, can be prohibitively expensive for many defense budgets, particularly for smaller or developing nations. Additionally, the long development cycles and high research and development (R&D) expenses often delay procurement timelines, further challenging the affordability of these systems.
Stringent Regulatory and Certification Requirements:
Another challenge in the military aircraft avionics market is the strict regulatory environment and the complexity of obtaining certifications. Military avionics systems must meet rigorous safety, reliability, and performance standards, which vary by country and region. The certification process can be time-consuming and costly, as it involves multiple stages of testing and validation to ensure the system's safety and effectiveness in combat operations. Any delays or failures in meeting these regulatory requirements can slow down the deployment of new avionics systems, impacting the overall market growth.
Cybersecurity Vulnerabilities and Emerging Threats:
Cybersecurity is an ongoing challenge for the military aircraft avionics market. As avionics systems become increasingly digitized and interconnected, they are more vulnerable to cyberattacks and electronic warfare. While there is a growing focus on developing secure avionics systems, the constantly evolving nature of cyber threats poses significant challenges to maintaining robust cybersecurity measures. The complexity of protecting avionics systems from hacking, jamming, and other cyber threats requires continuous investment in cybersecurity solutions, which can be resource-intensive for defense organizations. This vulnerability may hinder the adoption of certain digital avionics technologies in highly sensitive or contested environments.
Market Segmentation Analysis:
By aircraft type, fixed-wing combat aircraft dominate the market, driven by their critical role in offensive and defensive military operations. These aircraft rely heavily on advanced avionics for navigation, communication, and electronic warfare. Fixed-wing non-combat aircraft, such as transport and refueling planes, also contribute significantly to the market, particularly for missions requiring long-range capabilities. The demand for avionics in helicopters is increasing, as rotary-wing aircraft are widely used for surveillance, transport, and combat support. Meanwhile, the expanding use of unmanned aerial vehicles (UAVs) in reconnaissance and strike missions is fueling a surge in demand for advanced avionics designed to support autonomous and remote-controlled operations.
By subsystem type, the flight control system segment is crucial, as it ensures safe and efficient aircraft operations. The communication system is essential for real-time data exchange in complex combat environments, while the navigation system enhances the precision of flight paths and targeting. The monitoring system plays a critical role in maintaining aircraft performance by providing real-time diagnostics.
By end use, the market is divided into OEM (Original Equipment Manufacturer) and aftermarket segments. The OEM segment dominates, driven by the continuous demand for new aircraft equipped with modern avionics. The aftermarket segment is also vital, as military forces require regular upgrades and maintenance to keep their fleets combat-ready, ensuring a steady demand for avionics replacements and enhancements.
Segmentation:
By Aircraft Type:
- Fixed-wing Combat Aircraft
- Fixed-wing Non-Combat Aircraft
- Helicopters
- Unmanned Aerial Vehicles (UAVs)
By Subsystem Type:
- Flight Control System
- Communication System
- Navigation System
- Monitoring System
By End Use:
- OEM
- Aftermarket
Based on Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds the largest share of the global military aircraft avionics market, accounting for approximately 35% of the market. This dominance is primarily driven by the United States, which is the world's largest defense spender. The U.S. government allocates substantial funding for the development and procurement of advanced military avionics systems as part of its broader military modernization efforts. The country’s extensive fleet of fixed-wing combat and non-combat aircraft, helicopters, and unmanned aerial vehicles (UAVs) necessitates continuous avionics upgrades. Additionally, the presence of major defense contractors and avionics manufacturers such as Lockheed Martin, Boeing, and Northrop Grumman further strengthens North America's leadership in the market. Canada also contributes to regional growth, with ongoing investments in aircraft modernization and procurement programs.
Europe
Europe represents around 25% of the global military aircraft avionics market share. The region's market is driven by rising defense spending in response to increasing security threats and geopolitical tensions, particularly in Eastern Europe. Countries such as the United Kingdom, France, and Germany are heavily investing in upgrading their military aircraft fleets with advanced avionics systems. These nations are focusing on both fixed-wing combat aircraft and helicopters, enhancing their navigation, communication, and electronic warfare capabilities. Additionally, initiatives like the European Defense Fund and joint programs such as the Future Combat Air System (FCAS) are promoting technological advancements in avionics across the region. Emerging threats from neighboring regions have accelerated the need for advanced avionics solutions, particularly in electronic warfare and cyber defense.
Asia-Pacific
The Asia-Pacific region is the fastest-growing market for military aircraft avionics, with a market share of approximately 22%. The growth is driven by rising defense budgets in major countries such as China, India, and Japan. China, in particular, is heavily investing in modernizing its military capabilities, including avionics systems for its expanding fleet of fixed-wing aircraft, helicopters, and UAVs. India is also focusing on upgrading its aging aircraft fleet with advanced avionics systems as part of its broader military modernization efforts. Japan's increasing defense expenditure, particularly in response to regional security challenges, is contributing to the demand for sophisticated avionics systems. The ongoing territorial disputes and geopolitical instability in the Asia-Pacific region are compelling nations to prioritize air defense capabilities, further driving market growth.
Middle East and Africa
The Middle East and Africa region accounts for around 12% of the military aircraft avionics market share. In the Middle East, countries such as Saudi Arabia, the United Arab Emirates, and Israel are leading the market, driven by substantial defense investments and the need to counter regional security threats. These nations are procuring advanced combat aircraft and UAVs, which require cutting-edge avionics systems. In Africa, defense modernization programs are more limited, but countries like South Africa and Egypt are investing in upgrading their aircraft fleets with new avionics technologies. Regional conflicts and the need for stronger air defense capabilities are driving demand for avionics systems, particularly in electronic warfare and communication subsystems.
Key Player Analysis:
- Aspen Avionics (US),
- Avidyne (US),
- Curtiss-Wright (US),
- Elbit Systems (Israel),
- ENSCO Avionics (US),
- ForeFlight (US),
- GE Aviation (US),
- Hilton Software (US),
- Honeywell (US),
- L-3 Avionics Systems (US),
- Rockwell Collins (US),
- Sagetech (US),
- Thales Group (France),
- Xavion (US),
- Zodiac Aerospace (France).
Competitive Analysis:
The military aircraft avionics market is highly competitive, with key players continuously innovating to maintain a technological edge. Major defense contractors such as Lockheed Martin, Northrop Grumman, BAE Systems, and Thales Group dominate the market, benefiting from long-term defense contracts and government support. These companies invest heavily in research and development to create cutting-edge avionics solutions, focusing on advancements in communication systems, flight control, and electronic warfare capabilities. Smaller firms and specialized avionics manufacturers also play a significant role by providing niche solutions and integrating emerging technologies such as artificial intelligence and cybersecurity measures into avionics systems. Strategic partnerships, mergers, and acquisitions are common as companies seek to expand their portfolios and enhance their capabilities. The market's competitiveness is further intensified by regional players, particularly in Asia-Pacific, where governments are fostering domestic avionics development to reduce dependence on foreign suppliers.
Recent Developments:
- In March 2024, the Indian Ministry of Defence (MoD) awarded a USD 346.7 million contract to Hindustan Aeronautics Limited (HAL) for the mid-life upgrade of 25 Dornier aircraft and related equipment for the Indian Navy. This upgrade aims to extend the operational life of the aircraft while enhancing their performance and capabilities to support naval operations.
- Also, in March 2024, South Korea's Defense Acquisition Program Administration (DAPA) announced plans to invest USD 2.9 billion to upgrade the radar systems and long-range mission capabilities of its F-15K Eagle fleet. As part of this enhancement program, the aircraft will be equipped with AN/APG-82 electronic scanning radar, BAE Systems' AN/ALQ-250 Eagle Passive Active Warning Survivability System, and a new large-area cockpit display to boost situational awareness and operational effectiveness. These upgrades are expected to significantly enhance the fleet's combat readiness and survivability in complex mission environments.
Market Concentration & Characteristics:
The military aircraft avionics market is moderately concentrated, with a few major players holding a significant share of the global market. Companies such as Lockheed Martin, Northrop Grumman, Thales Group, and BAE Systems dominate due to their established expertise, extensive R&D capabilities, and long-standing defense contracts. However, regional manufacturers, particularly in Asia-Pacific, are emerging as competitive players, driven by government-backed initiatives to develop domestic defense industries. The market is characterized by high entry barriers due to the substantial capital investment required for research, development, and compliance with stringent regulatory standards. Additionally, long development cycles and the need for secure, technologically advanced systems further limit new entrants. Innovation in avionics, particularly in areas such as artificial intelligence, cybersecurity, and electronic warfare, remains a critical focus, as military forces demand increasingly sophisticated systems to maintain operational superiority in modern warfare.
Report Coverage:
The research report offers an in-depth analysis based on By Aircraft Type, By Subsystem Type and By End Use. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Increasing defense budgets worldwide will drive demand for advanced military avionics systems.
- Rapid advancements in AI and machine learning will enhance avionics capabilities, improving real-time data processing and automation.
- The rising adoption of UAVs and autonomous aircraft will create new opportunities for specialized avionics solutions.
- Growing emphasis on electronic warfare and cybersecurity will push demand for avionics with enhanced security features.
- Ongoing modernization programs in major military powers will lead to higher procurement of next-generation avionics systems.
- The shift towards integrated avionics suites will increase as military forces seek seamless communication and coordination across platforms.
- Emerging regional markets, particularly in Asia-Pacific, will experience rapid growth due to expanding defense investments.
- High development and maintenance costs will remain a challenge, potentially slowing down adoption in some regions.
- Collaboration between defense contractors and technology firms will drive innovation in avionics systems.
- The aftermarket segment will see steady growth as fleets undergo continuous upgrades and maintenance to meet evolving mission needs.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Military Aircraft Avionics Market?
What are the key drivers of market growth?
Which region holds the largest market share?
What challenges does the market face?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Military Aircraft Avionics Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Military Aircraft Avionics Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 37,165 million → 2032: USD 49,854.46 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Military Aircraft Avionics Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Military Aircraft Avionics Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Military Aircraft Avionics Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Military Aircraft Avionics Market Drivers
- 3.3 Military Aircraft Avionics Market Restraints & Challenges
- 3.4 Military Aircraft Avionics Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Military Aircraft Avionics Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Military Aircraft Avionics Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Military Aircraft Avionics category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Military Aircraft Avionics Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Military Aircraft Avionics Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Military Aircraft Avionics market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Military Aircraft Avionics Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Military Aircraft Avionics Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Military Aircraft Avionics Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Military Aircraft Avionics (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Military Aircraft Avionics Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Military Aircraft Avionics Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Military Aircraft Avionics Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Military Aircraft Avionics Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Military Aircraft Avionics Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Military Aircraft Avionics Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Military Aircraft Avionics Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Military Aircraft Avionics Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Military Aircraft Avionics Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
