
Market Overview
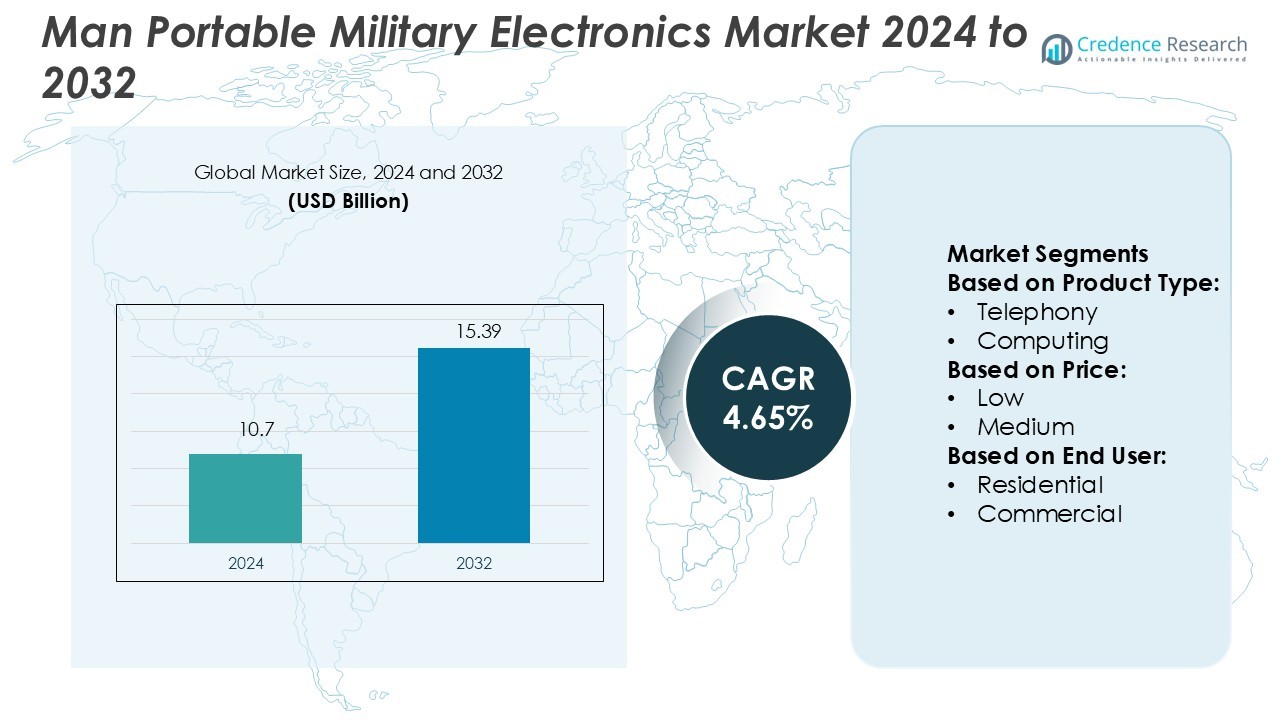
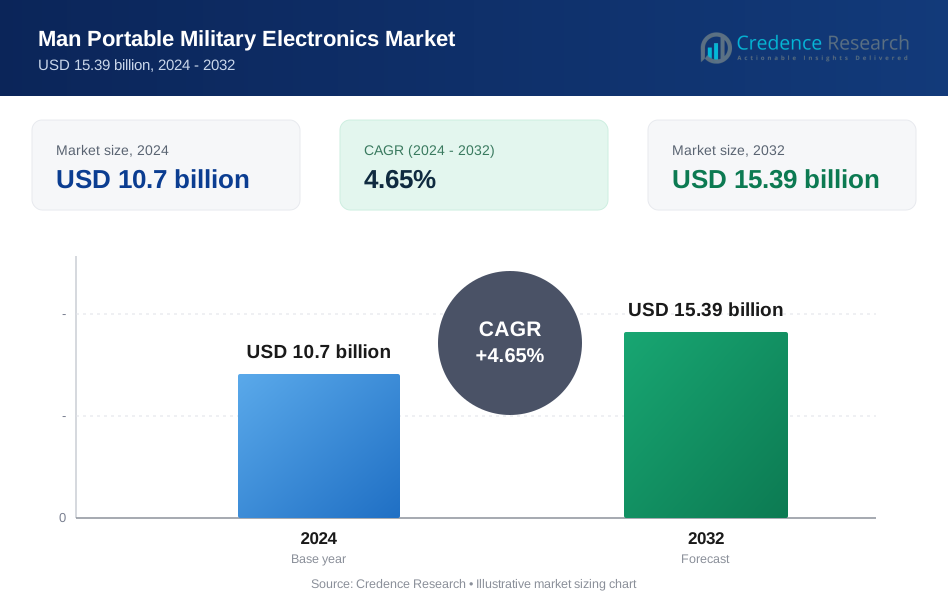
Man Portable Military Electronics Market size was valued USD 10.7 billion in 2024 and is anticipated to reach USD 15.39 billion by 2032, at a CAGR of 4.65% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Man Portable Military Electronics Market Size 2024 | USD 10.7 Billion |
| Man Portable Military Electronics Market, CAGR | 4.65% |
| Man Portable Military Electronics Market Size 2032 | USD 15.39 Billion |
The man-portable military electronics market is led by prominent players such as Indra Sistemas S.A., Honeywell International Inc., Bharat Electronics Limited, Hensoldt, Israel Aerospace Industries (IAI), Curtiss-Wright Corporation, Elbit Systems Ltd., Aselsan A.S., General Dynamics Corporation, and BAE Systems PLC. These companies dominate through continuous innovation in communication, surveillance, and navigation technologies tailored for modern warfare. Their focus on miniaturization, durability, and AI-driven systems strengthens their competitive positions globally. North America leads the market with a 38% share, driven by extensive defense spending, rapid adoption of advanced soldier systems, and ongoing modernization programs supporting battlefield connectivity and situational awareness.
Market Insights
- The man-portable military electronics market was valued at USD 10.7 billion in 2024 and is projected to reach USD 15.39 billion by 2032, growing at a CAGR of 4.65%.
- Rising demand for lightweight, portable communication and surveillance systems drives market expansion across defense sectors.
- Technological advancements such as AI integration, miniaturization, and real-time data connectivity are shaping market trends.
- The market faces restraints from high production costs, cybersecurity concerns, and complex maintenance requirements of advanced systems.
- North America dominates with a 38% share, while the telephony segment leads with 32%, supported by growing defense modernization programs and battlefield digitization initiatives.Top of Form
Market Segmentation Analysis:
By Product Type
The telephony segment dominates the man-portable military electronics market with a 32% share. This dominance stems from the growing demand for secure and real-time battlefield communication systems. Portable communication units, including encrypted radios and satellite phones, provide critical data sharing and coordination capabilities for ground troops. Advancements in lightweight and ruggedized telephony systems enhance operational mobility and reliability in combat zones. Increasing adoption of software-defined radios and network-centric communication further boosts segment growth.
- For instance, Indra Sistemas, S.A. signed an agreement with Bittium Corporation in July 2025 to cooperate in development of a tactical Software-Defined Radio (SDR) solution, leveraging 15 years of Indra’s SDR waveform expertise and 40 years of Bittium’s tactical radio technology.
By Price
The medium-priced segment holds the largest share of 46%, driven by balanced cost-effectiveness and performance. These products offer advanced communication, surveillance, and navigation capabilities without the high costs of premium systems. Defense agencies in emerging economies prefer medium-tier solutions to modernize infantry systems within limited budgets. Growing procurement of mid-range rugged laptops, portable sensors, and drones for tactical operations reinforces this dominance. The segment’s reliability and versatility make it suitable for both training and field deployment.
- For instance, Honeywell offers the TALIN Marine Inertial Navigation System (MINS) featuring ring-laser gyros and accelerometers. More than 15,000 units are deployed across land, air and sea applications.
By End User
The commercial segment leads the market with a 57% share, fueled by technological adaptation for defense contracts and private security operations. Commercial entities develop and supply advanced handheld systems, surveillance drones, and communication tools to military clients. Dual-use technologies, such as ruggedized tablets and autonomous drones, are increasingly integrated into defense applications. Collaboration between defense departments and private companies enhances innovation speed and operational efficiency. The growing use of commercial off-the-shelf (COTS) products further strengthens market expansion.
Key Growth Drivers
Rising Demand for Portable Communication Systems
The increasing need for real-time communication and situational awareness drives demand for portable communication devices. Advanced radios, satellite phones, and secure telephony systems enable seamless coordination among forces in remote or hostile terrains. Modern troops rely on lightweight and durable devices supporting high-speed data transfer and encrypted channels. Growing defense modernization programs and investments in battlefield digitization further strengthen this segment’s adoption, enhancing tactical responsiveness and mission success rates across defense forces globally.
- For instance, BEL has developed a high-frequency man-pack version of a Software Defined Radio (HF SDR) operating in the 1.5–30 MHz band, with maximum transmit power of 20 W.
Advancements in Miniaturization and Battery Technology
Technological progress in compact electronics and efficient power systems accelerates the growth of man-portable devices. Lightweight components with extended battery life improve soldier mobility and endurance during missions. Enhanced lithium-ion and solid-state battery solutions ensure longer operation times without frequent recharging. Continuous innovation in energy efficiency allows integration of computing, surveillance, and navigation tools into smaller form factors. These developments enable multi-functionality and portability, aligning with modern warfare requirements emphasizing agility and sustained field operations.
- For instance, HENSOLDT’s GMJ9500 man-portable RCIED jammer family offers full-spectrum jamming from 20 MHz to 6000 MHz. The system is described as “lightweight, modular and man-portable”, enabling infantry or EOD teams to deploy it in the field.
Government Investments and Modernization Programs
Increasing defense spending and government-backed modernization initiatives fuel market expansion. Military forces worldwide are upgrading outdated systems with network-enabled and interoperable man-portable electronics. Programs focusing on communication, intelligence, and surveillance modernization drive procurement of advanced tactical gear. Nations such as the U.S., China, and India are emphasizing soldier digitalization projects integrating real-time data and command systems. These efforts enhance battlefield efficiency and security, propelling steady demand for next-generation portable electronic solutions.
Key Trends & Opportunities
Integration of Artificial Intelligence and IoT
AI and IoT are transforming the capabilities of man-portable electronics by enabling predictive analytics and autonomous operations. Smart sensors and AI-driven decision systems enhance target identification, terrain mapping, and data interpretation. IoT connectivity allows seamless communication between devices, optimizing mission coordination and logistics. Defense agencies increasingly deploy intelligent drones and wearables to improve real-time monitoring and response. This trend opens opportunities for innovation in connected soldier ecosystems and AI-embedded tactical solutions.
- For instance, CW’s DuraCOR 312 ultra-small form factor mission computer features six Armv8 processor cores and a 256-core Pascal/CUDA GPU, delivering up to 1.5 TFLOPS (FP16) of performance.
Expansion of Commercial and Dual-Use Technologies
Commercial off-the-shelf (COTS) technology adoption is expanding, reducing costs and development timelines. Manufacturers integrate advanced commercial components into military systems to improve performance and scalability. Dual-use applications, including drones, computing tablets, and imaging devices, serve both defense and civilian markets. Collaboration between private firms and defense agencies promotes faster innovation and customization. This crossover encourages efficient supply chains and greater flexibility in field operations, driving market competitiveness and accessibility.
- For instance, ASELSAN’s “CATS – Common Aperture Targeting System” electro-optical product uses a 220 mm diameter aperture and supports HDTV resolution of 1920 × 1080 pixels, LL-NIR of 800 × 600, and an IR camera of 640 × 512, based on updated product specifications.
Key Challenges
High Procurement and Maintenance Costs
The cost of developing and maintaining advanced man-portable electronic systems remains a major barrier. Devices with integrated AI, encryption, and communication modules demand significant R&D investment. Budget constraints in developing nations restrict large-scale deployment. Additionally, repair and upgrade costs for field-deployed systems increase operational expenses. Balancing performance, durability, and affordability continues to challenge manufacturers and defense procurement agencies.
Cybersecurity and Data Vulnerability Risks
Growing connectivity across devices heightens risks of cyberattacks and data breaches. Unauthorized access to communication systems can compromise mission integrity and soldier safety. Portable systems must maintain strong encryption, authentication, and real-time threat detection capabilities. However, ensuring security in resource-limited, remote environments remains difficult. Continuous cybersecurity upgrades are essential but often strain defense budgets and complicate system interoperability across platforms.
Regional Analysis
North America
North America dominates the man-portable military electronics market with a 38% share. The region benefits from strong defense spending by the U.S. Department of Defense and Canada’s modernization initiatives. High investments in tactical communication, surveillance, and soldier systems drive growth. Advanced programs like the Integrated Visual Augmentation System (IVAS) by Microsoft and AI-based battlefield solutions enhance operational capabilities. Continuous R&D by key players such as L3Harris Technologies and Raytheon supports innovation in portable command and control devices, reinforcing North America’s leadership in military-grade communication and computing technologies.
Europe
Europe holds a 27% market share, driven by rising defense budgets and cross-border security collaborations. NATO initiatives and national modernization programs support demand for secure communication and battlefield monitoring systems. Countries such as Germany, the U.K., and France focus on equipping soldiers with advanced handheld electronics to strengthen interoperability in joint missions. The European Defense Fund’s investment in research enhances technology development across member states. Companies like Thales Group and BAE Systems lead innovation in ruggedized portable computing and intelligence systems for military operations across varied terrains.
Asia Pacific Asia Pacific accounts for a 23% share, supported by rapid defense modernization and territorial security initiatives. Nations such as China, India, Japan, and South Korea are investing heavily in portable communication, computing, and drone systems to enhance border defense. Government programs like India’s “Make in India” encourage domestic production of military electronics, reducing reliance on imports. The adoption of AI and miniaturized systems is expanding across regional defense agencies. Collaboration between local manufacturers and global defense firms accelerates product development and deployment efficiency in the region.
Latin America
Latin America holds a 5% share, reflecting steady growth in defense modernization and homeland security programs. Nations such as Brazil, Mexico, and Colombia are investing in portable electronic systems to enhance border surveillance and tactical coordination. Limited budgets restrict large-scale deployments; however, partnerships with international defense suppliers are expanding access to advanced technologies. Growing use of drones and communication systems for counter-narcotics and peacekeeping missions supports market expansion. Regional emphasis on upgrading defense infrastructure and interoperability continues to create long-term opportunities for technology integration.
Middle East & Africa
The Middle East & Africa region captures a 7% market share, primarily driven by defense digitization efforts and counter-terrorism initiatives. Countries including Saudi Arabia, the UAE, and Israel invest in man-portable systems for intelligence, surveillance, and border security. Local manufacturing programs aim to develop indigenous capabilities while reducing foreign dependency. The rising focus on battlefield connectivity and situational awareness strengthens market adoption. Strategic defense collaborations with Western technology providers further accelerate technological upgrades and modernization of portable communication and computing devices.
Market Segmentations:
By Product Type:
- Telephony
- Computing
By Price:
- Low
- Medium
By End User:
- Residential
- Commercial
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The man-portable military electronics market is highly competitive, with key players including Indra Sistemas S.A., Honeywell International Inc., Bharat Electronics Limited, Hensoldt, Israel Aerospace Industries (IAI), Curtiss-Wright Corporation, Elbit Systems Ltd., Aselsan A.S., General Dynamics Corporation, and BAE Systems PLC. The man-portable military electronics market is characterized by intense competition and rapid technological innovation. Manufacturers are focusing on developing lightweight, energy-efficient, and durable systems to enhance soldier mobility and mission effectiveness. Advancements in miniaturized sensors, secure communication modules, and AI-based situational awareness tools are transforming battlefield operations. Companies are increasingly investing in R&D to integrate IoT, real-time data analytics, and augmented reality into portable systems. Strategic collaborations with defense agencies and modernization programs across major economies further drive product development. The market’s competitive edge lies in continuous innovation, system interoperability, and meeting stringent defense performance standards.
Key Player Analysis
- Indra Sistemas, S.A.
- Honeywell International Inc.
- Bharat Electronics Limited
- Hensoldt
- Israel Aerospace Industries (IAI)
- Curtiss-Wright Corporation
- Elbit Systems Ltd.
- Aselsan A.S.
- General Dynamics Corporation
- BAE Systems PLC
Recent Developments
- In January 2025, Samsung Electronics America unveiled its latest innovation, Samsung Vision AI1, at the CES First Look 2025 event. This advanced AI technology showcases groundbreaking applications designed to deliver exceptional picture quality and serve as adaptive, intelligent companions that simplify and enhance daily life.
- In June 2024, Honeywell announced an agreement to acquire CAES Systems Holdings for in an all-cash deal. The acquisition was completed in September 2024 and expanded Honeywell's portfolio to include work on the SPY-6 naval radar, drone, and counter-drone technologies.
- In May 2024, DARPA awarded BAE Systems' FAST Labs a contract for the THREADS program to address thermal management challenges in defense electronics. The program aims to overcome temperature limitations in power-amplifying functions, specifically in monolithic microwave integrated circuits (MMICs) that use gallium nitride (GaN) devices.
- In April 2024, Raytheon, a business unit of RTX, received a contract to produce two missile variants: the SM-2 Block IIICU and SM-6 Block IU. The missiles will share common components, including the guidance section, target detection device, flight termination system, and electronics unit, allowing for unified production line manufacturing.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Price, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will expand with rising demand for compact and multi-functional soldier systems.
- Integration of AI and IoT will enhance real-time battlefield data and decision-making.
- Growth in defense modernization programs will boost adoption of portable electronics.
- Development of lightweight, energy-efficient devices will improve soldier mobility and endurance.
- Increased investment in R&D will drive innovation in secure communication systems.
- Rising geopolitical tensions will accelerate procurement of advanced tactical equipment.
- Collaboration between defense agencies and private firms will strengthen product development.
- Miniaturization of sensors and processors will enhance operational efficiency and accuracy.
- Expansion of autonomous and unmanned systems will create new growth opportunities.
- Focus on cybersecurity and encrypted communication will remain a top industry priority.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Man Portable Military Electronics Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Man Portable Military Electronics Market projected to grow between 2025 and 2032?
Which Man Portable Military Electronics Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Man Portable Military Electronics Market?
Who are the leading companies in the Man Portable Military Electronics Market?
Which region commanded the largest share of the Man Portable Military Electronics Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 10.7 billion → 2032: USD 15.39 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Man Portable Military Electronics Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Man Portable Military Electronics Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Man Portable Military Electronics Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Man Portable Military Electronics Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Man Portable Military Electronics Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Man Portable Military Electronics Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Man Portable Military Electronics Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Man Portable Military Electronics Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 10.7 billion → 2032: USD 15.39 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Man Portable Military Electronics Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Man Portable Military Electronics Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Man Portable Military Electronics Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Man Portable Military Electronics Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

