
Market Overview
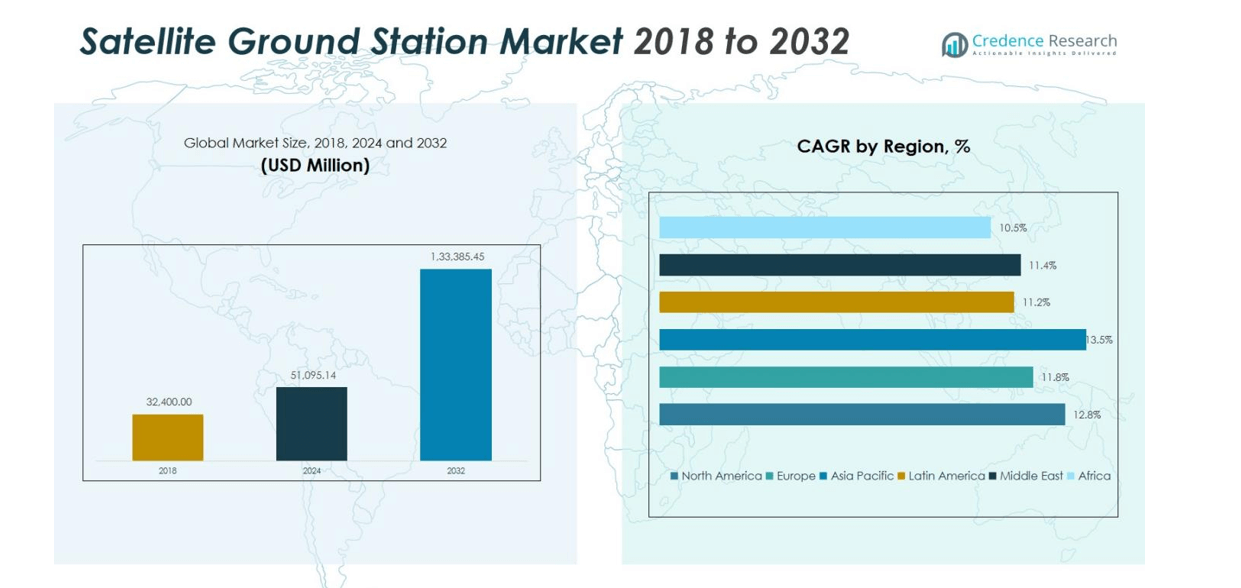
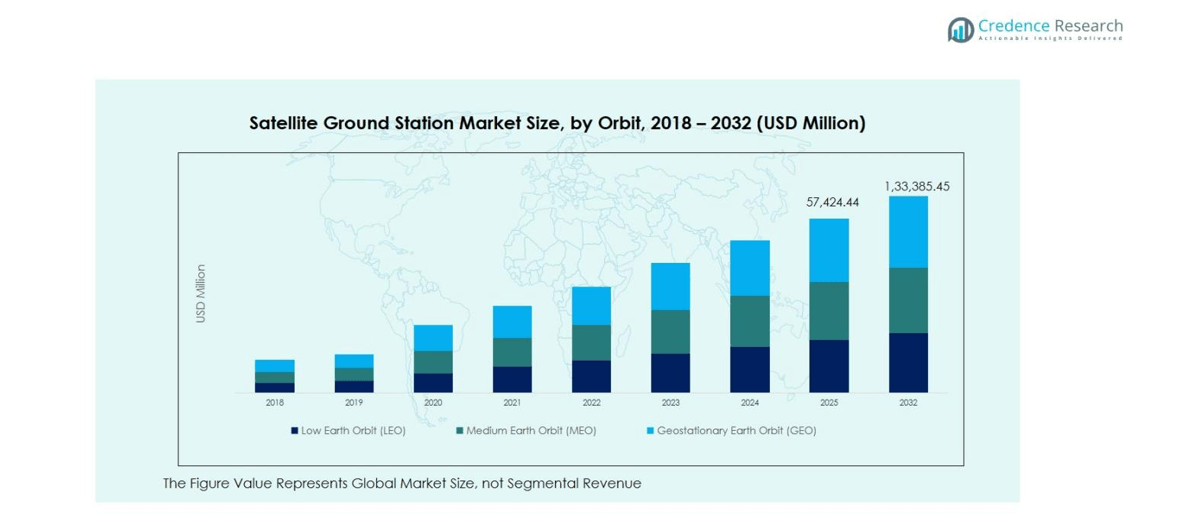
The Satellite Ground Station Market size was valued at USD 32,400.00 million in 2018, increased to USD 51,095.14 million in 2024, and is anticipated to reach USD 1,33,385.45 million by 2032, growing at a CAGR of 12.79% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Satellite Ground Station Market Size 2024 | USD 51,095.14 million |
| Satellite Ground Station Market, CAGR | 12.79% |
| Satellite Ground Station Market Size 2032 | USD 1,33,385.45 million |
The Satellite Ground Station Market is highly competitive, with key players such as Kongsberg Gruppen, Viasat Inc., Airbus Defence and Space, Thales Group, Kratos Defense & Security Solutions, SES S.A., Comtech Telecommunications Corp., and Gilat Satellite Networks Ltd. leading the global landscape. These companies are focusing on developing advanced, automated, and cloud-integrated ground systems to enhance data transmission efficiency and global connectivity. Strategic initiatives including partnerships, mergers, and technology upgrades are strengthening their market positions. Asia Pacific emerged as the leading region in 2024, commanding 52.8% of the global market share, driven by rapid digitalization, expanding government space programs, and the increasing deployment of satellite communication networks across China, India, and Japan.
Market Insights
- The Satellite Ground Station Market was valued at USD 51,095.14 million in 2024 and is projected to reach USD 1,33,385.45 million by 2032, expanding at a CAGR of 12.79% during the forecast period.
- Rising demand for satellite communication, broadband connectivity, and real-time data transmission across commercial and defense sectors is a key market driver supporting infrastructure expansion.
- Integration of cloud-based systems, AI, and automation in ground operations is a major trend enhancing efficiency and scalability across global networks.
- The market is moderately consolidated, with major players such as Kongsberg Gruppen, Viasat Inc., Airbus Defence and Space, Thales Group, and SES S.A. dominating through technological innovation and partnerships.
- Asia Pacific led the market with 8% share in 2024, followed by Europe and North America, while the Fixed platform segment held the largest share at 69.9%, driven by high adoption in commercial and government satellite operations.
Market Segmentation Analysis:
By Platform
Within the platform segment, the Fixed sub-segment dominates the Satellite Ground Station Market, accounting for 69.9% of the global share in 2024. This leadership is driven by the extensive deployment of fixed ground infrastructures that ensure continuous and reliable communication for broadcasting, data relay, and Earth observation missions. Fixed stations offer superior bandwidth, stable connectivity, and cost efficiency, making them essential for both government and commercial satellite operations. Meanwhile, portable and mobile stations are witnessing moderate growth, supported by demand for field-deployable and mobile communication solutions in defense and emergency services.
- For instance, Thales Group launched its modular FlexGround fixed ground stations, using software-defined radio technology that reduces operational costs by up to 40% while supporting multiple satellite constellations simultaneously.
By Function
The Communication sub-segment holds the largest share in the function category, representing 58.3% of the overall market in 2024. This dominance arises from the increasing need for high-capacity communication links supporting broadband connectivity, satellite television, and data transmission networks. Expanding LEO and MEO satellite constellations are amplifying ground communication requirements across both developed and emerging regions. Continuous advancements in antenna technology and network automation further enhance the efficiency and scalability of communication ground stations, reinforcing their leading position in the market.
- For instance, Eutelsat OneWeb inaugurated a new Satellite Network Portal in Yellowknife, Northern Canada, in 2024, significantly enhancing bandwidth and network resilience for its LEO constellation.
By End-User
Among end-users, the Commercial segment leads the market with 54.7% share in 2024. The expansion of private satellite networks, satellite broadband services, and ground station-as-a-service (GSaaS) models has fueled commercial investment in advanced ground infrastructure. Growing data consumption, media broadcasting, and enterprise connectivity requirements are accelerating the deployment of commercial ground stations worldwide. Although government and defense users remain critical for national security and research applications, commercial operators drive the highest growth rate due to faster innovation cycles and broader application diversity.
Key Growth Drivers
Rising Demand for Satellite Communication Services
The growing need for seamless global communication, broadband connectivity, and media broadcasting is a major driver of the Satellite Ground Station Market. Increasing deployment of Low Earth Orbit (LEO) constellations enhances real-time data exchange, requiring advanced ground station networks. Governments and private operators are expanding satellite infrastructures to support 5G backhaul, remote sensing, and maritime connectivity. This surge in bandwidth demand and satellite traffic is prompting heavy investments in fixed and mobile ground stations with advanced antenna systems and automation technologies.
- For instance, SpaceX’s Starlink LEO constellation, which operates thousands of satellites and drives the need for extensive, globally distributed ground stations to maintain low-latency broadband connectivity.
Advancements in Antenna and Network Technologies
Technological innovation in antenna systems, including phased-array and electronically steerable antennas, is significantly improving data transmission efficiency and flexibility in satellite ground stations. These advancements allow seamless communication with multiple satellites simultaneously, reducing latency and increasing network reliability. Integration of software-defined networking and AI-driven monitoring further optimizes resource management and minimizes operational costs. Such improvements enhance scalability and enable ground stations to support growing satellite fleets, positioning technology upgrades as a core catalyst for market expansion.
- For instance, Kymeta has pioneered holographic, electronically steerable antennas using metasurface technology, enabling wide-angle beam steering without moving parts, which allows for high gain in a low-profile, low-power format.
Expansion of Commercial Satellite Networks
The rapid increase in private satellite launches and commercial space ventures is accelerating demand for ground station infrastructure. Companies are adopting Ground Station-as-a-Service (GSaaS) models to enhance accessibility and reduce operational costs. The expanding use of satellites for Earth observation, communication, and navigation drives collaboration between public and private entities. Commercial enterprises’ focus on global coverage and low-latency communication reinforces the need for scalable, automated, and cloud-integrated ground systems, thereby fueling market growth across multiple sectors.
Key Trends and Opportunities
Integration of Cloud-Based Ground Station Services
The shift toward cloud-enabled satellite ground systems is reshaping operational models. Cloud platforms offer scalable data processing, real-time analytics, and cost-efficient network management. This integration enhances flexibility by allowing ground stations to process, store, and distribute data globally through cloud networks. Major space technology firms are forming strategic partnerships with cloud service providers to create virtualized, on-demand ground infrastructures. This trend is expected to open new opportunities for satellite operators and data service providers seeking rapid and flexible global connectivity solutions.
- For instance, Kratos Space delivers cloud-enabled ground system products that leverage virtual architecture to reduce costs and improve scalability and security across various satellite applications, including earth observation and geostationary communications.
Adoption of AI and Automation in Ground Operations
Artificial intelligence and automation are transforming satellite ground station management by improving predictive maintenance, signal optimization, and scheduling accuracy. AI-driven analytics enable faster data interpretation and reduce manual interventions in satellite control. Automation also supports multi-satellite coordination, enhancing efficiency in large-scale networks. These advancements are creating opportunities for cost reduction, reliability improvement, and intelligent decision-making, allowing operators to handle increasing satellite traffic with minimal downtime and greater operational precision.
- For instance, Airbus utilizes AI to enable ground segment automation, crucial for efficiently managing future mega satellite constellations.
Key Challenges
Cybersecurity Threats and Data Vulnerabilities
The growing digitization and interconnectivity of satellite ground systems expose them to cybersecurity risks such as data breaches, signal interference, and network intrusions. As more systems adopt cloud-based and software-defined architectures, the need for advanced encryption, threat detection, and secure communication protocols becomes critical. Protecting mission-critical data and maintaining signal integrity are ongoing challenges for both commercial and government operators, requiring continuous investment in robust cybersecurity infrastructure and international cooperation on secure space communication frameworks.
High Infrastructure and Maintenance Costs
The establishment and maintenance of satellite ground stations involve substantial capital investments in antennas, RF systems, and control software. Continuous technological upgrades and integration of automation solutions add to the overall operational cost. Smaller operators face challenges in maintaining economic viability amid rapid technological evolution. High costs of skilled personnel, energy, and maintenance limit accessibility in emerging markets. To overcome this, stakeholders are increasingly adopting shared infrastructure and cloud-based service models to improve efficiency and reduce financial burdens.
Regional Analysis
North America
North America held a 14.9% market share in 2018, valued at USD 4,989.60 million, and is projected to grow from USD 7,643.53 million in 2024 to USD 19,888.01 million by 2032, at a CAGR of 12.8%. The region’s strong presence is driven by extensive investments in satellite communication infrastructure, particularly in the U.S. defense and commercial sectors. Expanding low Earth orbit (LEO) constellations and initiatives by NASA and private players such as SpaceX are accelerating technological innovation. The integration of 5G networks and data relay systems further enhances North America’s position in the global market.
Europe
Europe accounted for a 21.3% market share in 2018, with a valuation of USD 6,901.20 million, rising to USD 10,360.70 million in 2024 and projected to reach USD 25,176.86 million by 2032, growing at a CAGR of 11.8%. The region’s growth is driven by the European Space Agency’s (ESA) programs and increasing private investments in satellite communication and Earth observation. Expanding broadband connectivity, government-led sustainability initiatives, and cross-border collaborations support infrastructure modernization, reinforcing Europe’s role as a key contributor to global satellite ground network expansion.
Asia Pacific
Asia Pacific dominated the market with a 52.8% share in 2018, valued at USD 17,107.20 million, growing to USD 27,532.40 million in 2024 and projected to reach USD 75,402.90 million by 2032, registering the highest CAGR of 13.5%. Rapid digitalization, rising satellite launches, and robust government programs across China, India, and Japan are fueling growth. Expanding communication networks, ISRO’s satellite missions, and China’s BeiDou navigation program strengthen the region’s infrastructure. Increasing demand for remote communication and Earth observation services positions Asia Pacific as the global leader in market expansion.
Latin America
Latin America represented a 4.2% market share in 2018, valued at USD 1,360.80 million, expanding to USD 2,114.83 million in 2024 and projected to reach USD 4,917.92 million by 2032, growing at a CAGR of 11.2%. The region’s growth is led by Brazil, Mexico, and Argentina, where governments are investing in digital transformation and telecommunication expansion. Increasing adoption of Earth observation satellites and improved access to commercial satellite data are strengthening market potential. Partnerships with global satellite operators are enhancing connectivity and data transmission infrastructure across the region.
Middle East
The Middle East accounted for a 3.9% market share in 2018, valued at USD 1,260.36 million, increasing to USD 1,864.64 million in 2024 and expected to reach USD 4,402.45 million by 2032, at a CAGR of 11.4%. Growth is driven by strong government investments in space research, national security, and communication systems, particularly in the UAE, Saudi Arabia, and Israel. Regional space programs and partnerships with international agencies are enhancing data transmission capabilities. Rising demand for navigation and high-speed satellite communication is fostering technological advancement in ground station infrastructure.
Africa
Africa held a 2.9% market share in 2018, valued at USD 780.84 million, and is projected to grow from USD 1,579.05 million in 2024 to USD 3,597.31 million by 2032, registering a CAGR of 10.5%. Market growth is supported by increasing reliance on satellite-based communication in underserved and remote regions. Countries such as South Africa, Nigeria, and Egypt are investing in Earth observation and broadband initiatives. The growing need for satellite connectivity in agriculture, disaster monitoring, and rural internet access continues to drive technological progress and partnerships with global satellite operators.
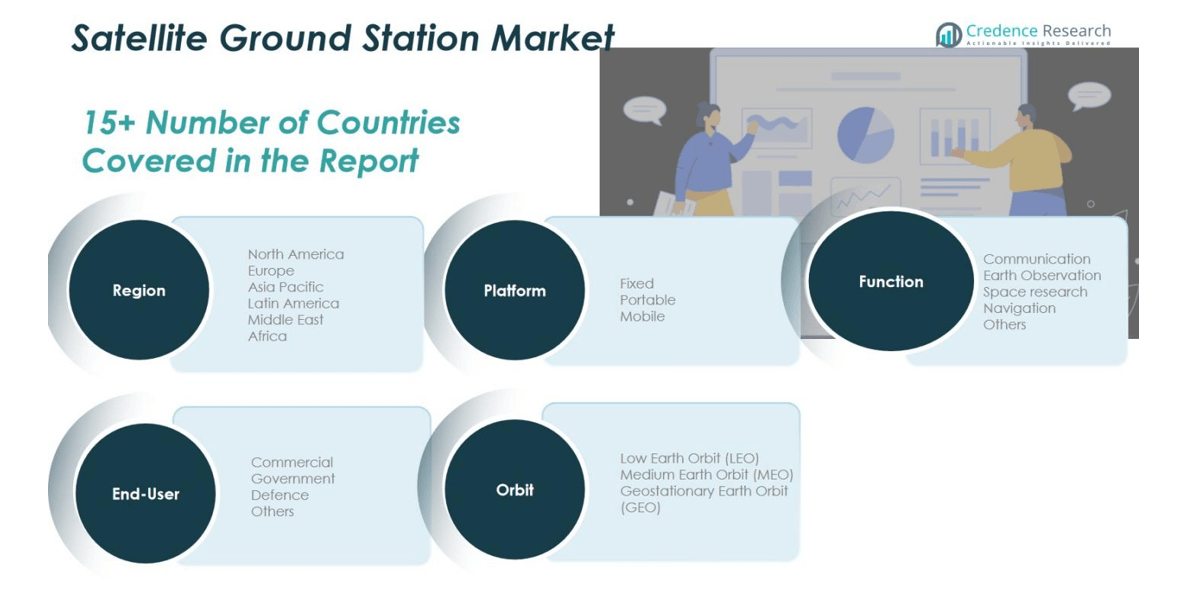
Market Segmentations:
By Platform
- Fixed
- Portable
- Mobile
By Function
- Communication
- Earth Observation
- Space Research
- Navigation
- Others
By End-user
- Commercial
- Government
- Defence
- Others
By Orbit
- Low Earth Orbit (LEO)
- Medium Earth Orbit (MEO)
- Geostationary Earth Orbit (GEO)
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Satellite Ground Station Market is characterized by the presence of major players such as Kongsberg Gruppen, Viasat Inc., Airbus Defence and Space, Kratos Defense & Security Solutions, Thales Group, SES S.A., Comtech Telecommunications Corp., and Gilat Satellite Networks Ltd. These companies are actively focusing on developing advanced, automated, and cloud-integrated ground station systems to support growing satellite constellations and data demands. Strategic initiatives such as mergers, partnerships, and investments in ground station-as-a-service (GSaaS) models are strengthening their market positions. Leading firms are emphasizing interoperability and real-time communication capabilities to improve performance and reduce latency in satellite data handling. Continuous advancements in antenna technology, virtualization, and remote operation platforms are enabling flexible, scalable ground infrastructure. The competition remains intense, with players striving to enhance global coverage, operational efficiency, and cost-effectiveness to meet the increasing demand for satellite-based communication and Earth observation services.
Key Player Analysis
- Intelsat
- Comtech Technologies Inc.
- General Dynamics Corporation
- Kongsberg Gruppen ASA
- Airbus SE
- Eutelsat Communications
- Viasat
- Inmarsat
- Iridium Communications
- Globecast
- Hughes Network Systems
- Advantech Wireless
- Optus Satellite
Recent Developments
- In September 2025, ThinKom Solutions Inc. partnered with Kongsberg Satellite Services (KSAT) to develop a commercially scalable receive-only ground station integrating ThinKom’s active phased array technology with KSAT’s global satellite network.
- In July 2025, Amazon Web Services (AWS) expanded its Ground Station as a Service Partner Program with KSAT, enabling users to access AWS cloud services alongside KSAT’s worldwide antenna infrastructure.
- In August 2025, Global Invacom Holdings Limited co-founded eNexus Space Data to enter the Ground Station as a Service (GSaaS) market, offering satellite operators enhanced access to data services across various orbital levels.
- In August 2025, Kongsberg Satellite Services (KSAT) announced plans to deploy a fleet of “Hyper” low-Earth-orbit satellites functioning as space-based ground stations to reduce latency and enhance real-time data delivery
Report Coverage
The research report offers an in-depth analysis based on Platform, Function, End User, Orbit and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Satellite Ground Station Market will experience robust growth driven by expanding low Earth orbit (LEO) satellite constellations.
- Integration of artificial intelligence and automation will enhance data processing and real-time communication efficiency.
- Demand for ground station-as-a-service (GSaaS) solutions will rise as operators seek flexible and scalable infrastructure.
- Increasing government investments in space research and defense communication will strengthen market adoption.
- Cloud-based ground station networks will gain traction for improved connectivity and remote access.
- Advancements in phased array and electronically steerable antennas will boost signal accuracy and reliability.
- Commercial players will expand their presence through partnerships and strategic collaborations with satellite operators.
- Asia Pacific will continue to lead global growth due to rapid digitalization and space program expansion.
- Sustainability initiatives will promote the development of energy-efficient and eco-friendly ground station systems.
- The market will see intensified competition as companies innovate to deliver higher bandwidth and lower latency solutions.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expansion of LEO and MEO Satellite Constellations
The rapid deployment of low and medium Earth orbit satellite constellations is driving demand for advanced ground station infrastructure to support high-frequency, low-latency data transmission and global broadband connectivity.
Integration of Cloud-Based and Automated Ground Systems
Adoption of cloud-enabled and AI-driven ground station solutions is enhancing scalability, reducing operational costs, and enabling real-time data processing, making ground station services more accessible and efficient for commercial and government users.
Growth in Commercial Satellite Networks and GSaaS Models
The proliferation of private satellite launches and the rise of ground station-as-a-service (GSaaS) offerings are fueling investment in flexible, scalable ground infrastructure, supporting diverse applications from Earth observation to enterprise connectivity.
Technological Advancements in Antenna and Network Systems
Innovations such as phased-array and electronically steerable antennas, along with software-defined networking, are improving signal reliability, bandwidth, and multi-satellite communication capabilities, making ground stations more versatile and cost-effective.
Government Investments in Space and Defense Communications
Increased funding for national space programs and defense communication networks is accelerating the modernization and expansion of ground station infrastructure, particularly in regions with active space research and security initiatives.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Satellite Ground Station Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Satellite Ground Station Market projected to grow between 2025 and 2032
Which Satellite Ground Station Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Satellite Ground Station Market?
Who are the leading companies in the Satellite Ground Station Market?
Which region commanded the largest share of the Satellite Ground Station Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Orbit
- 1.2.1 Low Earth Orbit (LEO)
- 1.2.2 Medium Earth Orbit (MEO)
- 1.2.3 Geostationary Earth Orbit (GEO)
- 1.3 By End-user
- 1.3.1 Commercial
- 1.3.2 Government
- 1.3.3 Defence
- 1.3.4 Others
- 1.4 By Function
- 1.4.1 Communication
- 1.4.2 Earth Observation
- 1.4.3 Space Research
- 1.4.4 Navigation
- 1.4.5 Others
- 1.5 By Platform
- 1.5.1 Fixed
- 1.5.2 Portable
- 1.5.3 Mobile
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 51,095.14 million → 2032: USD 1,33,385.45 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Satellite Ground Station Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Satellite Ground Station Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Satellite Ground Station Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Satellite Ground Station Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Satellite Ground Station Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Satellite Ground Station Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Satellite Ground Station Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Satellite Ground Station Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 51,095.14 million → 2032: USD 1,33,385.45 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Satellite Ground Station Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Orbit - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Low Earth Orbit (LEO)
- 12.3.7.2 Medium Earth Orbit (MEO)
- 12.3.7.3 Geostationary Earth Orbit (GEO)
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End-user - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Commercial
- 12.4.7.2 Government
- 12.4.7.3 Defence
- 12.4.7.4 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Function - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Communication
- 12.5.7.2 Earth Observation
- 12.5.7.3 Space Research
- 12.5.7.4 Navigation
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Platform - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Fixed
- 12.6.7.2 Portable
- 12.6.7.3 Mobile
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Satellite Ground Station End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Satellite Ground Station Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Satellite Ground Station Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Satellite Ground Station Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Kongsberg Gruppen
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Viasat Inc.
- 18.4 Airbus Defence and Space
- 18.5 Thales Group
- 18.6 Kratos Defense & Security Solutions
- 18.7 SES S.A.
- 18.8 Comtech Telecommunications Corp.
- 18.9 Gilat Satellite Networks Ltd.
- 18.10 Eutelsat Communications
- 18.11 Intelsat
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

