
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Military Communication Market Size 2024 | USD 33,125 Million |
| Military Communication Market, CAGR | 7.1% |
| Military Communication Market Size 2032 | USD 57,341.8 Million |
Market Overview
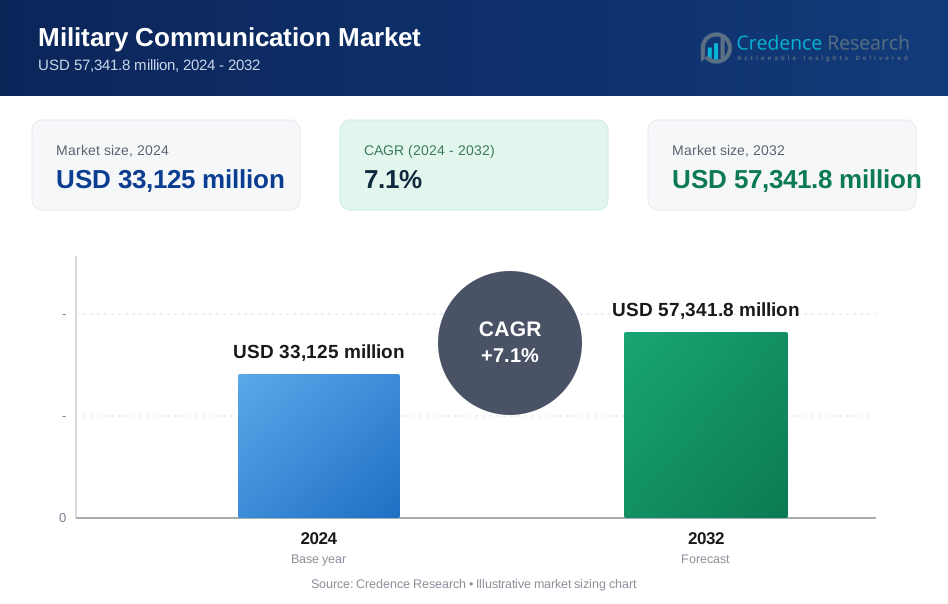
The Military Communication Market is expected to grow from USD 33,125 million in 2024 to USD 57,341.8 million by 2032, at a CAGR of 7.1%.
The military communication market is driven by the increasing demand for advanced communication systems to ensure secure, real-time information exchange in defense operations. The growing focus on modernization and the adoption of next-gen technologies like satellite communication, cloud computing, and AI for enhanced data transmission and operational efficiency are key trends. Additionally, rising geopolitical tensions and the need for effective border control are propelling the demand for secure and reliable communication infrastructure. The shift towards integrated communication solutions and the increasing use of mobile and wireless technologies also contribute to the market's expansion.
The military communication market is geographically diverse, with significant demand in regions such as North America, Europe, and the Asia Pacific. North America, led by the United States, remains a dominant player due to its advanced defense infrastructure and technological capabilities. Europe also plays a critical role, with countries like the UK and France investing heavily in defense modernization. The Asia Pacific region is witnessing rapid growth, driven by rising defense budgets and geopolitical tensions. Key players in this market include companies such as Northrop Grumman, Lockheed Martin, Raytheon Technologies, Thales Group, and Saab AB.
Market Drivers
Geopolitical Tensions and Increased Defense Spending Rising geopolitical tensions and global conflicts are significant drivers of the military communication market. Nations are increasing their defense budgets to strengthen military capabilities, which directly impacts the demand for advanced communication systems. For instance, global military expenditure reached $2.4 trillion in 2023, reflecting a 6.8% increase from the previous year due to heightened geopolitical tensions. These systems are vital for effective military operations, ensuring secure and reliable transmission of critical information during conflicts. As governments prioritize national security, they invest heavily in upgrading communication infrastructure to support modernized defense strategies.
Advancements in Communication Technologies The continuous advancement of communication technologies plays a key role in modern military communication systems. Technologies such as satellite communication, software-defined radios, and the rollout of 5G networks are transforming military communication. For example, the integration of 5G networks is expected to significantly enhance the speed and reliability of military communications. These innovations provide higher data rates, improved network capacity, and enhanced security, enabling faster, more secure exchanges of information. The integration of next-gen technologies ensures that military forces can stay connected across vast geographical distances and in challenging operational environments.
Integration of Unmanned Systems and AI The increasing deployment of unmanned systems, such as UAVs, has elevated the need for robust communication links to enable remote control and data transmission. Moreover, the integration of artificial intelligence (AI) into military communication systems enhances situational awareness, decision-making, and automation. AI helps to optimize communication processes, improving efficiency in complex and dynamic military operations. For instance, AI and machine learning algorithms can process vast amounts of communication data in real-time, allowing military personnel to respond rapidly to evolving situations. These technological advancements contribute to the overall transformation of military communication infrastructure, ensuring a more agile and responsive defense system.
Need for Secure and Reliable Communication Military operations require communication systems that can withstand potential cyberattacks and other security threats. As military missions become increasingly complex, secure and reliable communication is crucial for maintaining command and control, intelligence sharing, and logistical support. This demand for resilience drives innovations in communication technologies, as defense forces seek systems capable of safeguarding sensitive information while ensuring uninterrupted operations in hostile environments.
Market Trends
Increased Focus on Cybersecurity and Enhanced Protection With the growing sophistication of cyber threats, cybersecurity has become a critical focus in military communication systems. The risks of cyberattacks, such as data breaches and system infiltrations, are escalating, necessitating robust protection strategies. Military communication infrastructure is being fortified through advanced encryption, authentication protocols, and intrusion detection systems to safeguard sensitive information. For instance, a report on military cybersecurity highlights that only 39% of respondents felt moderately confident in their agency's preparedness for a cyberattack on defense communications infrastructure. These enhanced security measures ensure that communication systems remain resilient in the face of cyber threats, maintaining operational integrity and preventing disruption. As military communication systems evolve, cybersecurity must remain a top priority to secure data flows and protect national security interests.
Adoption of Advanced Technologies and Network Resilience The adoption of Software-Defined Radios (SDRs) is transforming military communication, offering greater flexibility and adaptability compared to traditional radio systems. SDRs can be easily reconfigured to operate across multiple frequencies and modulation schemes, reducing the need for specialized hardware and providing cost-effective solutions. Additionally, artificial intelligence (AI) is being integrated into communication systems, enhancing decision-making and automating routine tasks. AI-driven insights improve real-time situational awareness and operational efficiency. Advancements in satellite communication systems are further boosting network resilience, providing reliable connectivity, especially in remote and challenging environments. Additionally, the integration of the Internet of Things (IoT) is enabling connected devices to gather critical data for military operations, delivering real-time insights that improve battlefield intelligence. As military communication systems move toward network-centric warfare, the emphasis on interoperability and information sharing across platforms becomes essential, ensuring seamless coordination across different military units. Lastly, the rollout of 5G technology promises high-speed connectivity and lower latency, enabling faster communication, real-time video streaming, and the advancement of autonomous systems, further enhancing military operations.
Market Challenges Analysis
Cybersecurity Threats and Data Protection Challenges The increasing sophistication of cyberattacks poses a significant threat to military communication systems, which are critical for national security. As these systems become more interconnected, they are vulnerable to advanced cyber threats that could compromise sensitive information or disrupt operations. Hackers and state-sponsored actors are continuously evolving their tactics, making it difficult for military forces to safeguard their networks. Moreover, data breaches could expose vital military secrets and intelligence, resulting in severe strategic consequences. Protecting against these threats requires ongoing investment in robust cybersecurity measures, encryption technologies, and real-time monitoring systems to ensure data integrity and secure communication channels across military networks.
Interoperability, Spectrum Congestion, and Emerging Technological Challenges One of the key challenges in military communications is ensuring interoperability between diverse systems. Military forces often rely on a range of communication technologies from different manufacturers, each with its own protocols and standards. This lack of standardization makes it difficult to ensure seamless information exchange across units and platforms, hindering operational effectiveness. Furthermore, the limited availability of radio spectrum for military communication is a growing concern, with spectrum congestion and interference threatening the reliability and security of communications. Efficient spectrum management is vital to prevent these issues. According to a survey on spectrum management, concerns for spectrum congestion have spurred extensive research efforts on efficient spectrum management. Additionally, the high costs and complexity associated with developing advanced military communication systems, particularly for smaller nations, can strain resources. For instance, developing a new military communication satellite system can cost upwards of $1 billion. The rapid pace of technological advancements in communication technologies adds another layer of complexity, as integrating new innovations into existing systems can be time-consuming and challenging. These factors create an ongoing challenge for military forces in maintaining effective, secure, and up-to-date communication systems.
Market Segmentation Analysis:
By Component:
The military communication market is segmented into two main components: systems and services. The systems segment is further divided into satellite communication systems, radar & sonar systems, and radio systems. Satellite communication systems are essential for providing long-range communication capabilities in remote and hostile environments, ensuring continuous connectivity for military operations. Radar and sonar systems play a crucial role in detecting and tracking objects, making them vital for defense operations. Radio systems remain a key communication tool, offering reliable, real-time communication for ground troops. The services segment, which includes consulting, testing & integration, and support & maintenance, is equally important. Consulting services help military organizations design and implement communication solutions tailored to their specific needs, while testing & integration services ensure that systems meet required standards. Support & maintenance services are necessary for the ongoing functionality and reliability of communication systems, offering regular upgrades and troubleshooting to maintain optimal performance.
By Applications:
The market for military communication solutions is driven by several critical applications, including Intelligence, Surveillance, and Reconnaissance (ISR), situational awareness, and command & control. ISR systems are essential for gathering intelligence, monitoring threats, and providing real-time data to military personnel, improving decision-making and operational efficiency. Situational awareness applications focus on providing comprehensive information about the battlefield environment, enabling military units to stay informed and react swiftly to emerging threats. Command & control systems are vital for coordinating operations, ensuring that military forces can effectively plan and execute missions. The integration of these applications within military communication systems is crucial for enhancing overall operational effectiveness, ensuring that the armed forces have access to the most up-to-date information to support mission success.
Segments:
Based on Component:
- Systems
- Satellite Communication Systems
- Radar & Sonar Systems
- Radio Systems
- Services
- Consulting
- Testing & Integration
- Support & Maintenance
Based on Applications:
- ISR
- Situational Awareness
- Command & Control
Based on End User:
- Air Force
- Land Force
- Naval Force
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America accounts for the largest market share, estimated at 40%, driven primarily by the robust defense budgets of the United States and Canada. The U.S. military's ongoing investments in advanced communication systems, including satellite communication, radio systems, and secure mobile technologies, continue to bolster the market in this region. Furthermore, the increasing adoption of 5G technologies and artificial intelligence (AI) for enhanced situational awareness and decision-making is contributing to market expansion. The region's military forces also prioritize cybersecurity to counteract growing threats, driving demand for highly secure, resilient communication systems. The U.S., in particular, remains a key player in global defense technology innovation, which further strengthens North America's dominance in the military communication sector.
Europe
In contrast, Europe holds a 25% market share and is witnessing steady growth in military communication investments, driven by defense modernization initiatives among NATO members and EU countries. The region’s focus on interoperability, network-centric operations, and advanced communication technologies has significantly enhanced its military capabilities. Countries like the United Kingdom, Germany, and France are leading the charge in integrating advanced satellite communication systems, AI-based decision-making tools, and cybersecurity solutions into their military operations. As European nations seek to improve their defense coordination with NATO allies, the demand for integrated communication systems continues to rise. Additionally, the increasing threat of geopolitical tensions in Eastern Europe, particularly with Russia, has intensified the need for reliable and secure communication channels for defense and military operations, further fueling the market in this region.
Key Player Analysis
- Northrop Grumman Corporation (US)
- Lockheed Martin Corporation (US)
- Raytheon Technologies Corporation (US)
- L3Harris Technologies Inc. (US)
- Viasat Inc. (US)
- Honeywell International Inc. (US)
- Thales Group (France)
- Leonardo (Italy)
- Rheinmetall AG (Germany)
- Saab AB (Sweden)
- BAE Systems (UK)
- Cobham Limited (UK)
- Elbit Systems (Israel)
- Israel Aerospace Industries (Israel)
- Aselsan A.S (Turkey)
Competitive Analysis
The military communication market is highly competitive, with key players striving for technological advancements and market share. Companies like Raytheon Technologies, Northrop Grumman, Thales Group, Elbit Systems, L3Harris Technologies, Lockheed Martin, BAE Systems, Saab AB, Aselsan A.S, Viasat Inc., Rheinmetall AG, Leonardo, Israel Aerospace Industries, Cobham Limited, and Honeywell International Inc. are at the forefront of developing sophisticated communication systems for defense applications. These players focus on integrating cutting-edge technologies such as satellite communication, radar & sonar systems, and software-defined radios. They also emphasize research and development to enhance the security, reliability, and efficiency of military communication solutions. Strategic partnerships, mergers, and acquisitions are common strategies employed to expand product offerings and strengthen market presence. As the demand for secure, real-time communication systems rises, these companies continue to innovate, keeping pace with evolving defense needs globally.
Recent Developments
- In March 2024, The U.S. Space Force awarded Boeing a USD 439.6 million contract to build the WGS-12 military communications satellite. The Ministry of Defense announced the signing of the contract on March 1. WGS-12 is the 12th satellite in the Wideband Global Satcom geostationary constellation, which provides communications services to the U.S. and its allies.
- In October 2023, The US Space Systems Command announced its plans to issue a request for proposals in early 2024 for the development of the Evolved Strategic Satellite Communications System (ESS) constellation under a USD 8 billion contract.
- In October 2023, Airbus was awarded the Skynet Design Support (SDSC) contract by the UK to provide Design Authority reach back for the country's SKYNET 5 and 6A military satellite communications systems.
- In August 2023, Ukraine announced that Rheinmetall will supply Ukraine with new Luna NG (next generation) reconnaissance unmanned aircraft systems (UASs). This provision is a segment of a USD 765 million military assistance package committed by the German government for Ukraine, as announced at the NATO summit in Vilnius, Lithuania.
- In May 2023, L3Harris Technologies has disclosed contracts amounting to USD 160 million from the Marine Corps, encompassing multi-channel handheld and vehicular radio systems. This development raises the cumulative program orders to USD 336 million. All U.S. military branches, Special Operations Command, and many key allies have widely embraced the Falcon IV radio family's software-defined framework. This offers adaptability for ongoing updates and effortless incorporation of new technologies for future requirements.
- In June 2023, Raytheon Technologies received a USD 625 million contract from the U.S. Air Force Nuclear Weapons Center to manufacture satellite communication terminals that are resistant to nuclear effects.
Market Concentration & Characteristics
The military communication market is moderately concentrated, with a few leading companies dominating the landscape. Key players such as Raytheon Technologies, Northrop Grumman, and Lockheed Martin hold significant market shares due to their extensive portfolios, technological expertise, and strong government contracts. The market is characterized by high competition, driven by continuous advancements in communication technologies, including satellite, radio, and radar systems. These companies focus on providing integrated solutions that offer secure, reliable, and real-time communication for defense operations. Due to the critical nature of military communication, the market also experiences high barriers to entry, with new players needing substantial investment in research and development to compete. Additionally, ongoing geopolitical tensions and increased defense budgets globally have led to an expanding demand for innovative communication systems. The market is also marked by increasing trends in the adoption of software-defined radios, AI integration, and satellite communication for better network resilience.
Report Coverage
The research report offers an in-depth analysis based on Component, Applications, End User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for secure and reliable communication systems will continue to grow due to rising geopolitical tensions.
- Advancements in satellite communication will enhance connectivity, especially in remote and challenging environments.
- The integration of artificial intelligence will improve real-time decision-making and automated systems in military operations.
- 5G technology will enable faster and more reliable communication, enhancing operational efficiency.
- Cybersecurity measures will become increasingly important as cyber threats to military communication systems rise.
- The use of software-defined radios will provide more flexibility and adaptability in communication systems.
- Interoperability among various defense forces will be a key focus to ensure seamless information sharing.
- Increasing adoption of unmanned systems will require robust communication infrastructure for remote control and data transmission.
- The complexity of military communication systems will drive a need for specialized training and advanced technologies.
- Military communication systems will increasingly rely on network-centric operations to improve coordination across different forces.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Geopolitical Tensions and Increased Defense Spending
Rising geopolitical tensions and global conflicts are prompting nations to boost defense budgets, directly increasing investment in advanced military communication systems to ensure secure and reliable information exchange during operations.
Advancements in Communication Technologies
Continuous innovation in satellite communication, 5G networks, and software-defined radios is transforming military communications, enabling faster, more secure, and higher-capacity data transmission across diverse and challenging environments.
Integration of Unmanned Systems and AI
The growing use of unmanned aerial vehicles and AI-driven systems in military operations requires robust, real-time communication links for remote control, data transmission, and enhanced situational awareness, driving demand for advanced communication infrastructure.
Need for Secure and Reliable Communication
As military missions become more complex and cyber threats escalate, there is a critical need for communication systems that offer high resilience, advanced encryption, and uninterrupted operation to protect sensitive information and maintain command and control.
Focus on Interoperability and Network-Centric Operations
Modern defense strategies emphasize seamless information sharing and coordination across different military branches and allied forces, increasing the demand for interoperable and integrated communication solutions.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Military Communication Market?
What factors are driving the growth of the Military Communication Market?
What are the key segments within the Military Communication Market?
What are some challenges faced by the Military Communication Market?
Who are the major players in the Military Communication Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Air Force
- 1.2.2 Land Force
- 1.2.3 Naval Force
- 1.3 By Component
- 1.3.1 Satellite Communication Systems
- 1.3.2 Radar & Sonar Systems
- 1.3.3 Radio Systems
- 1.3.4 Consulting Services
- 1.3.5 Testing & Integration Services
- 1.3.6 Support & Maintenance Services
- 1.4 By Application
- 1.4.1 Intelligence, Surveillance, and Reconnaissance (ISR)
- 1.4.2 Situational Awareness
- 1.4.3 Command & Control
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 33,125 million → 2032: USD 57,341.8 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Military Communication Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Military Communication Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Military Communication Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Military Communication Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Military Communication Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Military Communication Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Military Communication Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Military Communication Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 33,125 million → 2032: USD 57,341.8 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Military Communication Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Air Force
- 12.3.7.2 Land Force
- 12.3.7.3 Naval Force
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Component - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Satellite Communication Systems
- 12.4.7.2 Radar & Sonar Systems
- 12.4.7.3 Radio Systems
- 12.4.7.4 Consulting Services
- 12.4.7.5 Testing & Integration Services
- 12.4.7.6 Support & Maintenance Services
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Intelligence, Surveillance, and Reconnaissance (ISR)
- 12.5.7.2 Situational Awareness
- 12.5.7.3 Command & Control
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Military Communication End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Military Communication Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Military Communication Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Military Communication Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Northrop Grumman Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Lockheed Martin Corporation
- 18.4 Raytheon Technologies Corporation
- 18.5 Thales Group
- 18.6 Saab AB
- 18.7 L3Harris Technologies Inc.
- 18.8 BAE Systems
- 18.9 Elbit Systems
- 18.10 Viasat Inc.
- 18.11 Leonardo
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

