
Market Overview
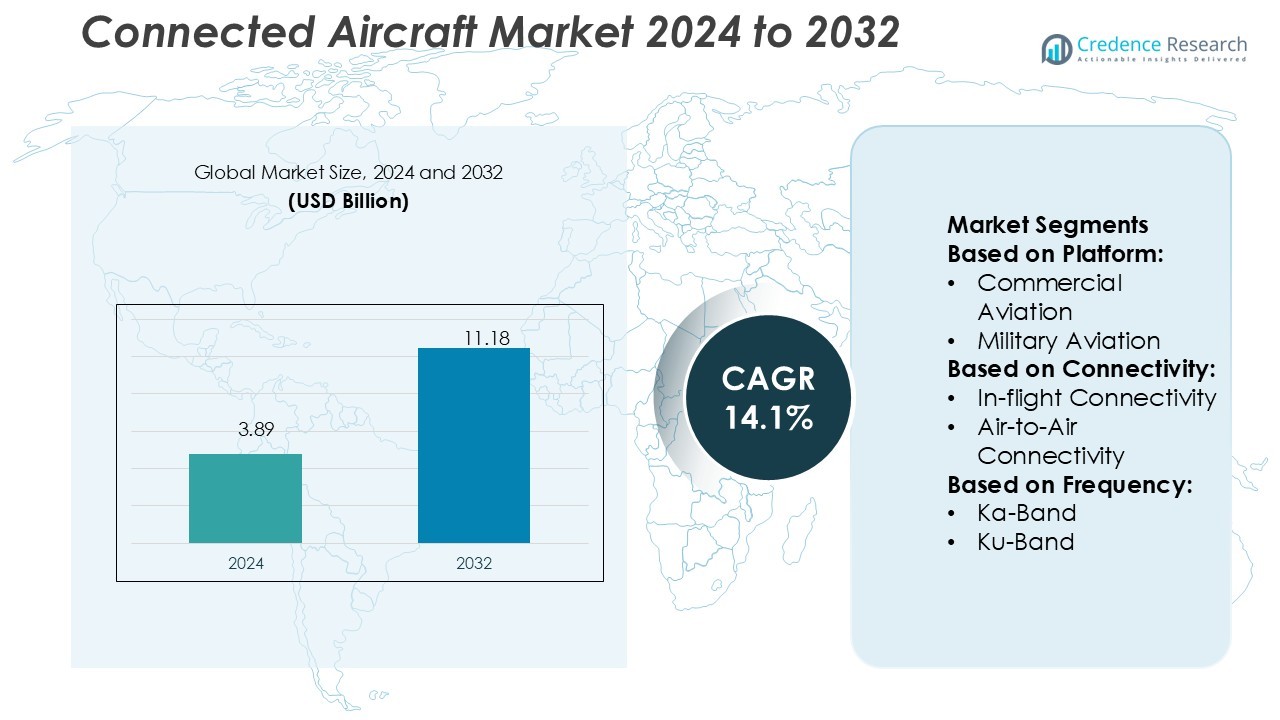
Connected Aircraft Market size was valued USD 3.89 billion in 2024 and is anticipated to reach USD 11.18 billion by 2032, at a CAGR of 14.1% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Connected Aircraft Market Size 2024 | USD 3.89 Billion |
| Connected Aircraft Market, CAGR | 14.1% |
| Connected Aircraft Market Size 2032 | USD 11.18 Billion |
The Connected Aircraft Market is driven by major players including Panasonic Avionics Corporation, Thales Group, Gogo, Burrana Inc., Zodiac Aerospace, Global Eagle Entertainment, BAE Systems PLC, Inmarsat, and Honeywell. These companies focus on advanced in-flight connectivity, real-time communication systems, and secure data solutions to strengthen their global market position. They invest heavily in satellite networks, IoT integration, and software-driven platforms to enhance operational performance and passenger experience. Strategic partnerships with airlines and OEMs help expand their service capabilities. North America leads the global market with a 34% share, supported by strong technological infrastructure, high adoption rates of advanced connectivity systems, and the presence of key aviation technology providers. This leadership is reinforced by ongoing investments in modern air traffic systems and secure communication solutions.
Market Insights
- The Connected Aircraft Market size was valued at USD 3.89 billion in 2024 and is expected to reach USD 11.18 billion by 2032, growing at a CAGR of 14.1%.
- Growing demand for real-time communication, advanced in-flight connectivity, and enhanced passenger experience is driving strong market expansion.
- Key players focus on IoT integration, satellite networks, and software platforms to boost operational efficiency and global service coverage.
- Limited infrastructure in emerging regions and high integration costs remain key restraints, slowing adoption in some markets.
- North America leads with a 34% market share, supported by strong infrastructure and early technology adoption, while commercial aviation represents the dominant segment, accounting for the largest share due to fleet modernization and rising connectivity investments.
Market Segmentation Analysis:
By Platform
Commercial aviation dominates the connected aircraft market with the largest market share. Airlines adopt connected solutions to improve operational efficiency, passenger experience, and flight safety. High passenger traffic drives strong demand for in-flight entertainment, real-time monitoring, and predictive maintenance. For instance, major airlines deploy advanced connectivity systems to support real-time data exchange between aircraft and ground stations. Business and general aviation, military aviation, UAVs, and advanced air mobility are growing segments. Their growth is supported by increased fleet modernization and rising defense budgets.
- For instance, SES and ThinKom, a Gulfstream G-III equipped with Thales’ FlytLIVE logged sustained throughputs exceeding 265 Mbps while switching between GEO and MEO beams mid-flight.
By Connectivity
In-flight connectivity holds the dominant share in the market. Airlines prioritize strong in-flight Wi-Fi and entertainment systems to meet passenger expectations for continuous connectivity. These solutions enhance customer satisfaction and open new revenue streams through premium services. For instance, leading carriers use high-speed satellite communication for seamless streaming and messaging. Air-to-air and air-to-ground connectivity segments are expanding as demand for data sharing and networked flight operations increases. These advancements support predictive maintenance and optimized flight operations.
- For instance, Gogo does offer its AVANCE systems for business aviation, and the number of installations is growing. As of March 31, 2025, total AVANCE aircraft online grew to 4,716, and AVANCE units comprised approximately 68% of total ATG aircraft online.
By Frequency
Ku-band dominates the market with the largest share due to its wide coverage and stable performance. This frequency band supports reliable broadband connections essential for passenger and crew communication. For instance, several airlines use Ku-band satellite networks to offer high-speed Wi-Fi on international routes. Ka-band is growing quickly, offering higher bandwidth for advanced applications. L-band is widely used for safety-critical communications due to its strong signal reliability, especially in challenging weather conditions and remote airspace.
Key Growth Drivers
Rising Demand for High-Speed In-Flight Connectivity
Airlines are investing in advanced connectivity to enhance passenger experience. High-speed Wi-Fi and real-time entertainment services are now core offerings for major carriers. Growing adoption of satellite-based communication networks enables low-latency and uninterrupted service. For instance, Panasonic Avionics has equipped over 3,000 aircraft globally with its broadband systems, ensuring stable in-flight internet. Increasing passenger expectations and business travel demand are driving operators to upgrade legacy systems. This shift strengthens the competitive edge of airlines and accelerates adoption of connected aircraft technologies.
- For instance, Zodiac RAVE™ Centric IFSC became a line-fit option on the Airbus A350 XWB as enabling embedded modular seat-centric systems with independent seat failures (i.e., one seat failure does not impact others).
Expansion of Real-Time Aircraft Data Monitoring
Airlines are leveraging connected systems to monitor aircraft performance in real time. Advanced sensors and IoT solutions collect engine health, flight path, and maintenance data. This data enables predictive maintenance and operational cost reduction. For example, Honeywell’s Connected Aircraft solutions can reduce unscheduled maintenance events by 35%. These insights allow airlines to prevent downtime and enhance safety standards. Growing emphasis on operational efficiency and regulatory compliance is pushing airlines to invest in robust monitoring and analytics solutions.
- For instance, Global Eagle’s Airconnect Global Antenna integrates a three-axis precision pointing mechanism with steerable beams to maintain link continuity even during banking maneuvers, tested across latitudes from –30° to +60° in real flights.
Growth in Unmanned and Advanced Air Mobility Platforms
The rise of unmanned aerial vehicles (UAVs) and electric vertical take-off and landing (eVTOL) aircraft is fueling demand for connected solutions. These platforms rely on constant, secure communication for navigation and traffic management. For instance, Airbus’ Vahana program demonstrated automated flight with real-time ground control through 4G networks. Rapid urbanization and smart city development are supporting this growth. Advanced connectivity enables efficient airspace integration and regulatory compliance, driving wider adoption of connected aircraft technologies across both commercial and defense sectors.
Key Trends & Opportunities
Integration of Satellite and 5G Networks
The convergence of satellite and 5G networks is transforming aircraft connectivity. Hybrid systems enable low-latency, high-speed data transfer for both cockpit and cabin operations. Companies like Viasat and Inmarsat are expanding satellite constellations to improve coverage. This integration supports seamless streaming, predictive analytics, and advanced operational applications. It creates opportunities for airlines to offer premium services and optimize route management, making connected aircraft a strategic asset.
- For instance, BAE also maintains over 1,000 flight computers on more than 300 satellites, which cumulatively have logged more than 10,000 years of in-orbit flight time.
Shift Toward Predictive Maintenance Models
Predictive maintenance is gaining traction as airlines seek to minimize downtime. Connected sensors continuously monitor aircraft systems, identifying issues before they escalate. Boeing’s AnalytX platform, for example, analyzes over 100 million flight data points daily. This proactive approach reduces maintenance costs and enhances fleet availability. As regulatory frameworks evolve, predictive solutions offer airlines a competitive advantage through cost savings, safety improvements, and operational resilience.
- For instance, Panasonic’s Converix™ platform can access over 10,000 datapoints across an aircraft and analyze multiple terabytes of structured and unstructured data to generate daily reports to airlines.
Advancements in Cybersecurity Solutions
As connectivity expands, cybersecurity remains a top priority. Aircraft systems are adopting advanced encryption and real-time threat detection to safeguard operations. Companies like Collins Aerospace are developing intrusion detection systems tailored for aviation. Strengthening cybersecurity builds passenger trust and ensures regulatory compliance. The demand for secure digital ecosystems presents opportunities for new product offerings and strategic partnerships within the connected aircraft ecosystem.
Key Challenges
High Implementation and Operational Costs
The deployment of connected aircraft technologies requires significant investment. Upgrading existing fleets with satellite antennas, routers, and cybersecurity solutions can be costly. Smaller carriers face budget constraints, slowing adoption. Additionally, ongoing maintenance and bandwidth fees add to operational costs. This creates a market divide between large airlines and regional operators, impacting overall connectivity penetration rates.
Complex Regulatory and Airspace Integration Issues
Integration of connected aircraft systems must comply with strict aviation safety and communication standards. Varying international regulations create operational complexity for global carriers. Coordinating between aviation authorities, satellite operators, and telecom providers can delay implementation. Moreover, managing airspace for UAVs and eVTOLs adds further challenges. This regulatory complexity can hinder large-scale deployment and slow market growth.
Regional Analysis
North America
North America leads the Connected Aircraft Market with a 34% market share. The region benefits from strong investment in aerospace connectivity, advanced air traffic infrastructure, and early adoption of IoT technologies. Airlines focus on improving operational efficiency and passenger experience through high-speed in-flight connectivity. The U.S. dominates due to major OEMs like Boeing and leading communication providers driving innovation. Government initiatives to modernize air traffic control also strengthen market growth. The increasing demand for real-time flight data and seamless communication makes North America a critical hub for connected aircraft advancements.
Europe
Europe holds a 27% market share in the Connected Aircraft Market, supported by robust aviation regulations and technology integration programs. Countries such as the U.K., Germany, and France are key contributors, with airlines adopting advanced satellite communication systems. The European Union’s Single European Sky initiative boosts real-time aircraft monitoring and interoperability. Airbus plays a major role in driving connectivity solutions across fleets. The region also invests in cybersecurity measures to protect digital flight operations. Strategic collaborations between airlines, equipment suppliers, and telecom firms continue to accelerate market growth.
Asia-Pacific
Asia-Pacific accounts for a 25% market share, making it one of the fastest-growing regions in the Connected Aircraft Market. Rapid expansion of commercial aviation and rising passenger traffic drive strong demand for connectivity solutions. Countries like China, Japan, and India are increasing investments in in-flight connectivity and real-time operational monitoring. Regional airlines focus on improving flight safety, efficiency, and customer experience. Major OEMs and telecom operators are partnering to expand satellite and 5G infrastructure. Low-cost carriers are also integrating connected aircraft systems to stay competitive and enhance service quality.
Latin America
Latin America holds a 5% market share in the Connected Aircraft Market. Regional airlines are adopting connectivity solutions to improve operational performance and passenger experience. Brazil and Mexico lead the regional adoption due to rising air traffic and modernized fleet operations. Infrastructure upgrades and partnerships with satellite communication providers are expanding coverage and reliability. Although market penetration remains lower than in other regions, strong aviation growth and supportive regulatory efforts are expected to accelerate adoption. The region presents emerging opportunities for connected aircraft technology providers.
Middle East & Africa
The Middle East & Africa region captures a 9% market share in the Connected Aircraft Market. The region’s growth is driven by major airlines like Emirates, Qatar Airways, and Etihad, which prioritize premium connectivity for passengers. Investments in airport modernization and satellite coverage expansion support this demand. Gulf countries lead in adopting real-time aircraft tracking and advanced communication solutions. Africa is gradually upgrading aviation infrastructure, enabling new opportunities. Government support for smart aviation initiatives further enhances connectivity adoption, particularly in major aviation hubs across the Middle East.
Market Segmentations:
By Platform:
- Commercial Aviation
- Military Aviation
By Connectivity:
- In-flight Connectivity
- Air-to-Air Connectivity
By Frequency:
- Ka-Band
- Ku-Band
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Connected Aircraft Market features prominent players such as Panasonic Avionics Corporation, Thales Group, Gogo, Burrana Inc., Zodiac Aerospace, Global Eagle Entertainment, BAE Systems PLC, Panasonic Avionics, Inmarsat, and Honeywell. The competitive landscape of the Connected Aircraft Market is characterized by strong technological innovation and strategic collaborations. Companies focus on developing advanced in-flight connectivity, real-time data exchange, and secure communication systems to enhance operational efficiency. Growing investment in satellite networks, IoT integration, and cybersecurity strengthens market positioning and service reliability. Many players emphasize product diversification through hardware-software integration, enabling better passenger experiences and improved airline performance. Strategic alliances with OEMs and MRO providers expand global reach and ensure system compatibility. This competitive environment encourages continuous innovation, price competitiveness, and market consolidation, reinforcing connected aircraft technologies as a core element of modern aviation infrastructure.
Key Player Analysis
- Panasonic Avionics Corporation
- Thales Group
- Gogo
- Burrana Inc.
- Zodiac Aerospace
- Global Eagle Entertainment
- BAE Systems PLC
- Panasonic Avionics
- Inmarsat
- Honeywell
Recent Developments
- In June 2025, Qatar Airways selected Panasonic Avionics’ Converix platform for 60 B777X aircraft, adding AI-powered virtual cabin crew and integrated data management.
- In May 2025, China National Aero-Technology Import & Export Corporation (CATIC) showcased its standalone weapon fire control system (SWFCS) at the 2025 Langkawi International Maritime and Aerospace (LIMA) Exhibition, which was held from May 19 to May 24 in Malaysia.
- In April 2025, Dynamatic Technologies Limited, an Indian aerostructure manufacturer, and Deutsche Aircraft, a German regional aircraft OEM for sustainable aviation, jointly inaugurated the rear fuselage assembly line for the 40-seater D328eco turboprop aircraft at Dynamatic's advanced aerospace facility located outside Bangalore.
- In October 2024, Prime Minister Narendra Modi inaugurated the TATA Aircraft Complex to produce C-295 aircraft with his Spanish counterpart, Pedro Sanchez, in Vadodara, Gujarat.
Report Coverage
The research report offers an in-depth analysis based on Platform, Connectivity, Frequency and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will see rapid expansion with growing demand for real-time data exchange.
- Airlines will increasingly adopt advanced in-flight connectivity solutions to enhance passenger experience.
- Integration of 5G technology will enable faster and more reliable communication networks.
- Satellite-based systems will play a key role in expanding global coverage for connected aircraft.
- Cybersecurity solutions will gain more focus to protect critical aviation data.
- Partnerships between airlines, telecom operators, and OEMs will accelerate technology deployment.
- IoT-enabled aircraft operations will improve flight safety and operational efficiency.
- AI and analytics will support predictive maintenance and better fleet management.
- Regulatory frameworks will evolve to support seamless and secure aviation connectivity.
- Market competition will intensify as more players invest in digital aviation technologies.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Connected Aircraft Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Connected Aircraft Market projected to grow between 2025 and 2032?
Which Connected Aircraft Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Connected Aircraft Market?
Who are the leading companies in the Connected Aircraft Market?
Which region commanded the largest share of the Connected Aircraft Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 3.89 billion → 2032: USD 11.18 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Connected Aircraft Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Connected Aircraft Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Connected Aircraft Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Connected Aircraft Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Connected Aircraft Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Connected Aircraft Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Connected Aircraft Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Connected Aircraft Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 3.89 billion → 2032: USD 11.18 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Connected Aircraft Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Connected Aircraft Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Connected Aircraft Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Connected Aircraft Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

