
Market Overview
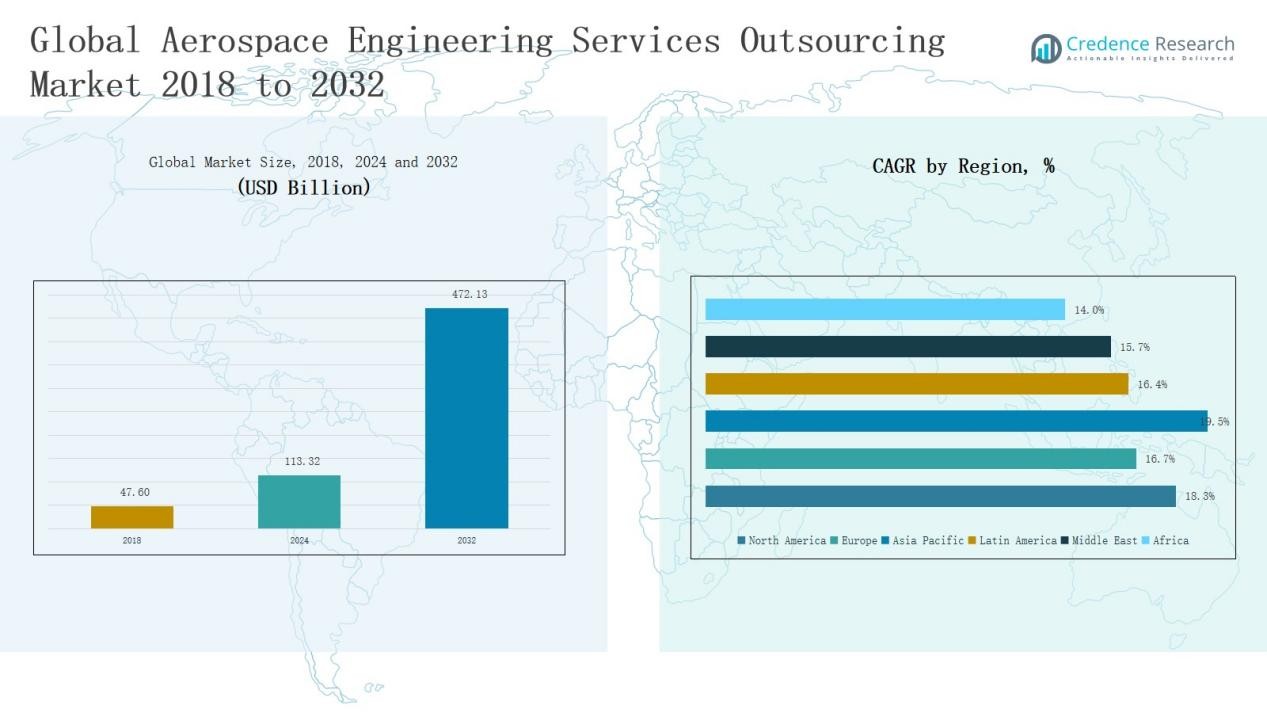
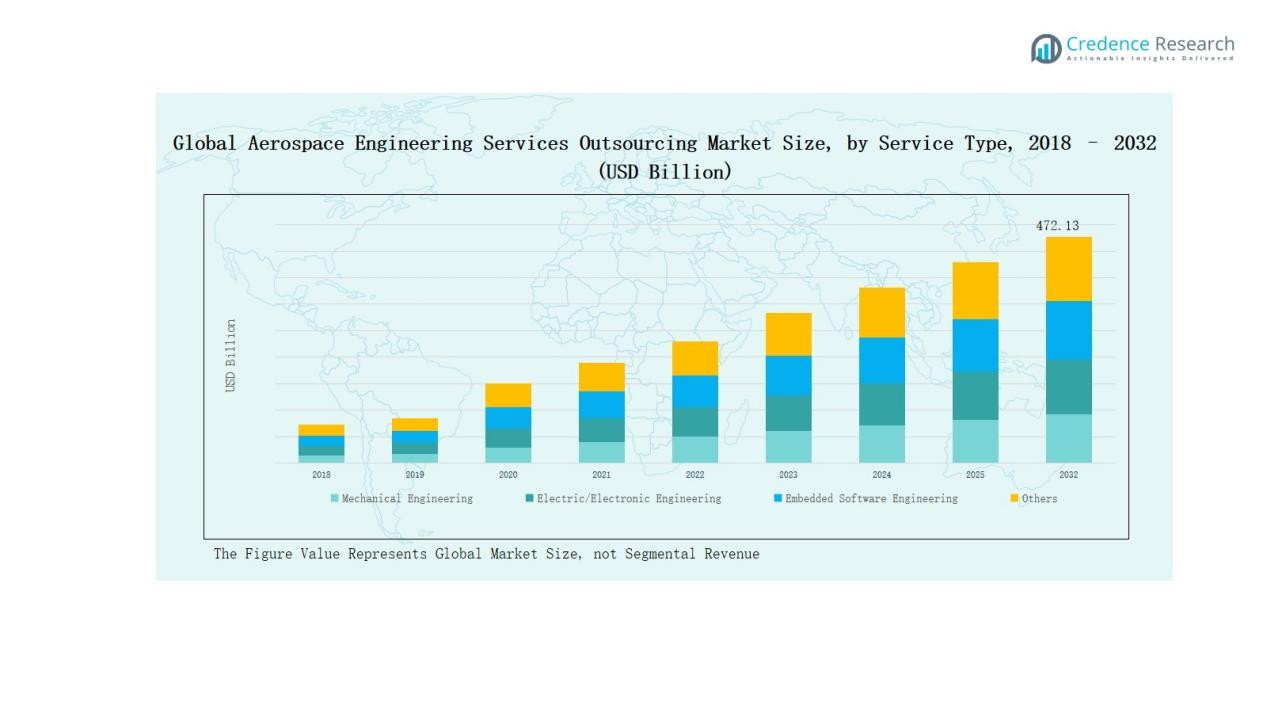
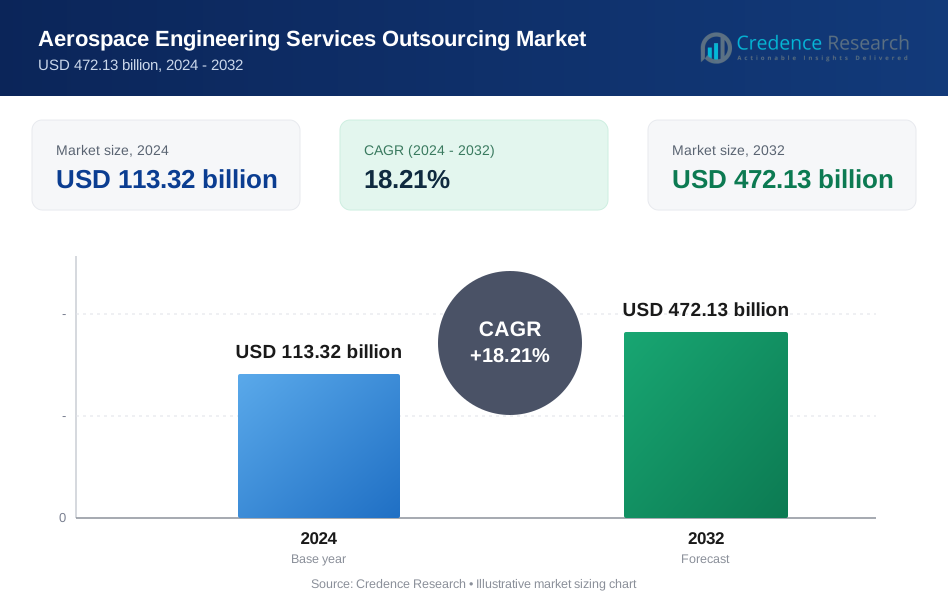
The Aerospace Engineering Services Outsourcing Market was valued at USD 47.60 billion in 2018, grew to USD 113.32 billion in 2024, and is anticipated to reach USD 472.13 billion by 2032, expanding at a CAGR of 18.21% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Aerospace Engineering Services Outsourcing Market Size 2024 | USD 113.32 Billion |
| Aerospace Engineering Services Outsourcing Market, CAGR | 18.21% |
| Aerospace Engineering Services Outsourcing Market Size 2032 | USD 472.13 Billion |
The Aerospace Engineering Services Outsourcing Market features strong competition among global leaders such as Altair Engineering Inc., Alten Group, Capgemini, Bertrandt AG, Honeywell International Inc., ITK Engineering GmbH, Tech Mahindra Limited, HCL Technologies Limited, Tata Consultancy Services Limited (TCS), and L&T Technology Services. These companies drive growth through advanced design, simulation, and digital engineering capabilities, offering end-to-end solutions to major OEMs and Tier 1 suppliers. Strategic collaborations, AI integration, and sustainable design development strengthen their market positions. North America emerged as the leading region in 2024 with a 44% share, supported by robust aerospace infrastructure, extensive R&D activities, and long-standing outsourcing partnerships with global manufacturers.
Market Insights
- The Aerospace Engineering Services Outsourcing Market grew from USD 47.60 billion in 2018 to USD 113.32 billion in 2024 and is projected to reach USD 472.13 billion by 2032, expanding at a CAGR of 18.21%.
- North America led the market with a 44% share in 2024, driven by high R&D investments, OEM presence, and digital engineering adoption across the U.S. aerospace industry.
- Mechanical Engineering dominated by service type with a 38% share, fueled by rising demand for component testing, system integration, and adoption of 3D modeling and digital twin technologies.
- Design held the largest function share at 41%, supported by lightweight component innovation and reduced development cycles through simulation and digital validation tools.
- Offshore outsourcing captured 64% of the market, supported by cost-effective engineering talent in India, the Philippines, and Eastern Europe, enhancing large-scale aerospace project efficiency.
Market Segment Insights
By Service Type
Mechanical Engineering dominated the Aerospace Engineering Services Outsourcing Market in 2024 with a 38% share. The segment benefits from strong demand for structural design, component testing, and system integration in aircraft manufacturing. Growing adoption of advanced materials, 3D modeling, and digital twin technologies has further expanded outsourcing needs. Electric/Electronic Engineering and Embedded Software Engineering are gaining traction due to avionics modernization, autonomous flight systems, and the shift toward electric and hybrid propulsion platforms.
By Function
Design accounted for the largest share of 41% in 2024, driven by continuous innovation in aircraft structures, aerodynamics, and lightweight component development. OEMs and Tier 1 suppliers increasingly outsource design functions to reduce costs and shorten development cycles. Simulation & Digital Validation is also expanding rapidly, supported by advanced computational tools that help enhance performance, reliability, and safety standards while minimizing physical prototyping costs for aerospace manufacturers.
- For instance, Boeing expanded its use of Siemens’ digital validation tools to conduct virtual certification of aircraft systems, which significantly reduced physical prototype requirements and accelerated performance testing.
By Location
Offshore services held the leading position with a 64% market share in 2024. The growth is fueled by the availability of skilled engineers, lower operational costs, and expanding aerospace clusters in India, the Philippines, and Eastern Europe. Many global aerospace OEMs rely on offshore partners for high-volume design, analysis, and digital validation projects. Onshore outsourcing continues to grow steadily in regions requiring strict data security and compliance with aerospace regulatory frameworks.
- For instance, India’s Infosys reported expanding its aerospace engineering delivery by setting up a new facility in Bengaluru to support digital aero-structure validation projects for leading OEMs.
Key Growth Drivers
Rising Aircraft Production and Fleet Modernization
The continuous rise in global aircraft production and modernization programs drives the Aerospace Engineering Services Outsourcing Market. Airlines are upgrading fleets to meet stricter fuel efficiency and emission standards. OEMs and Tier 1 suppliers outsource engineering functions to reduce turnaround time and improve innovation. Outsourced service providers deliver design, testing, and validation expertise, supporting faster development of next-generation aircraft and sustainable aviation technologies.
- For instance, TAP Air Portugal implemented IATA FuelIS, an advanced analytics solution, enabling the airline to optimize fleet fuel consumption and benchmark environmental performance against global peers using verified data from over 220 contributing airlines.
Increasing Adoption of Digital Engineering Solutions
The growing use of digital tools such as simulation, digital twin, and 3D modeling fuels outsourcing demand. Aerospace companies are adopting advanced software platforms for faster prototyping and cost-efficient product validation. Service providers specializing in digital engineering enable real-time collaboration and optimization across the supply chain. This adoption enhances operational flexibility and helps manufacturers manage complex design cycles and compliance standards in modern aircraft programs.
- For instance, Rolls-Royce advanced its use of digital twin technology for aero-engine performance monitoring through the IntelligentEngine program, enabling predictive maintenance and faster validation.
Cost Efficiency and Access to Skilled Workforce
Cost optimization and access to a global talent pool remain key outsourcing drivers. Aerospace OEMs prefer engineering hubs in Asia-Pacific and Eastern Europe to leverage skilled engineers at lower costs. Outsourcing firms offer multidisciplinary expertise in mechanical, software, and electronic systems, reducing internal R&D overhead. This approach allows OEMs to focus on core innovation while external partners handle complex design, analysis, and digital integration processes efficiently.
Key Trends & Opportunities
Shift Toward Sustainable and Electric Aviation
The market is witnessing a growing focus on sustainability and electrification. Engineering service providers are increasingly involved in developing electric propulsion systems, lightweight materials, and energy-efficient designs. Collaborations with OEMs on green aviation programs create strong growth opportunities. This trend aligns with global carbon reduction targets and accelerates the adoption of innovative, eco-friendly aircraft systems through specialized outsourced design and simulation support.
- For instance, the Electra EL-2 Goldfinch, an electric short takeoff and landing (eSTOL) demonstrator, uses distributed electric propulsion and completed its first crewed flight on November 20, 2023, showcasing advancements in hybrid-electric aviation technology.
Expansion of Aerospace Digitalization and AI Integration
The integration of artificial intelligence, automation, and cloud-based platforms is transforming aerospace engineering services. Companies are using AI for predictive maintenance, structural analysis, and design optimization. Outsourcing partners offering AI-driven solutions gain competitive advantage by improving accuracy and reducing engineering timelines. The demand for digital collaboration platforms and data analytics tools presents major opportunities for technology-driven service providers in the global aerospace ecosystem.
- For instance, Air France-KLM partnered with Google Cloud in December 2024 to implement generative AI for predictive maintenance, cutting data analysis time from hours to minutes and enhancing operational efficiency.
Key Challenges
Data Security and Intellectual Property Concerns
Outsourcing complex aerospace engineering tasks raises significant data security and IP protection challenges. Sensitive design data shared across borders increases risks of cyberattacks and information leaks. Regulatory compliance and export control laws demand strict security frameworks. Companies must ensure that outsourcing partners maintain certified systems and secure networks to protect proprietary technologies and classified information in global collaboration environments.
Regulatory and Quality Compliance Complexity
The aerospace industry operates under strict international standards such as AS9100, DO-178C, and FAA/EASA regulations. Ensuring consistent compliance across outsourced operations remains difficult. Service providers must maintain high-quality documentation, testing validation, and process traceability. Failure to meet compliance standards can delay certification or lead to financial penalties. Continuous audits and alignment with OEM quality systems are essential for sustaining outsourcing partnerships.
Talent Retention and Skill Shortage
The market faces growing challenges in retaining skilled aerospace engineers, particularly in digital systems and embedded software. High turnover rates and talent migration affect project continuity. Outsourcing firms must invest in upskilling and workforce development to meet evolving technical requirements. Competition for expertise in emerging fields like AI-driven design and avionics integration further pressures service providers to maintain strong retention and training programs.
Regional Analysis
North America
North America dominated the Aerospace Engineering Services Outsourcing Market in 2024 with a 44% share. The market grew from USD 21.11 billion in 2018 to USD 49.74 billion in 2024 and is projected to reach USD 207.79 billion by 2032, expanding at a CAGR of 18.3%. Growth is driven by high R&D investments, strong OEM presence, and increased demand for digital engineering in aircraft production. The U.S. leads regional outsourcing due to advanced aerospace infrastructure and partnerships between OEMs and specialized engineering service providers.
Europe
Europe held a 17% market share in 2024, valued at USD 18.71 billion, up from USD 8.35 billion in 2018, and is expected to reach USD 70.40 billion by 2032, growing at a CAGR of 16.7%. The region benefits from the presence of Airbus, Rolls-Royce, and Safran, which increasingly outsource engineering activities for cost efficiency. Rising adoption of sustainable aviation technologies and electric propulsion design supports steady outsourcing growth, particularly across France, Germany, and the UK.
Asia Pacific
Asia Pacific ranked second globally with a 27% share in 2024, increasing from USD 13.97 billion in 2018 to USD 35.08 billion in 2024, and projected to reach USD 159.22 billion by 2032, at the fastest CAGR of 19.5%. The region’s growth is fueled by expanding aerospace clusters in India, China, and Japan, offering cost-effective and skilled engineering talent. Favorable government policies, digitalization, and increased participation of outsourcing firms in aircraft design and simulation strengthen Asia Pacific’s leadership potential.
Latin America
Latin America accounted for a 6% market share in 2024, rising from USD 2.25 billion in 2018 to USD 5.29 billion in 2024, and expected to reach USD 19.49 billion by 2032, growing at a CAGR of 16.4%. The region’s growth is supported by Brazil’s aerospace industry and increasing collaborations with international OEMs. Outsourcing in manufacturing design and simulation services is expanding, driven by local engineering capabilities and investment in technology-based partnerships.
Middle East
The Middle East represented a 4% market share in 2024, valued at USD 2.93 billion, up from USD 1.34 billion in 2018, and projected to reach USD 10.31 billion by 2032, registering a CAGR of 15.7%. The region’s growth is propelled by aviation infrastructure expansion in GCC countries and aerospace diversification initiatives. Increased government spending on MRO and engineering hubs strengthens outsourcing opportunities.
Africa
Africa captured a 2% market share in 2024, growing from USD 0.58 billion in 2018 to USD 1.57 billion in 2024, and projected to reach USD 4.92 billion by 2032, expanding at a CAGR of 14.0%. The market is emerging with growing MRO facilities and localized aerospace training programs. Partnerships with global aerospace companies are gradually supporting technology transfer and engineering service expansion across key nations such as South Africa and Egypt.
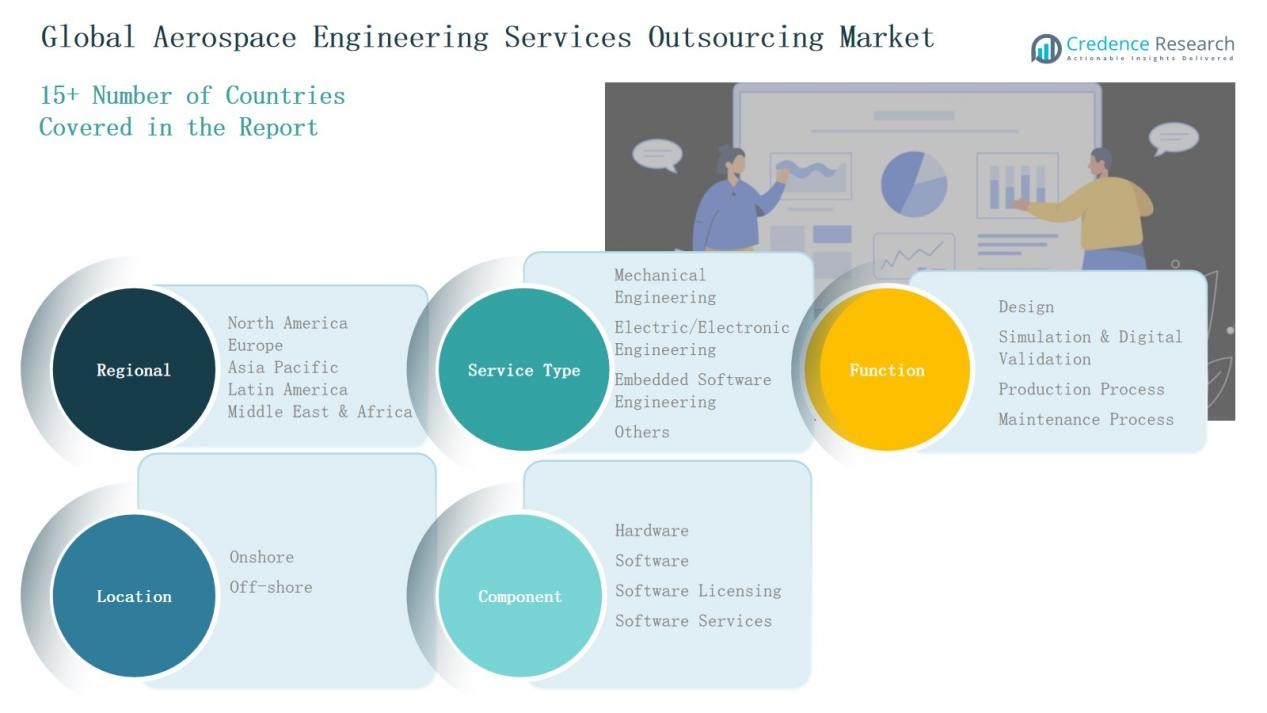
Market Segmentations:
By Service Type
- Mechanical Engineering
- Electric/Electronic Engineering
- Embedded Software Engineering
- Others
By Function
- Design
- Simulation & Digital Validation
- Production Process
- Maintenance Process
By Location
- Onshore
- Offshore
By Component
- Hardware
- Software
- Software Licensing
- Software Services
By Region
North America
- U.S.
- Canada
- Mexico
Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Rest of Europe
Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Southeast Asia
- Rest of Asia Pacific
Latin America
- Brazil
- Argentina
- Rest of Latin America
Middle East
- GCC Countries
- Israel
- Turkey
- Rest of Middle East
Africa
- South Africa
- Egypt
- Rest of Africa
Competitive Landscape
The Aerospace Engineering Services Outsourcing Market is highly competitive, with global and regional players offering specialized engineering, design, and digital solutions to major OEMs and Tier 1 suppliers. Key companies such as Altair Engineering Inc., Alten Group, Capgemini, Bertrandt AG, Honeywell International Inc. and ITK Engineering GmbH dominate through diversified service portfolios and long-term partnerships with aircraft manufacturers. Firms compete on innovation, technical expertise, and digital transformation capabilities, including simulation, digital twin, and AI-driven analytics. Strategic alliances, mergers, and acquisitions are common as companies expand global delivery centers and strengthen aerospace-specific offerings. Asia Pacific-based service providers increasingly gain prominence due to cost advantages and engineering talent availability. Continuous investment in advanced technologies, cybersecurity, and compliance standards defines the competitive differentiation across this rapidly expanding global outsourcing landscape.
Key Players
- Altair Engineering Inc.
- Alten Group
- Capgemini
- Bertrandt AG
- EWI
- Honeywell International Inc.
- ITK Engineering GmbH
Recent Developments
- In October 2025, Expleo entered a strategic agreement with Deutsche Aircraft to provide advanced aerospace engineering services aimed at enhancing next-generation aircraft development.
- In September 2025, Accenture completed the acquisition of SIPAL’s Integrated Product Support (IPS) business in Italy, expanding its aerospace and defense engineering capabilities.
- In July 2025, Chorus Aviation agreed to acquire Elisen & Associates Inc., a firm in aerospace engineering and certification services.
- In September 2025, Accenture announced intent to acquire Orlade Group (France), which offers advisory and project management for aerospace, defense, and capital projects.
Report Coverage
The research report offers an in-depth analysis based on Service Type, Function, Location, Component and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for outsourced aerospace engineering services will grow with rising aircraft production.
- Digital engineering adoption will expand through AI, simulation, and digital twin technologies.
- OEMs will increasingly partner with offshore service providers for cost optimization.
- Sustainability goals will boost demand for lightweight materials and electric propulsion design.
- Integrated design-to-manufacturing solutions will drive collaboration between OEMs and service firms.
- Asia Pacific will continue to emerge as a global outsourcing hub for aerospace development.
- Increased focus on cybersecurity and data protection will shape vendor selection criteria.
- Cloud-based engineering platforms will enhance remote collaboration and design validation.
- Skilled workforce shortages will encourage automation and training investments in outsourcing centers.
- Strategic mergers and partnerships will accelerate innovation and expand global engineering capacity.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Aerospace Engineering Services Outsourcing Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Aerospace Engineering Services Outsourcing Market projected to grow between 2025 and 2032?
Which Aerospace Engineering Services Outsourcing Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Aerospace Engineering Services Outsourcing Market?
Who are the leading companies in the Aerospace Engineering Services Outsourcing Market?
Which region commanded the largest share of the Aerospace Engineering Services Outsourcing Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Aerospace Engineering Services Outsourcing Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Aerospace Engineering Services Outsourcing Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 113.32 billion → 2032: USD 472.13 billion)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Aerospace Engineering Services Outsourcing Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Aerospace Engineering Services Outsourcing Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Aerospace Engineering Services Outsourcing Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Aerospace Engineering Services Outsourcing Market Drivers
- 3.3 Aerospace Engineering Services Outsourcing Market Restraints & Challenges
- 3.4 Aerospace Engineering Services Outsourcing Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Aerospace Engineering Services Outsourcing Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Aerospace Engineering Services Outsourcing Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Aerospace Engineering Services Outsourcing category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Aerospace Engineering Services Outsourcing Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Aerospace Engineering Services Outsourcing Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Aerospace Engineering Services Outsourcing. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Aerospace Engineering Services Outsourcing Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Aerospace Engineering Services Outsourcing Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Aerospace Engineering Services Outsourcing Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Aerospace Engineering Services Outsourcing (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Aerospace Engineering Services Outsourcing
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Aerospace Engineering Services Outsourcing Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Aerospace Engineering Services Outsourcing Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Aerospace Engineering Services Outsourcing Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Aerospace Engineering Services Outsourcing Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Aerospace Engineering Services Outsourcing Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Aerospace Engineering Services Outsourcing Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Aerospace Engineering Services Outsourcing Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Aerospace Engineering Services Outsourcing Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
