
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| MRO Distribution Market Size 2024 | USD 641,620 Million |
| MRO Distribution Market, CAGR | 2.77% |
| MRO Distribution Market Size 2032 | USD 798,378.33 Million |
Market Overview:
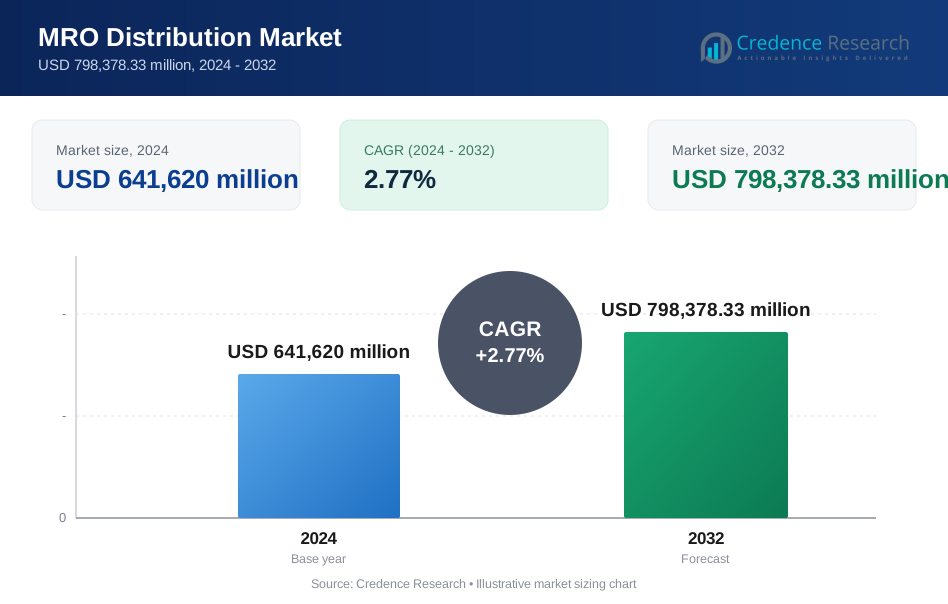
The MRO Distribution Market is projected to grow from USD 641,620 million in 2024 to USD 798,378.33 million by 2032, with a compound annual growth rate (CAGR) of 2.77%.
The MRO distribution market is driven by increasing industrialization, infrastructure development, and the growing need for equipment maintenance across various sectors. Companies are prioritizing efficiency, reliability, and cost control, leading to a greater demand for MRO services to ensure seamless operations. Technological advancements, such as the adoption of predictive maintenance and smart solutions, are further shaping the market by optimizing supply chains and reducing downtime. E-commerce platforms are also gaining traction, allowing businesses to streamline procurement processes and access a wider range of products. Moreover, the rise of sustainability initiatives is encouraging the use of eco-friendly materials and energy-efficient equipment, adding to market growth. As companies focus on reducing operational risks and extending asset lifecycles, the MRO distribution market is set to witness steady expansion.
The MRO distribution market exhibits diverse growth patterns across key regions, with North America leading with a 35% market share in 2024 due to its established industrial sectors and advanced technological adoption. Europe holds 25%, driven by strong manufacturing bases in Germany, France, and the UK, alongside growing sustainability efforts. Asia-Pacific, with a 30% share, shows rapid growth due to industrialization in China, India, and Japan, while Latin America accounts for 7%, supported by Brazil and Mexico's manufacturing and energy sectors. The Middle East and Africa region captures 3%, fueled by infrastructure and energy investments. Leading players in the market include ABB Group, Cromwell Group, Ferguson plc, Festo AG & Co. KG, and Graco, Inc., among others, actively expanding their regional presence and product offerings.
Market Insights:
- The MRO distribution market is projected to grow from USD 641,620 million in 2024 to USD 798,378.33 million by 2032, with a CAGR of 2.77%.
- Industrialization and infrastructure development across sectors drive the demand for maintenance, repair, and operations (MRO) products and services.
- Technological advancements, such as predictive maintenance and smart solutions, enhance supply chain efficiency and reduce operational downtime in the MRO market.
- E-commerce platforms are gaining prominence, streamlining procurement processes and offering businesses a broader product selection.
- Sustainability initiatives are influencing the MRO market, with a growing demand for eco-friendly materials and energy-efficient equipment.
- North America holds a 35% market share in 2024, leading the MRO distribution market, followed by Europe with 25% and Asia-Pacific with 30%.
- Key players in the MRO distribution market include ABB Group, Ferguson plc, Festo AG & Co. KG, Graco, Inc., and Cromwell Group, among others.
Market Drivers:
Industrial Growth and Infrastructure Development:
The MRO distribution market is heavily influenced by rapid industrialization and the expansion of infrastructure globally. As manufacturing industries, power plants, and construction sectors grow, the demand for maintenance, repair, and operational supplies increases. These industries require consistent upkeep and repair of machinery and equipment, driving the need for efficient MRO services. The expansion of infrastructure, especially in emerging economies, is further boosting the market, as companies look to maintain operational continuity and improve efficiency.
Focus on Operational Efficiency and Cost Control:
Companies across sectors are increasingly focusing on reducing downtime and enhancing the longevity of their assets. MRO services play a critical role in helping businesses maintain operational efficiency and manage costs. By ensuring that equipment is well-maintained and properly repaired, companies can avoid costly breakdowns and production halts. For instance, For instance, in September 2024, Dassault Aviation announced a new subsidiary in Noida, India, named Dassault Aviation MRO India (DAMROI), to focus on the maintenance, repair, and overhaul of military aircraft. This growing emphasis on preventive maintenance and repair is a key driver for the MRO distribution market, as organizations look to optimize their operations while minimizing unnecessary expenses.
Technological Advancements and Smart Solutions:
The rise of new technologies, such as predictive maintenance and the Internet of Things (IoT), is transforming the MRO distribution market. Predictive maintenance allows businesses to monitor equipment in real time, identifying potential failures before they occur and reducing downtime. For instance, IoT-enabled solutions from companies like Siemens and Schneider Electric allow businesses to monitor machinery performance and automate inventory management, improving efficiency. IoT-enabled devices and smart sensors are also improving the supply chain by offering insights into inventory management and product performance. These technological advancements are fueling demand for MRO products that are compatible with modern systems, further propelling the market forward.
Sustainability and Eco-friendly Initiatives:
Environmental concerns and the push for sustainability are shaping the MRO distribution market. Companies are increasingly adopting eco-friendly materials, energy-efficient equipment, and sustainable practices to meet regulatory standards and reduce their carbon footprint. This shift towards sustainability is driving demand for greener MRO solutions, which is expected to significantly influence market growth in the coming years.
Market Trends:
Commerce and Digital Transformation:The MRO distribution market is experiencing a significant shift towards digital platforms, with companies increasingly utilizing e-commerce to streamline procurement processes. Digital transformation has enabled faster, more efficient purchasing, allowing businesses to access a wider range of products and services online. This trend is not only enhancing convenience but also enabling companies to track and manage their supply chains more effectively. As digital adoption grows, distributors are leveraging e-commerce platforms to expand their reach, enhance customer engagement, and offer more tailored solutions.
Adoption of Predictive Maintenance and IoT:
Technological advancements, particularly in predictive maintenance and the Internet of Things (IoT), are reshaping the MRO landscape. Predictive maintenance solutions use data analytics to monitor equipment conditions in real time, helping companies detect potential issues before they lead to costly downtime. IoT-enabled devices further support this trend by providing real-time monitoring, tracking, and data collection. For instance, Airbus enhanced its Skywise digital platform to support predictive maintenance. EasyJet reported that Skywise predictive tools helped it avoid 35 technical cancellations in August 2022. The integration of these technologies is enabling businesses to optimize their maintenance processes and improve equipment reliability, creating greater demand for smart MRO solutions.
Increased Focus on Sustainability:
Sustainability is becoming a critical consideration in the MRO distribution market. Companies are actively seeking eco-friendly products and services to reduce their environmental impact and comply with stricter regulations. This trend includes the adoption of energy-efficient equipment, recyclable materials, and sustainable maintenance practices. As businesses increasingly prioritize sustainability, distributors are expanding their offerings to include more environmentally friendly options, aligning with corporate sustainability goals and market demand.
Customized and Value-added Services:
There is a growing trend towards offering customized and value-added services in the MRO distribution market. Companies are seeking personalized solutions that meet their specific maintenance and repair needs. For instance, Fastenal provides tailored inventory management solutions and on-site services to help businesses streamline their operations. Distributors are responding by providing tailored products, technical support, and after-sales services, helping businesses optimize their operations and achieve greater efficiency. These value-added offerings are enhancing customer loyalty and driving market competitiveness.
Market Challenges Analysis:
Supply Chain Disruptions and Material Shortages:
The MRO distribution market faces significant challenges due to ongoing supply chain disruptions and material shortages. Global events, such as the COVID-19 pandemic, geopolitical tensions, and economic fluctuations, have severely strained supply chains, leading to production delays and shortages of critical MRO products. These disruptions make it difficult for distributors to maintain optimal inventory levels and meet customer demands promptly. Material shortages, particularly in raw components used in manufacturing and repair, have further worsened the situation, forcing companies to pay premium prices for limited resources. For instance, Grainger and Fastenal are investing in digital platforms to improve customer experience and streamline procurement processes, helping them to capture a larger market share by offering value-added services and customized solutions. This, in turn, increases operational costs and pressures profit margins across the industry. Additionally, fluctuating transportation and shipping costs, coupled with unpredictable lead times, further exacerbate these challenges, compelling businesses to explore alternative sourcing strategies, such as nearshoring or local suppliers, to mitigate risks. Adapting to these evolving conditions requires distributors to adopt flexible, agile approaches to their supply chain management while balancing inventory costs and availability.
Rising Competition and Pressure on Margins:
Another challenge in the MRO distribution market is the intensifying competition, particularly due to the rise of e-commerce platforms and large-scale distributors offering comprehensive product portfolios at competitive prices. The growing shift towards digital procurement enables new entrants to compete with well-established players, creating increased pressure on smaller distributors to differentiate their offerings. This heightened competition often leads to price wars, compressing profit margins and making it difficult for many businesses to maintain profitability. Additionally, customer expectations for faster delivery, wider product variety, and enhanced value-added services, such as technical support and customized solutions, further strain traditional distributors. To remain competitive, many businesses must invest heavily in technology, automation, and supply chain optimization. However, these investments can be financially burdensome for smaller and mid-sized players, creating a significant challenge in balancing cost-effectiveness with the need for innovation. As competition continues to rise, distributors must continuously adapt their strategies to meet evolving market demands.
Market Opportunities:
The MRO distribution market presents significant growth opportunities driven by technological advancements and the increasing adoption of digital solutions. As more businesses shift towards predictive maintenance and smart systems, the demand for IoT-enabled devices and advanced MRO products is on the rise. Distributors can capitalize on this trend by expanding their offerings to include smart tools and solutions that enhance operational efficiency and reduce downtime. Moreover, the growing use of data analytics and AI-powered platforms in supply chain management offers opportunities to improve inventory tracking, streamline procurement processes, and provide more personalized customer experiences. By leveraging these technologies, distributors can enhance their service offerings, differentiate themselves from competitors, and strengthen customer relationships.
Another promising opportunity lies in the shift towards sustainability and environmentally conscious practices. As industries across the globe prioritize reducing their carbon footprints, there is an increasing demand for energy-efficient equipment, recyclable materials, and eco-friendly MRO solutions. Distributors that align their product portfolios with these sustainability trends can tap into a growing market of businesses seeking to meet regulatory requirements and enhance their environmental stewardship. Additionally, partnerships with manufacturers focusing on green technologies offer a unique opportunity to capture new customers while reinforcing existing client relationships. As sustainability becomes a key focus, MRO distributors that adapt to this demand will be well-positioned to capture a significant share of the market.
Market Segmentation Analysis:
By Product
The MRO distribution market is segmented by product into categories such as fasteners, tools, electrical components, safety equipment, and consumables. Fasteners and tools hold a significant share due to their widespread use across industries. Growing demand for specialized tools and safety equipment, driven by industrial automation and workplace safety standards, is boosting market growth.
By Industry
Key industries driving the MRO market include manufacturing, energy, construction, aerospace, and automotive. Manufacturing remains the dominant sector due to its continuous need for maintenance and operational efficiency. Meanwhile, industries like energy and aerospace are increasingly adopting advanced MRO services to ensure seamless operations and extend equipment life cycles.
By End User
The market serves a wide range of end users, from small enterprises to large corporations. Large enterprises, particularly in manufacturing and energy sectors, drive higher demand for MRO products due to their extensive infrastructure and complex maintenance needs. However, small and mid-sized enterprises are increasingly adopting MRO solutions to enhance efficiency.
Segments:
Based on Product:
- Industrial Supplies
- Sanitation Products
- Fluid Power Components
- Maintenance Chemicals
- Office Supplies
Based on Industry:
- Manufacturing
- Construction
- Oil
- Healthcare
- Transportation
Based on End-User:
- Government
- Hospitals
- Educational Institutions
- Transportation Companies
- Manufacturing Plants
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds a dominant position in the MRO distribution market, accounting for a significant share of the global market. In 2024, the region is expected to capture 35% of the market share, driven by its well-established industrial sectors, particularly in the U.S. and Canada. The manufacturing, automotive, aerospace, and energy industries in these countries consistently demand MRO services to ensure operational efficiency and reduce downtime. Additionally, the rapid adoption of advanced technologies, such as predictive maintenance and IoT-enabled tools, further propels market growth in the region. The strong presence of key MRO distributors and a focus on workplace safety also contribute to North America’s leadership in this market.
Europe
In 2024, Europe is projected to hold 25% of the global MRO distribution market share. The region’s market is primarily driven by its robust manufacturing base, including automotive, aerospace, and heavy machinery sectors. Countries like Germany, France, and the UK play a major role in contributing to the demand for MRO products. The region’s growing emphasis on sustainability and energy efficiency is fostering demand for eco-friendly MRO solutions. Furthermore, the adoption of digital procurement platforms and smart maintenance technologies is accelerating the growth of the MRO distribution market across Europe. Stringent regulatory standards for industrial safety and environmental compliance also promote the usage of MRO products in the region.
Asia-Pacific
The Asia-Pacific region is expected to witness the fastest growth in the MRO distribution market, capturing 30% of the market share in 2024. This rapid growth is fueled by expanding industrialization and infrastructure development in countries like China, India, Japan, and South Korea. The manufacturing and automotive sectors, in particular, are driving high demand for MRO services in the region. Additionally, increasing investments in energy, construction, and transportation projects further boost the market. The shift towards digitization and the adoption of e-commerce platforms are also key factors contributing to the growth of the MRO market in Asia-Pacific. As companies in the region focus on enhancing operational efficiency, the demand for advanced MRO products and services continues to rise.
Latin America
Latin America is anticipated to hold a smaller yet growing share of the MRO distribution market, accounting for 7% of the market in 2024. Countries like Brazil and Mexico are the primary contributors to this growth, driven by the expanding manufacturing and energy sectors. Although the region faces economic and political challenges, investments in industrial infrastructure and a growing focus on maintenance and repair services are expected to support market growth. Moreover, increasing awareness about workplace safety and the gradual adoption of modern technologies in the MRO space are contributing to the region's market development.
Middle East and Africa
The Middle East and Africa region are expected to capture 3% of the global MRO distribution market in 2024. The market here is driven by growing investments in the energy and infrastructure sectors, particularly in countries like Saudi Arabia, the UAE, and South Africa. While the region's industrial base is smaller compared to other regions, the need for efficient maintenance and repair services is growing as these industries expand. Additionally, the adoption of sustainability-focused MRO products and services is gradually gaining traction in the region.
Key Player Analysis:
- Cromwell Group
- Graco, Inc.
- Hillman Group, Inc.
- Rittal GmbH & Co. KG
- Ascendum
- Lawson Products, Inc.
- Lindberg & Lund AS
- Ferguson plc
- ABB Group
- Mento AS
- Festo AG & Co. KG
Competitive Analysis:
The MRO distribution market is highly competitive, with key players such as ABB Group, Ascendum, Cromwell Group, Ferguson plc, Festo AG & Co. KG, Graco, Inc., Hillman Group, Inc., Lawson Products, Inc., Lindberg & Lund AS, Mento AS, and Rittal GmbH & Co. KG leading the landscape. These companies compete primarily through product portfolio expansion, technological advancements, and strategic partnerships. Many of these firms are adopting digital platforms and e-commerce solutions to streamline their distribution channels and improve customer engagement. Additionally, players are focusing on offering value-added services, such as predictive maintenance solutions and tailored customer support, to differentiate themselves in the market. The adoption of eco-friendly products and sustainability initiatives is also gaining momentum, providing a competitive edge for companies aligning with these trends. As the market evolves, the leading players continue to invest in innovation, supply chain optimization, and regional expansions to maintain their market share and strengthen their global presence.
Recent Developments:
- In January 2024, MSC Industrial Supply Co. acquired KAR Industrial Inc., a Canadian metalworking distributor. This acquisition enables MSC to offer KAR’s customers access to its extensive 2.4 million product portfolio and an e-commerce channel through mscdirect.com.
- In March 2024, Troy, the UK’s largest industrial and engineering supplies network, acquired Scott Direct Ltd., expanding its market reach and supporting independent businesses after financial backing from BGF.
- In October 31, 2023, Ferguson completed the acquisition of SecureVision of America, Inc., a Texas-based waterworks metering distributor, enhancing its services across the Dallas, Austin, San Antonio, and Western Texas regions.
- In December 2024, NorthSky Supply Inc. launched an e-commerce platform to meet MRO needs in the U.S., offering a wide range of industrial supplies and repair items to various industries.
- In January 2023, Applied Industrial Technologies introduced its fifth edition Master Product Catalog, featuring over 47,000 MRO products, including fasteners, tools, safety gear, and more.
Market Concentration & Characteristics:
The MRO distribution market is characterized by a moderately fragmented landscape, with a mix of large multinational corporations and smaller regional players. Market concentration is relatively low, as no single company holds a dominant market share, allowing competition to flourish across different regions and sectors. Leading players, such as ABB Group, Ferguson plc, and Cromwell Group, drive the market through extensive product portfolios, technological integration, and global distribution networks. Smaller firms focus on niche markets, offering specialized products and services tailored to local industries. The market is driven by evolving customer demands, with a focus on operational efficiency, cost control, and sustainability. As technological advancements, such as predictive maintenance and digital platforms, continue to reshape the sector, companies are investing in innovation and expanding their capabilities to stay competitive. The market’s dynamic nature encourages continuous growth and diversification across regions.
Report Coverage:
The research report offers an in-depth analysis based on Product, Industry, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The MRO distribution market will witness increased adoption of digital platforms and e-commerce for streamlined procurement and faster delivery.
- Predictive maintenance technologies will play a key role in reducing operational downtime and optimizing maintenance processes.
- Companies will focus on integrating smart solutions and IoT-enabled devices to enhance supply chain efficiency.
- Sustainability will become a critical factor, with businesses adopting eco-friendly and energy-efficient MRO products.
- Regional expansions and strategic partnerships will drive market competition and growth.
- Automation and AI will significantly influence inventory management and operational processes in the MRO sector.
- The demand for specialized MRO services will rise as companies seek to extend the lifespan of industrial equipment.
- Emerging economies will experience rapid growth due to industrialization and infrastructure development.
- Supply chain disruptions may lead to increased nearshoring and local sourcing strategies.
- Technological advancements will continue to differentiate key players, driving innovation and competitive advantages.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the MRO Distribution Market?
What factors are driving the growth of the MRO Distribution Market?
What are the key segments within the MRO Distribution Market?
What are some challenges faced by the MRO Distribution Market?
Who are the major players in the MRO Distribution Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 MRO Distribution Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global MRO Distribution Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 641,620 million → 2032: USD 798,378.33 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 MRO Distribution Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. MRO Distribution Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 MRO Distribution Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 MRO Distribution Market Drivers
- 3.3 MRO Distribution Market Restraints & Challenges
- 3.4 MRO Distribution Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 MRO Distribution Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 MRO Distribution Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, MRO Distribution category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 MRO Distribution Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. MRO Distribution Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the MRO Distribution market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 MRO Distribution Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 MRO Distribution Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 MRO Distribution Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in MRO Distribution (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New MRO Distribution Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global MRO Distribution Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America MRO Distribution Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe MRO Distribution Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific MRO Distribution Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America MRO Distribution Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East MRO Distribution Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa MRO Distribution Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. MRO Distribution Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
