
Market Overview:
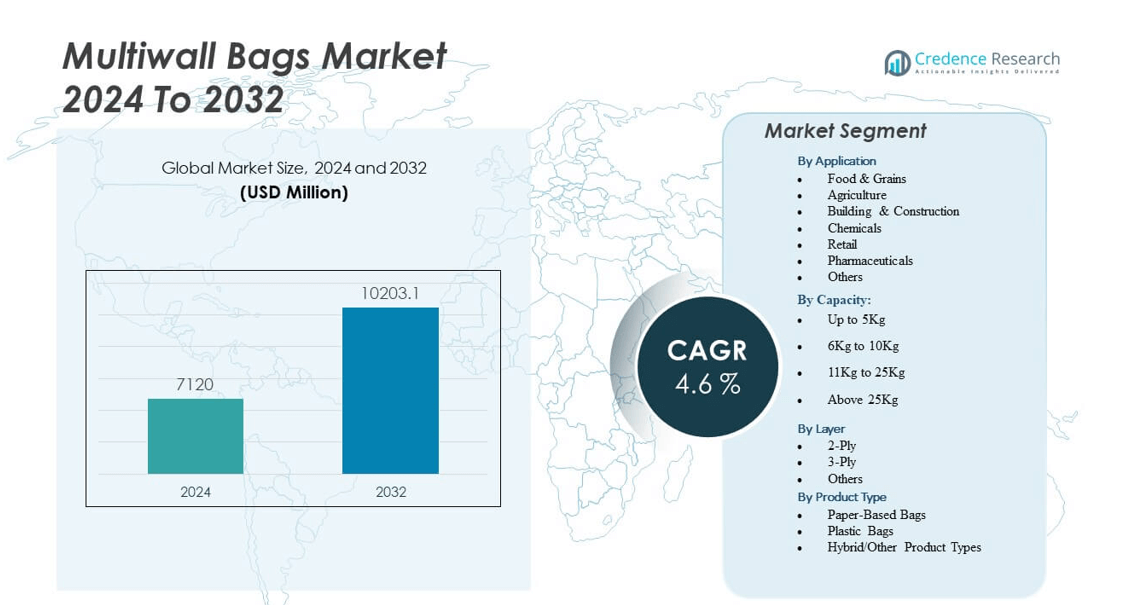
The Multiwall Bags Market is projected to grow from USD 7120 million in 2024 to an estimated USD 10203.1 million by 2032, with a compound annual growth rate (CAGR) of 4.6% from 2024 to 2032.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Multiwall Bags Market Size 2024 | USD 7120 million |
| Multiwall Bags Market, CAGR | 4.6% |
| Multiwall Bags Market Size 2032 | USD 10203.1 million |
Market growth is driven by the rising demand for durable and sustainable packaging solutions across industries such as food, agriculture, chemicals, and construction. Manufacturers are increasingly adopting multiwall bags due to their ability to protect goods from moisture, contamination, and damage during transportation and storage. The shift toward eco-friendly materials and recyclable packaging also strengthens demand, as companies aim to meet stricter environmental regulations and enhance their sustainability commitments.
Regionally, North America and Europe currently lead the market, supported by strong packaging innovation, strict sustainability standards, and established manufacturing industries. Asia Pacific is emerging as the fastest-growing region, driven by rapid industrialization, expanding agriculture, and rising consumption in countries like China and India. Latin America and the Middle East are also showing increasing adoption, supported by economic development and growth in food and chemical exports.
Market Insights:
- The Multiwall Bags Market was valued at USD 7120 million in 2024 and is expected to reach USD 10203.1 million by 2032, growing at a CAGR of 4.6%.
- Rising demand for durable and sustainable packaging drives strong adoption across food, agriculture, construction, and chemicals.
- Regulatory support for eco-friendly materials boosts the preference for paper-based multiwall bags.
- Fluctuating raw material costs and competition from alternative packaging formats create pricing pressures.
- North America holds 28% share, Europe accounts for 26%, and Asia Pacific leads with 32%.
- Emerging regions like Latin America and the Middle East & Africa show steady adoption in agriculture and construction.
- Investments in advanced coatings, lightweight designs, and automation improve efficiency and strengthen competitiveness.
Market Drivers:
Growing Demand from Food and Agricultural Packaging Industries
The Multiwall Bags Market experiences strong growth from rising food and agricultural packaging needs. It offers durability, moisture resistance, and secure storage, which drive adoption in grain, flour, sugar, and seed packaging. The agricultural sector prefers multiwall bags due to their strength and ability to protect products during long-distance transport. Food manufacturers use it to ensure safety, hygiene, and extended shelf life. The rise in population and increasing food exports further elevate demand. Regulatory standards on packaging safety reinforce adoption. It maintains cost-efficiency while meeting bulk packaging requirements across multiple applications. Rising investments in modern farming and storage facilities further stimulate packaging consumption.
- For instance, in June 2025 Mondi launched the re/cycle PaperPlus Bag Advanced, a high-barrier paper bag with a 20 µm film that cuts plastic use by up to 60%, protects humidity-sensitive powdery products, runs on existing filling lines, and is fully recyclable per CEPI and 4Evergreen standards.
Rising Preference for Sustainable and Eco-Friendly Packaging Solutions
Sustainability initiatives act as a major force behind the Multiwall Bags Market. Companies adopt recyclable and biodegradable paper-based bags to comply with environmental policies. Growing consumer awareness about eco-friendly packaging strengthens demand for paper alternatives over plastics. Industrial sectors adopt it to minimize their carbon footprint and strengthen corporate sustainability goals. Governments across regions impose stricter restrictions on single-use plastics, encouraging rapid multiwall bag adoption. Packaging suppliers integrate renewable raw materials to meet regulatory compliance. Innovation in sustainable paper layers enhances bag performance. Stronger emphasis on green packaging boosts long-term market adoption across industries. Expanding circular economy models increase opportunities for multiwall packaging solutions.
- For instance, Smurfit Kappa’s Bag-in-Box packaging is made from more than 75% fully recyclable corrugated cardboard, with the plastic liner weighing only 35 grams for the 3-liter format, resulting in an 8.8 times lower carbon footprint compared to glass bottles and achieving over 85% recycling rates for corrugated components in Europe.
Expansion of Construction and Chemical Sectors Driving Bulk Packaging Demand
The construction and chemical sectors support the Multiwall Bags Market due to their need for bulk material packaging. Cement, gypsum, and fertilizers require durable bags that withstand weight and pressure. Multiwall bags serve industries handling powders, minerals, and specialty chemicals. It ensures resistance to puncture, leakage, and moisture, which is essential for safe transport. Chemical companies rely on it for efficiency in handling hazardous and non-hazardous materials. Strong growth in infrastructure projects elevates cement and chemical demand. Manufacturers develop specialized multiwall bags with coatings for added protection. The adoption ensures stability in supply chains that manage heavy products. Expanding industrial production worldwide reinforces demand for reliable bulk packaging formats.
Rising Global Trade and Supply Chain Expansion Increasing Packaging Needs
Expanding global trade creates strong demand for the Multiwall Bags Market. International shipments of agricultural, food, and chemical products rely on durable packaging formats. Multiwall bags offer flexibility for bulk shipments where handling efficiency is critical. It ensures product protection during extended transit by sea, air, or road. The surge in e-commerce trade increases packaging requirements in food, agriculture, and construction materials. Exporters value it for lightweight yet durable features that lower logistics costs. Large-scale distributors rely on multiwall bags to streamline warehousing and shipping. Growing trade agreements between regions further support steady adoption worldwide. Expanding logistics infrastructure strengthens opportunities for consistent demand growth.
Market Trends:
Integration of Advanced Barrier Technologies to Improve Product Performance
The Multiwall Bags Market benefits from the integration of barrier coatings and films. Manufacturers enhance moisture and oxygen resistance with specialty liners. Industries such as food and chemicals require better protection to maintain product quality. It supports extended shelf life and reduces product loss during storage and transport. Coating innovations improve resistance without reducing recyclability. Companies invest in hybrid bags that combine paper strength with protective layers. Advanced barrier designs increase competitiveness among manufacturers. Rising demand for performance-driven packaging drives steady innovation across suppliers. Continuous research investment ensures the long-term evolution of functional packaging materials.
- For example, in June 2025, Mondi launched the re/cycle PaperPlus Bag Advanced-a high-performance paper bag featuring a 20 µm barrier film. It cuts plastic usage by up to 60% compared to standard 50 µm alternatives, upholds moisture protection for humidity-sensitive goods, and remains fully recyclable.
Digital Printing and Customization Enhancing Branding Opportunities for End-Users
Digital printing transforms the Multiwall Bags Market by enabling customization and branding. Food producers, retailers, and construction suppliers demand visually appealing packaging. It allows direct printing of logos, product details, and promotional elements. The approach enhances shelf visibility and creates brand recognition. Flexible printing technologies enable short-run production for specialized orders. Customization supports regulatory labeling and traceability requirements. Businesses adopt it to differentiate in competitive markets. Printing advancements strengthen value-added opportunities for bag suppliers. Demand for brand-focused packaging continues to rise across consumer-driven industries.
Shift Toward Lightweight and Cost-Efficient Packaging in Bulk Applications
The Multiwall Bags Market observes a strong trend toward lightweight designs. Manufacturers optimize raw material usage while retaining bag strength. Industries prefer lighter packaging to reduce handling and transportation costs. It improves efficiency in global supply chains where bulk goods dominate. Companies experiment with thinner paper layers without sacrificing durability. Lightweight innovations benefit exporters who face cost-sensitive markets. Industrial sectors adopt it to optimize storage space in warehouses and shipping containers. This trend aligns with broader packaging efficiency goals worldwide. Rising demand for transport efficiency reinforces adoption of lightweight solutions.
- For instance, Billerud developed a digital Sack Calculator that enables packaging producers to design lighter industrial sacks by comparing current sack constructions with alternatives using high-strength paper grades; their sack paper with a TEA-index of 3.65 J/g allows a single-ply 25 kg sack to be produced from 110 g/m² paper while still reaching a tensile energy absorption of 400 J/m², reducing material use without compromising performance.
Rising Adoption of Automation and Smart Packaging in Manufacturing Facilities
Automation in production strengthens the Multiwall Bags Market. Automated filling, sealing, and stacking systems reduce operational costs. It ensures precision and efficiency in high-volume packaging lines. Smart packaging technologies integrate RFID tags and QR codes for tracking. Businesses benefit from improved supply chain transparency. Manufacturers deploy automated solutions to handle heavy bags with safety. Digital tools enhance production speed and maintain quality consistency. Automation supports scalability to meet growing industrial packaging demand. Ongoing technological integration improves productivity and global competitiveness.
Market Challenges Analysis:
Volatility in Raw Material Costs and Pressure on Pricing Strategies
The Multiwall Bags Market faces challenges from fluctuating raw material costs. Kraft paper and specialty coatings undergo frequent price variations due to supply disruptions. Manufacturers struggle to balance quality and affordability in such conditions. It leads to pricing pressure across suppliers competing in cost-sensitive markets. Rising costs of sustainable raw materials further complicate profitability. Small-scale producers find it difficult to maintain competitive advantage. Frequent market fluctuations demand agile sourcing strategies. Companies must adapt to maintain stability in a competitive environment. Increasing volatility creates long-term risk for global packaging suppliers.
Competition from Alternative Packaging Formats Affecting Market Expansion
The Multiwall Bags Market encounters rising competition from plastic sacks and flexible intermediate bulk containers. These alternatives often provide cheaper or higher-capacity options. It limits adoption in sectors with tight cost margins. Customers in emerging markets sometimes prefer lower-cost substitutes. Recyclability challenges in multi-layer designs create additional hurdles. Strict recycling regulations affect bag disposal in certain regions. Manufacturers must continue innovating to retain market share. Competitive pressures may slow overall adoption growth without constant product differentiation. Growing adoption of substitutes places added pressure on traditional packaging suppliers.
Market Opportunities:
Expansion of Sustainable Packaging Solutions Supporting Long-Term Growth
Sustainability presents strong opportunities for the Multiwall Bags Market. Paper-based bags gain momentum with global efforts to reduce plastic waste. It positions suppliers as key partners in achieving green goals. Businesses adopt recyclable packaging to meet consumer expectations and government regulations. Emerging markets adopt sustainable solutions faster due to stricter environmental laws. Innovation in biodegradable coatings strengthens eco-friendly adoption. This opportunity allows suppliers to expand across industries seeking greener alternatives. Rising demand from environmentally conscious consumers ensures steady growth. Stronger partnerships between packaging producers and retailers accelerate market adoption.
Growth Potential in Emerging Economies and Untapped Industrial Applications
Emerging economies create high potential for the Multiwall Bags Market. Rapid urbanization increases demand for cement, chemicals, and packaged food. It strengthens market expansion in regions with developing infrastructure. Untapped applications in specialty chemicals and pet food packaging open new revenue streams. Local manufacturers adopt cost-effective multiwall bags to meet industrial demand. Global companies expand their production facilities in growing regions. Partnerships with distributors enhance product reach across rural and urban markets. These opportunities highlight broad future growth prospects for suppliers. Rising investment in modern logistics networks supports further expansion.
Market Segmentation Analysis:
By application, the Multiwall Bags Market shows strong adoption across applications such as food and grains, agriculture, building and construction, chemicals, retail, and pharmaceuticals. Food and grains remain dominant due to high packaging needs for flour, sugar, and cereals. Agriculture benefits from bulk handling of seeds and fertilizers, while building and construction drive usage through cement and gypsum packaging. Chemicals require durable formats to transport powders and specialty products safely. Retail and pharmaceuticals utilize multiwall bags for product protection and reliable storage. Other applications include pet food and specialty industrial goods.
By capacity, the market divides into up to 5Kg, 6Kg to 10Kg, 11Kg to 25Kg, and above 25Kg categories. Smaller bags serve retail and pharmaceutical needs, while mid-range bags support food and agriculture. Heavy-duty bags above 25Kg dominate in cement, chemicals, and construction. This segmentation reflects the diverse range of industries relying on weight-specific solutions.
- For instance, LC Packaging produces tailor-made multiwall paper bags with capacities up to 25 kg, supplying the construction and agricultural sectors with safe, durable packaging solutions for commodities such as cement, fertilizers, and grains.
By layer, 2-ply and 3-ply formats remain preferred, offering strength and durability. Two-ply bags suit lighter applications, while three-ply options dominate in chemicals and construction. Other configurations provide flexibility for niche industries.
- For instance, SHU Packaging manufactures multiwall paper bags in 2-ply and 3-ply formats, with the 3-ply heavy-duty kraft construction offering high elasticity and tear resistance, making it suitable for industries such as fertilizers, chemicals, minerals, and construction.
By product type, paper-based bags lead due to sustainability and recyclability advantages. Plastic bags retain demand in cost-sensitive sectors, and hybrid types gain traction where extra barrier protection is required. The market demonstrates balance between environmental focus and performance-driven packaging.
Segmentation:
By Application
- Food & Grains
- Agriculture
- Building & Construction
- Chemicals
- Retail
- Pharmaceuticals
- Others
By Capacity:
- Up to 5Kg
- 6Kg to 10Kg
- 11Kg to 25Kg
- Above 25Kg
By Layer
- 2-Ply
- 3-Ply
- Others
By Product Type
- Paper-Based Bags
- Plastic Bags
- Hybrid/Other Product Types
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis:
North America holds a market share of 28% in the Multiwall Bags Market, driven by established food, agriculture, and construction industries. Strong regulatory frameworks on packaging safety and sustainability standards support adoption across multiple sectors. The United States leads the region with robust demand from packaged food and building materials. Canada and Mexico contribute steadily, supported by agricultural exports and chemical production. It benefits from advanced manufacturing capabilities and consistent investment in sustainable packaging formats. Regional players focus on recyclable paper-based multiwall bags to align with eco-friendly policies.
Europe accounts for 26% of the market share, supported by strict environmental regulations and a mature packaging sector. The region emphasizes recyclable and biodegradable materials to meet EU sustainability goals. Germany, France, and the UK dominate with strong construction, food, and chemical industries. Growth in Eastern Europe adds momentum through rising agricultural and retail sectors. It experiences strong innovation in hybrid and barrier-coated multiwall bags to meet industrial needs. The focus on circular economy policies drives manufacturers toward advanced eco-friendly solutions across the region.
Asia Pacific leads with a market share of 32%, fueled by rapid industrialization and growing consumption across emerging economies. China and India dominate due to strong demand in agriculture, construction, and packaged food sectors. Japan and South Korea contribute with advanced manufacturing and chemical industries. It benefits from large-scale production, cost-efficient labor, and rising exports of agricultural commodities. Expansion in retail and pharmaceuticals further strengthens regional adoption. Latin America holds 8%, while the Middle East and Africa collectively represent 6%, supported by agriculture, chemicals, and construction projects.
Key Player Analysis:
- Mondi Group
- Smurfit Kappa Group
- WestRock Company
- Sonoco Products Company
- Berry Global Inc.
- Hood Packaging Corporation
- El Dorado Packaging, Inc.
- LC Packaging
- NNZ Group
- United Bags, Inc.
- Langston Companies, Inc.
- Segezha Group
Competitive Analysis:
The Multiwall Bags Market is highly competitive with global and regional players focusing on product quality, sustainability, and customization. Leading companies such as Mondi Group, Smurfit Kappa, WestRock, and Berry Global dominate with strong global networks and diversified portfolios. It demonstrates competitiveness through innovation in paper-based solutions and eco-friendly alternatives. Mid-sized firms like Hood Packaging, LC Packaging, and El Dorado Packaging strengthen regional supply with tailored solutions for food, agriculture, and construction sectors. Companies invest in advanced printing, barrier coatings, and lightweight designs to enhance product performance and meet consumer demands. Sustainability commitments drive partnerships with industries seeking recyclable and biodegradable packaging. The presence of multiple small and regional players increases pricing pressure, forcing innovation and operational efficiency among larger firms. Competitive intensity is expected to remain high as demand grows in both developed and emerging markets.
Recent Developments:
- In June 2025, Mondi Group launched its FunctionalBarrier Paper Ultimate, responding to rising demand for sustainable, high-barrier paper-based packaging options in the multiwall bags market.
- In April 2025, Mondi Group completed the acquisition of Schumacher Packaging’s Western Europe operations, consolidating its market position and expanding its product portfolio-particularly with corrugated solutions-within the multiwall bags segment.
- In September 2024, ProAmpac announced the launch of QUADFLEX® Recyclable LFQ, its latest innovation for the multiwall bags market. This product offers brands a fully recyclable laminate solution, supporting increasing demand for environmentally friendly packaging while maintaining the strength and moisture barrier required for food, agriculture, and industrial applications.
- In May 2023, GELPAC, a North American packaging solutions provider, strategically acquired Standard Multiwall Bag Mfg. Co., a specialty producer of food-grade and industrial multiwall and woven poly laminated bags.
Report Coverage:
The research report offers an in-depth analysis based on Application, Capacity, Layer and Product Type. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Multiwall Bags Market is expected to experience steady demand from food and grain packaging driven by population growth and rising consumption.
- Agricultural expansion will support adoption as multiwall bags remain reliable for seed, fertilizer, and crop distribution.
- Construction activity worldwide will sustain usage in cement, gypsum, and other bulk material applications.
- Chemical industries will strengthen demand through their reliance on durable, moisture-resistant packaging solutions.
- Sustainability initiatives will increase the share of paper-based multiwall bags aligned with eco-friendly policies.
- Investments in advanced coatings and hybrid formats will enhance product strength and barrier performance.
- Retail and pharmaceutical sectors will expand usage through lightweight, customized, and safe packaging solutions.
- Emerging markets will accelerate growth through industrialization, infrastructure development, and rising export activities.
- Automation in bag manufacturing and smart packaging integration will improve efficiency and supply chain visibility.
- Competitive strategies will emphasize product innovation, branding, and recyclability to maintain market positioning.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Demand from Food and Agricultural Packaging Industries
The need for durable, moisture-resistant, and secure packaging in food and agriculture is driving multiwall bag adoption, especially for grains, flour, sugar, and seeds. Population growth and increased food exports further elevate demand, while regulatory standards on packaging safety reinforce the use of multiwall bags.
Rising Preference for Sustainable and Eco-Friendly Packaging Solutions
Stricter environmental regulations and consumer awareness are pushing companies to adopt recyclable and biodegradable paper-based multiwall bags. This shift is supported by government policies targeting single-use plastics and by corporate sustainability commitments, boosting demand for eco-friendly packaging.
Expansion of Construction and Chemical Sectors
The construction and chemical industries require robust, bulk packaging for materials like cement, gypsum, fertilizers, and specialty chemicals. Multiwall bags offer the necessary strength and protection, supporting safe transport and storage, and are increasingly adopted as infrastructure and industrial production expand globally.
Rising Global Trade and Supply Chain Expansion
International shipments of agricultural, food, and chemical products rely on multiwall bags for their durability and efficiency in bulk handling. The growth of global trade, e-commerce, and improved logistics infrastructure is increasing the need for reliable packaging solutions like multiwall bags.
Integration of Advanced Barrier Technologies and Automation
Innovations in barrier coatings, lightweight designs, and automated manufacturing processes are enhancing the performance and cost-efficiency of multiwall bags. These advancements improve product protection, extend shelf life, and support high-volume, efficient production, making multiwall bags more attractive across industries.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Multiwall Bags Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Multiwall Bags Market projected to grow between 2024 and 2032?
What are the primary factors fueling the growth of the Multiwall Bags Market?
Who are the leading companies in the Multiwall Bags Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Layer
- 1.2.1 2-Ply
- 1.2.2 3-Ply
- 1.2.3 Others
- 1.3 By Capacity
- 1.3.1 Up to 5Kg
- 1.3.2 6Kg to 10Kg
- 1.3.3 11Kg to 25Kg
- 1.3.4 Above 25Kg
- 1.4 By Application
- 1.4.1 Food & Grains
- 1.4.2 Agriculture
- 1.4.3 Building & Construction
- 1.4.4 Chemicals
- 1.4.5 Retail
- 1.4.6 Pharmaceuticals
- 1.4.7 Others
- 1.5 By Product Type
- 1.5.1 Paper-Based Bags
- 1.5.2 Plastic Bags
- 1.5.3 Hybrid/Other Product Types
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 7120 million → 2032: USD 10203.1 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Multiwall Bags Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Multiwall Bags Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Multiwall Bags Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Multiwall Bags Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Multiwall Bags Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Multiwall Bags Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Multiwall Bags Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Multiwall Bags Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 7120 million → 2032: USD 10203.1 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Multiwall Bags Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Layer - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 2-Ply
- 12.3.7.2 3-Ply
- 12.3.7.3 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Capacity - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Up to 5Kg
- 12.4.7.2 6Kg to 10Kg
- 12.4.7.3 11Kg to 25Kg
- 12.4.7.4 Above 25Kg
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Food & Grains
- 12.5.7.2 Agriculture
- 12.5.7.3 Building & Construction
- 12.5.7.4 Chemicals
- 12.5.7.5 Retail
- 12.5.7.6 Pharmaceuticals
- 12.5.7.7 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Product Type - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Paper-Based Bags
- 12.6.7.2 Plastic Bags
- 12.6.7.3 Hybrid/Other Product Types
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Multiwall Bags End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Multiwall Bags Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Multiwall Bags Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Multiwall Bags Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Mondi Group
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Smurfit Kappa Group
- 18.4 WestRock Company
- 18.5 Sonoco Products Company
- 18.6 Berry Global Inc.
- 18.7 Hood Packaging Corporation
- 18.8 El Dorado Packaging, Inc.
- 18.9 LC Packaging
- 18.10 NNZ Group
- 18.11 United Bags, Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

