
Market Overview:
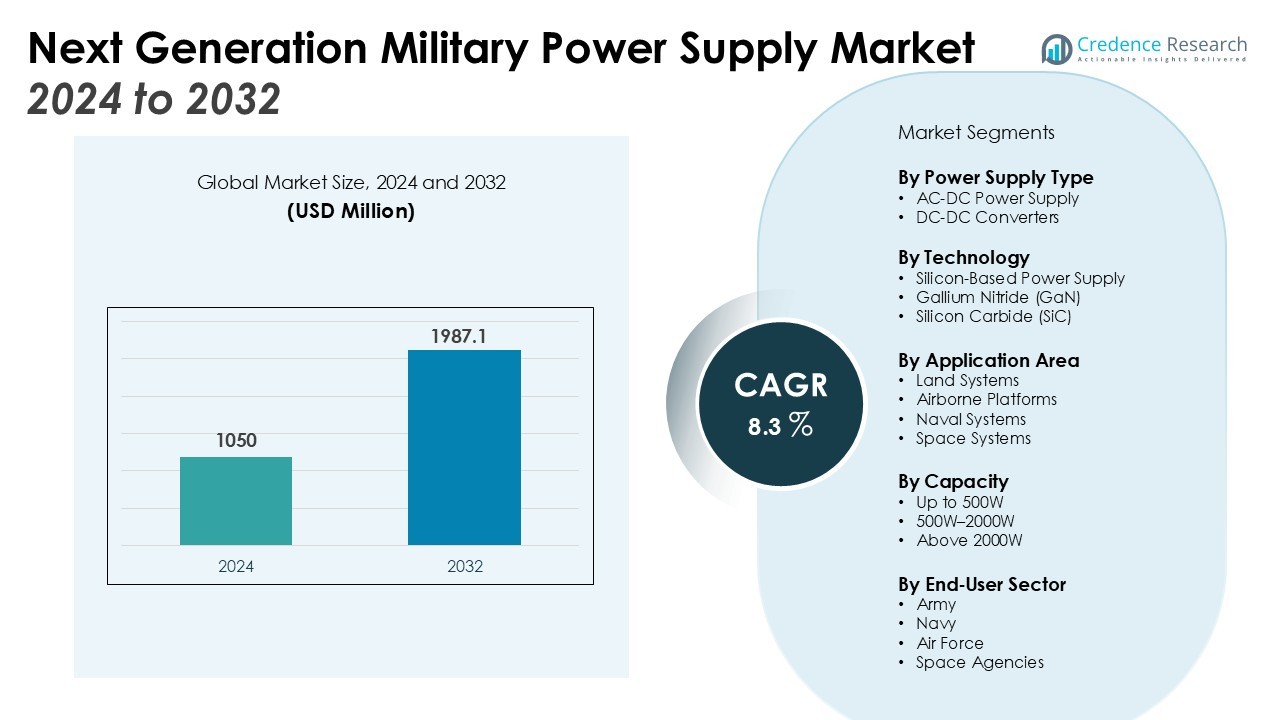
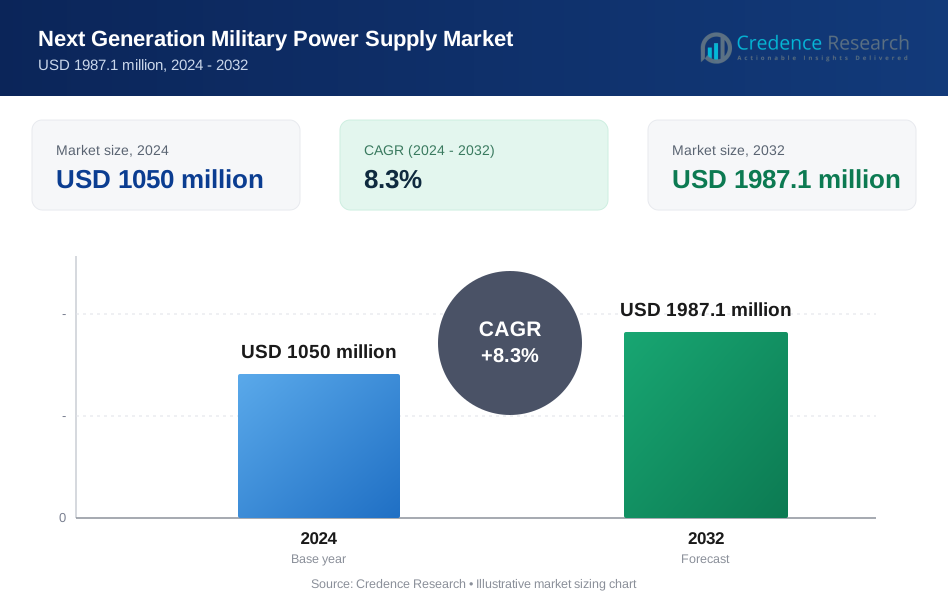
The Next Generation Military Power Supply Market size was valued at USD 1050 million in 2024 and is anticipated to reach USD 1987.1 million by 2032, at a CAGR of 8.3% during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Next Generation Military Power Supply Market Size 2024 | USD 1050 Million |
| Next Generation Military Power Supply Market, CAGR | 8.3% |
| Next Generation Military Power Supply Market Size 2032 | USD 1987.1 Million |
Market growth is driven by the rising demand for compact, rugged, and high-efficiency power supplies that can withstand harsh environments. Defense forces are increasingly focused on solutions that support advanced electronics, unmanned vehicles, radar, and communication systems, which require stable and secure power delivery. Continuous investment in next-generation technologies, such as gallium nitride (GaN) and silicon carbide (SiC) semiconductors, is further enhancing efficiency, reducing weight, and extending mission endurance.
Regionally, North America holds the largest share due to extensive defense spending by the U.S. and ongoing modernization programs. Europe follows closely, supported by NATO-led initiatives and defense upgrades across Germany, the U.K., and France. Asia Pacific is the fastest-growing region, fueled by rising military budgets in China, India, and Japan, alongside regional security concerns. The Middle East is also emerging as a key market, driven by rising defense procurement and modernization initiatives across GCC nations.
Market Insights:
- The Next Generation Military Power Supply Market was valued at USD 1050 million and is projected to reach USD 1987.1 million at a CAGR of 8.3%.
- Market expansion is supported by rising demand for compact, rugged, and high-efficiency power supplies for harsh defense environments.
- Growth is fueled by advanced applications in unmanned platforms, radar, electronic warfare, and secure communication systems requiring stable power delivery.
- Continuous adoption of GaN and SiC semiconductors is improving efficiency, reducing weight, and enabling high-power density solutions.
- North America holds 42% share, driven by high defense spending, modernization programs, and a mature defense ecosystem.
- Europe captures 28% share, supported by NATO-led initiatives, defense upgrades, and increasing focus on energy-efficient power systems.
- Asia Pacific accounts for 21% share, emerging as the fastest-growing region due to rising military budgets and indigenous defense manufacturing.
Market Drivers:
Rising Demand for Advanced and Ruggedized Power Systems
The Next Generation Military Power Supply Market is expanding due to the rising need for compact, durable, and energy-efficient systems. Modern defense operations require power supplies that can withstand harsh environments such as extreme temperatures, shock, and vibration. These systems support critical functions in land, air, naval, and space missions where reliability cannot be compromised. Growing military reliance on high-performance electronics strengthens the demand for next-generation power supply solutions.
- For instance, Vicor’s DCM non-isolated regulated DC-DC converter modules support up to 2000 Watts of power with a 6-fold reduction in size compared to conventional converters, offering exceptional power density for military applications.
Increasing Deployment of Unmanned and Autonomous Defense Platforms
The rapid adoption of unmanned aerial vehicles (UAVs), ground systems, and autonomous naval platforms is driving market growth. These systems depend heavily on stable and efficient power delivery to maintain communication, navigation, and surveillance functions. The market benefits from rising investments in autonomous technologies that demand compact and lightweight power supplies. It is helping defense organizations enhance operational efficiency while extending mission capabilities.
Growing Emphasis on Electronic Warfare and Advanced Communication Systems
Electronic warfare, radar, and communication systems require uninterrupted and secure power to function effectively in combat scenarios. The Next Generation Military Power Supply Market is supported by increasing investments in advanced defense electronics designed for network-centric warfare. Rising threats in cyber and electronic domains push governments to prioritize resilient power infrastructure. It ensures seamless integration of advanced technologies into existing defense networks.
- For instance, Lockheed Martin's AN/ALQ-217 Electronic Support Measures system provides full 360° radio frequency acquisition coverage across three bands with four antennas and four active front ends, ensuring powerful performance in dense environments and fast emitter identification.
Technological Advancements in Semiconductor and Power Conversion Materials
Innovations in gallium nitride (GaN) and silicon carbide (SiC) semiconductors are transforming the efficiency of military power supplies. These materials enable higher power density, reduced system weight, and improved thermal management. The market gains momentum as defense contractors adopt these technologies to meet modern combat requirements. It reflects a broader industry shift toward advanced materials that enhance performance while reducing maintenance costs.
Market Trends:
Integration of Smart Power Management and Modular Designs
The Next Generation Military Power Supply Market is witnessing a strong shift toward modular and intelligent power solutions. Defense organizations are adopting power systems with built-in diagnostics, predictive maintenance, and remote monitoring features to improve mission reliability. Modular designs allow easy scalability and faster deployment across diverse platforms, including aircraft, naval vessels, and ground vehicles. The demand for flexible architectures that reduce downtime and enhance adaptability is rising. It is also enabling militaries to customize power configurations based on specific mission requirements. Growing interest in digital control systems further highlights the importance of smart power management in improving efficiency and operational readiness.
- For instance, Leonardo DRS has fielded over 3,000 units of its Digital Vehicle Distribution Box (DVDB) within the Bradley Fighting Vehicle platform, which includes embedded diagnostics to monitor power lines and sensors, significantly enhancing operational reliability.
Adoption of Renewable and Hybrid Energy Solutions in Defense Applications
Global defense agencies are increasingly focusing on renewable and hybrid power supply technologies to reduce fuel dependency and enhance sustainability. The Next Generation Military Power Supply Market is benefiting from research efforts aimed at integrating solar, fuel cell, and hybrid energy systems into field operations. Militaries are deploying mobile microgrids and energy storage systems to power advanced electronics, radar, and command centers in remote or contested areas. It reflects a growing commitment to improving energy security while minimizing logistical risks related to fuel transport. The market is also observing a shift toward hybrid architectures that combine conventional and renewable sources to deliver reliable, uninterrupted power. This trend is strengthening the industry’s role in supporting greener and more resilient defense strategies.
- For instance, Schweitzer Engineering Laboratories (SEL) offers tactical mobile microgrids with the powerMAX control system that enables seamless parallel operation of multiple diesel generators, enhancing power resiliency and operational efficiency for forward operating bases.
Market Challenges Analysis:
High Development Costs and Stringent Compliance Requirements
The Next Generation Military Power Supply Market faces challenges linked to high development costs and strict regulatory compliance. Advanced designs using GaN and SiC semiconductors require significant investment in R&D and specialized manufacturing. Defense-grade power supplies must also meet rigorous standards for safety, reliability, and electromagnetic compatibility. These requirements increase costs and lengthen development timelines, creating barriers for smaller suppliers. It restricts broader adoption and slows product commercialization in certain regions. Rising procurement scrutiny further adds complexity to meeting diverse defense specifications.
Supply Chain Vulnerabilities and Technological Integration Issues
The market also struggles with supply chain disruptions and difficulties in integrating new technologies into legacy defense systems. Dependence on specialized raw materials and semiconductor components exposes the industry to delays and cost fluctuations. It complicates production planning and impacts timely delivery of critical equipment. Integrating modern power supplies with existing platforms is technically demanding and resource-intensive. The challenge grows as defense forces push for interoperability across land, sea, air, and space domains. Limited availability of skilled personnel in advanced power electronics further intensifies these constraints.
Market Opportunities:
Expanding Demand for Power Solutions in Emerging Defense Technologies
The Next Generation Military Power Supply Market holds strong opportunities with the rapid adoption of unmanned systems, directed-energy weapons, and advanced radar platforms. These technologies require compact, lightweight, and efficient power supplies capable of operating in demanding conditions. Governments are increasing defense budgets to support modernization programs that prioritize advanced electronic warfare and communication systems. It creates a favorable environment for manufacturers offering innovative and high-performance power solutions. Rising investments in hybrid energy systems and field-deployable microgrids also expand market potential across diverse missions. The growing need for reliable and flexible power delivery strengthens opportunities for both established and emerging suppliers.
Strategic Focus on Renewable and Energy-Efficient Defense Operations
The transition toward energy efficiency and renewable integration presents another avenue for market growth. The Next Generation Military Power Supply Market is benefiting from initiatives aimed at reducing fuel dependency and improving sustainability in field operations. Defense agencies are exploring hybrid systems combining traditional, renewable, and storage-based power supplies to enhance operational endurance. It enables militaries to lower logistical risks while ensuring uninterrupted mission capability. Growing emphasis on digital power management and smart control systems provides new prospects for technological innovation. The trend aligns with global defense strategies focused on greener, resilient, and future-ready military infrastructure.
Market Segmentation Analysis:
By Power Supply Type
The Next Generation Military Power Supply Market is segmented by power supply type, reflecting the diverse needs of modern defense systems. AC-DC power supplies dominate due to their extensive use in ground vehicles, naval systems, and communication platforms. DC-DC converters are witnessing strong demand for integration into advanced electronics, unmanned systems, and portable field equipment. It highlights the growing requirement for compact, lightweight, and high-efficiency solutions that can adapt to various mission conditions.
- For instance, Advanced Energy's Evergreen™ Vento series offers a power density of 38 W/in³, delivering more power in less space for rugged military applications.
By Technology
By technology, the market is advancing through the adoption of gallium nitride (GaN) and silicon carbide (SiC) semiconductors. These materials deliver higher efficiency, improved power density, and better thermal management compared to conventional silicon-based systems. Their use reduces system weight while enhancing durability and performance in harsh environments. It strengthens the ability of defense organizations to deploy next-generation platforms with longer operational lifecycles.
- For instance, Qorvo's GaN power amplifiers used in military radar systems achieve power outputs up to 150 watts per device, supporting advanced radar performance in extreme conditions.
By Application Area
By application area, the market serves land, air, naval, and space defense operations. Land systems hold a major share, driven by the demand for secure and reliable power in armored vehicles and tactical equipment. Airborne platforms, including fighter jets and UAVs, require lightweight, high-density solutions to maximize mission range. Naval and space segments are also expanding, driven by advanced radar, communication, and satellite systems that depend on uninterrupted and efficient power delivery.
Segmentations:
By Power Supply Type
- AC-DC Power Supply
- DC-DC Converters
By Technology
- Silicon-Based Power Supply
- Gallium Nitride (GaN)
- Silicon Carbide (SiC)
By Application Area
- Land Systems
- Airborne Platforms
- Naval Systems
- Space Systems
By Capacity
- Up to 500W
- 500W–2000W
- Above 2000W
By End-User Sector
- Army
- Navy
- Air Force
- Space Agencies
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis:
Strong Position of North America Driven by Defense Modernization
North America accounted for 42% share of the Next Generation Military Power Supply Market. The region’s growth is supported by the U.S. Department of Defense’s high military spending and continuous modernization initiatives. The focus on advanced combat systems, electronic warfare, and unmanned platforms drives strong demand for rugged and efficient power supplies. Major defense contractors and technology providers contribute to innovation through significant investments in research and development. It ensures rapid adoption of GaN and SiC-based systems that improve energy efficiency and performance. The presence of a mature defense manufacturing ecosystem further strengthens the region’s leadership.
Europe’s Steady Growth Through NATO Initiatives and Defense Upgrades
Europe captured 28% share of the global market. The region benefits from NATO-led programs and national defense upgrades, especially in Germany, France, and the U.K. Heavy investments are directed toward next-generation power systems for aircraft, naval fleets, and ground-based platforms. The emphasis on secure communication, radar modernization, and electronic warfare enhances demand for reliable power delivery solutions. It also gains from collaborative projects between governments and defense technology firms. Europe’s defense industry focus on sustainability supports wider integration of energy-efficient systems.
Asia Pacific’s Rapid Expansion Supported by Rising Defense Budgets
Asia Pacific accounted for 21% share of the Next Generation Military Power Supply Market. The region’s growth is supported by rising defense budgets in China, India, Japan, and South Korea. Increasing investments in indigenous defense manufacturing and platform modernization drive regional expansion. Security concerns and border tensions push governments to prioritize advanced power technologies for mission readiness. It is creating strong opportunities for both domestic and international suppliers to expand. Growing adoption of hybrid and renewable-based power solutions reflects the region’s commitment to long-term energy security and operational resilience.
Key Player Analysis:
- XP Power
- Advanced Conversion Technology
- Eaton Corporation
- Aegis Power System
- TDK-Lambda Americas
- Abbott Technologies
- AGMA Power Systems
- Mitsubishi Electric
- Energy Technologies
- Synqor
- Prime Power
- Powerbox Inteational
- Milpower Source
- Astrodyne TDI
Competitive Analysis:
The Next Generation Military Power Supply Market is highly competitive, driven by continuous innovation and rising defense investments. Leading companies focus on developing rugged, compact, and energy-efficient systems tailored to advanced defense applications. It emphasizes high reliability, extended durability, and compliance with strict military standards. Key players are expanding their portfolios with GaN and SiC-based solutions that offer higher power density, reduced weight, and improved thermal management. Strategic partnerships with defense agencies and long-term supply contracts strengthen their global presence. The market also reflects competition among established defense contractors and specialized electronics firms aiming to secure large-scale modernization projects. It highlights strong investment in R&D, product differentiation, and regional expansion to meet the evolving requirements of land, air, naval, and space defense operations.
Recent Developments:
- In June 2025, Advanced Conversion and W. L. Gore & Associates announced the start of volume production for high-temperature film capacitors, following a partnership agreement made in June 2024.
- In May 2025, Eaton launched the 9PX Gen2, a new uninterruptible power supply (UPS) system designed for data centers.
- In January 2025, Synqor, Inc. announced the release of its new military-grade, isolated, 3-phase power factor correction module, the MPFIC-115-3PD-28R-FG.
Report Coverage:
The research report offers an in-depth analysis based on Power Supply Type, Technology, Application Area, Capacity, End-User Sector and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising adoption of compact and rugged power supplies will strengthen operational readiness across diverse defense platforms.
- Growing reliance on unmanned aerial, ground, and naval systems will expand demand for lightweight and efficient solutions.
- Advancements in GaN and SiC semiconductors will enhance power density, reduce weight, and improve durability in harsh environments.
- Expansion of electronic warfare and secure communication systems will create continuous demand for resilient power delivery.
- Integration of smart monitoring and predictive maintenance features will improve efficiency and reduce downtime.
- Hybrid and renewable-based power systems will gain traction as defense agencies pursue sustainability and energy security.
- Increasing defense budgets in emerging economies will provide growth opportunities for global and regional suppliers.
- Collaboration between defense contractors and technology firms will accelerate innovation and deployment of next-generation systems.
- Interoperability requirements across land, air, naval, and space operations will drive development of standardized solutions.
- Strategic investments in R&D and supply chain resilience will shape long-term competitiveness in the market.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Demand for Compact, Rugged, and High-Efficiency Power Supplies
Modern military platforms require power supplies that are compact, lightweight, and capable of withstanding harsh environments, such as extreme temperatures and vibrations. This need is driving the adoption of next-generation solutions that enhance operational reliability and mission endurance.
Growth in Unmanned and Autonomous Defense Platforms
The increasing deployment of UAVs, unmanned ground vehicles, and autonomous naval systems necessitates stable, efficient, and lightweight power delivery. This trend is expanding the market for advanced power supplies tailored to these platforms.
Advancements in GaN and SiC Semiconductor Technologies
Continuous innovation in gallium nitride and silicon carbide semiconductors is enabling higher power density, improved efficiency, and reduced weight in military power supplies. These advancements are critical for supporting advanced electronics and extending mission capabilities.
Expansion of Electronic Warfare and Secure Communication Systems
The proliferation of electronic warfare, radar, and secure communication systems in defense operations requires uninterrupted and resilient power delivery. Investments in these advanced systems are fueling demand for next-generation military power supplies.
Shift Toward Renewable and Hybrid Energy Solutions
Defense agencies are increasingly integrating renewable and hybrid power systems to reduce fuel dependency and enhance sustainability in field operations. This shift is creating new opportunities for innovative power supply solutions that combine conventional and renewable energy sources.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Next Generation Military Power Supply, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Next Generation Military Power Supply market projected to grow between 2024 and 2032?
Which Next Generation Military Power Supply market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Next Generation Military Power Supply market?
Which region commanded the largest share of the Next Generation Military Power Supply market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Capacity
- 1.2.1 Up to 500W
- 1.2.2 500W–2000W
- 1.2.3 Above 2000W
- 1.3 By Technology
- 1.3.1 Silicon-Based Power Supply
- 1.3.2 Gallium Nitride (GaN)
- 1.3.3 Silicon Carbide (SiC)
- 1.4 By Application Area
- 1.4.1 Land Systems
- 1.4.2 Airborne Platforms
- 1.4.3 Naval Systems
- 1.4.4 Space Systems
- 1.5 By Power Supply Type
- 1.5.1 AC-DC Power Supply
- 1.5.2 DC-DC Converters
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1050 million → 2032: USD 1987.1 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Next Generation Military Power Supply Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Next Generation Military Power Supply Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Next Generation Military Power Supply Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Next Generation Military Power Supply Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Next Generation Military Power Supply Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Next Generation Military Power Supply Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Next Generation Military Power Supply Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Next Generation Military Power Supply Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1050 million → 2032: USD 1987.1 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Next Generation Military Power Supply Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Capacity - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Up to 500W
- 12.3.7.2 500W–2000W
- 12.3.7.3 Above 2000W
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Silicon-Based Power Supply
- 12.4.7.2 Gallium Nitride (GaN)
- 12.4.7.3 Silicon Carbide (SiC)
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application Area - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Land Systems
- 12.5.7.2 Airborne Platforms
- 12.5.7.3 Naval Systems
- 12.5.7.4 Space Systems
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Power Supply Type - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 AC-DC Power Supply
- 12.6.7.2 DC-DC Converters
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Next Generation Military Power Supply End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Next Generation Military Power Supply Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Next Generation Military Power Supply Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Next Generation Military Power Supply Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 XP Power
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Advanced Conversion Technology
- 18.4 Eaton Corporation
- 18.5 Aegis Power Systems
- 18.6 TDK-Lambda Americas
- 18.7 Abbott Technologies
- 18.8 Mitsubishi Electric
- 18.9 Synqor
- 18.10 Astrodyne TDI
- 18.11 Milpower Source
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

