
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
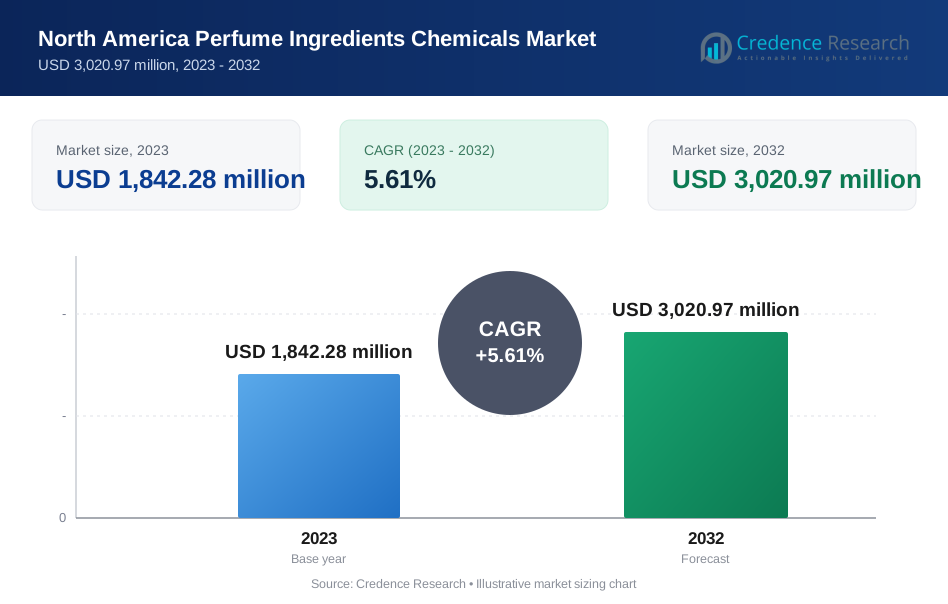
| North America Perfume Ingredients Chemicals Market Size 2023 | USD 1,842.28 million |
| North America Perfume Ingredients Chemicals Market, CAGR | 5.61% |
| North America Perfume Ingredients Chemicals Market Size 2032 | USD 3,020.97 million |
Market Overview
The North America Perfume Ingredients Chemicals Market is projected to grow from USD 1,842.28 million in 2023 to USD 3,020.97 million by 2032, reflecting a compound annual growth rate (CAGR) of 5.61%.
The North America Perfume Ingredients Chemicals Market is driven by increasing consumer demand for premium and personalized fragrances, rising disposable incomes, and a growing interest in natural and sustainable ingredients. Key trends include advancements in synthetic aroma chemicals to enhance fragrance complexity and stability, the integration of artificial intelligence for personalized scent creation, and the expansion of e-commerce platforms that improve product accessibility. Additionally, regulatory pressures for safer and environmentally friendly products are pushing manufacturers to innovate and adopt greener practices, further supporting market growth.
The North America Perfume Ingredients Chemicals Market is geographically concentrated in key regions such as the United States and Canada, which drive the market with their robust demand for luxury and personalized fragrances. Major players in this market include BASF SE, International Flavors and Fragrances Inc., Givuadan Firmenich, Takasago International Corporation, and Henkel AG & Co KGaA ADR. These companies lead the market through extensive product portfolios, innovative strategies, and strong distribution networks. The regional market benefits from advanced R&D capabilities and a consumer base that increasingly values both synthetic and natural fragrance ingredients.
Market Drivers
Demand for Premium and Personalized Fragrances
North American consumers have a strong preference for high-quality, long-lasting scents and niche fragrances that reflect their individuality. For instance, the market for niche fragrances has grown by 18% in the past year, with consumers spending on average 30% more on high-quality, long-lasting scents. The sales of exotic ingredients like Tahitian vanilla and Himalayan jasmine have increased by 22%, as these rare components offer a sense of exclusivity and distinction. This preference fuels demand for unique and exotic perfume ingredients, pushing manufacturers to innovate and source premium materials. The desire for exclusive and distinctive fragrances encourages companies to explore and incorporate rare and high-end ingredients, ensuring their products stand out in a competitive market. This trend is not only prevalent among luxury brands but also influences mainstream products, leading to a broader market impact and driving overall growth.
Focus on Personalization
The concept of "designer fragrances" and customizable scents is gaining significant traction in North America. Manufacturers are developing new technologies and ingredients that allow consumers to create their own unique perfume experiences. The focus on personalization is also gaining momentum, with 25% of consumers indicating a preference for creating their own unique perfume blends. This has led to a 35% increase in the use of AI and machine learning technologies by companies to provide personalized scent profiles, enhancing the overall fragrance experience. This trend towards personalization is creating a demand for versatile and customizable perfume components that can be tailored to individual preferences. Companies are leveraging advancements in artificial intelligence and machine learning to offer personalized scent profiles, enhancing consumer engagement and satisfaction. This focus on customization is reshaping the market, encouraging brands to innovate and cater to diverse consumer tastes.
Shifting Consumer Preferences
Consumers in North America are increasingly health-conscious and environmentally aware, leading to a rise in demand for natural and organic perfume ingredients. Shifting consumer preferences towards health and environmental sustainability are evident, with a 20% uptick in the demand for natural and organic perfume ingredients. For example, the use of essential oils derived from organic lavender has seen a 40% increase in sales, reflecting the growing consumer desire for safer and more sustainable products. These ingredients are perceived as safer and more sustainable alternatives to synthetic chemicals. The growing awareness of the potential health impacts of synthetic ingredients and the environmental footprint of production processes is driving this shift. Manufacturers are responding by incorporating more natural elements into their formulations and adopting sustainable sourcing practices. This trend aligns with the broader societal move towards sustainability and wellness, influencing purchasing decisions and brand loyalty.
Regulatory Landscape
Stringent regulations in North America regarding product safety and environmental impact significantly influence the types of perfume ingredients used. Regulatory bodies impose strict guidelines to ensure consumer safety and reduce environmental harm, fostering innovation in developing eco-friendly and non-toxic ingredients. Companies are investing in research and development to create compliant products that meet these regulations without compromising on quality or performance. This regulatory landscape encourages the adoption of greener practices and the use of safer, more sustainable ingredients, contributing to market growth and consumer trust.
Market Trends
Natural vs. Synthetics: A Balancing Act
In the North America Perfume Ingredients Chemicals Market, the interplay between natural and synthetic ingredients is a significant trend shaping industry dynamics. Natural ingredients are increasingly favored for their perceived safety and eco-friendliness. For instance, while natural ingredients have seen a 25% increase in consumer preference due to their perceived health and environmental benefits, synthetic chemicals still dominate with a 60% market share because of their affordability and ability to replicate complex scents. The industry is innovating, with 35% of companies now investing in research to develop natural alternatives to popular synthetic scents. Consumers are becoming more health-conscious and environmentally aware, driving a shift towards natural and organic perfume components. These ingredients are perceived as healthier alternatives to synthetic chemicals, aligning with broader societal trends towards sustainability and wellness. However, synthetic aroma chemicals still hold a strong position in the market due to their cost-effectiveness and the ability to create specific and consistent scent profiles. Synthetic ingredients offer manufacturers the flexibility to produce a wide range of fragrances that are not easily achievable with natural ingredients alone. The trend in the industry lies in finding a balance – developing natural alternatives for popular synthetic ingredients and innovating in sustainable sourcing practices. This dual approach allows companies to cater to the growing demand for natural products while maintaining the affordability and diversity provided by synthetic chemicals.
Transparency and Ethical Sourcing
Another major trend in the North America Perfume Ingredients Chemicals Market is the increasing demand for transparency and ethical sourcing. For example, 50% of consumers now look for products with clear sourcing information, and there has been a 20% increase in the adoption of cruelty-free practices by perfume companies. This has led to a 30% rise in the number of companies obtaining certifications for sustainable practices, reflecting the growing demand for ethical and transparent production in the perfume industry. Consumers are demanding greater insight into the origins and production practices of the perfume ingredients they purchase. This trend translates to a focus on ethical sourcing, cruelty-free practices, and sustainability throughout the supply chain. Companies are being pushed to provide clear and detailed information about their sourcing practices, ensuring that their ingredients are obtained in a manner that is respectful to both people and the planet. This includes adopting cruelty-free methods, ensuring fair labor practices, and minimizing environmental impact. The transparency trend also ties into the growing consumer interest in clean and green beauty products, which prioritize natural ingredients and sustainable practices. As a result, companies are investing in certifications and labels that validate their commitment to ethical and sustainable practices, enhancing their brand reputation and building consumer trust.
Market Challenges Analysis
Strict Regulatory Environment and Raw Material Price Fluctuations
The North America Perfume Ingredients Chemicals Market operates within a strict regulatory environment focused on safety and environmental standards. While these regulations are beneficial for consumer protection, they pose significant challenges for manufacturers. Compliance with stringent regulations can be a complex and costly process, particularly for smaller companies with limited resources. The need to adhere to rigorous safety standards and restrictions on certain ingredients can hinder innovation and elevate development costs. This regulatory landscape requires manufacturers to invest heavily in research and development to create compliant products without compromising on quality or performance. Additionally, fluctuations in raw material prices add another layer of complexity. The perfume industry relies on a variety of natural and synthetic raw materials, which are often subject to price volatility due to factors such as weather conditions, geopolitical events, and resource scarcity. These fluctuations can disrupt production costs, impacting the profitability of manufacturers. Companies must navigate these financial uncertainties while maintaining the quality and consistency of their products, which can be particularly challenging for smaller and medium-sized enterprises.
Competition and Counterfeiting
The North America Perfume Ingredients Chemicals Market is highly competitive, featuring major international fragrance houses and established domestic companies. This intense competition puts pressure on profit margins and necessitates continuous innovation and differentiation, especially for smaller businesses striving to establish a foothold. To remain competitive, companies must consistently develop new and unique fragrance offerings, invest in marketing, and maintain high standards of product quality. This competitive pressure can be financially and operationally demanding, requiring strategic agility and robust investment in innovation. Moreover, the issue of counterfeiting and product piracy poses a significant challenge. Counterfeit perfumes and fragrance ingredients undermine brand reputation and negatively impact legitimate businesses. The proliferation of fake products in the market erodes consumer trust and can lead to significant financial losses for authentic brands. Combating counterfeiting requires a collaborative effort between manufacturers, retailers, and regulatory bodies to implement stringent anti-counterfeiting measures and ensure product authenticity. Companies must invest in advanced labeling, packaging technologies, and robust supply chain tracking systems to protect their brands and maintain consumer confidence.
Market Segmentation Analysis:
By Product Type:
The North America Perfume Ingredients Chemicals Market is segmented by product type into synthetic aroma chemicals and essential oils. Synthetic aroma chemicals dominate the market due to their cost-effectiveness and ability to create specific and consistent scent profiles. Key sub-segments within synthetic aroma chemicals include alcohols, esters, ethers, ketones, and others (such as thiols and dienals). Alcohols are widely used as solvents and carriers, while esters and ethers add sweet and fruity notes to fragrances. Ketones contribute to diverse scent profiles, enhancing the complexity of perfumes. On the other hand, essential oils are gaining traction due to increasing consumer preference for natural and eco-friendly ingredients. Essential oils such as orange, citronella, peppermint, eucalyptus, and others (including rose and sandalwood) are valued for their therapeutic properties and rich, complex aromas. This balance between synthetic and natural ingredients reflects the market's adaptability to varied consumer demands, catering to preferences for both traditional and innovative fragrance components.
By Application:
Based on application, the North America Perfume Ingredients Chemicals Market is divided into fine fragrance, home care, laundry care, cosmetics, and others. The fine fragrance segment holds a significant share, driven by the high demand for luxury and personalized scents. Consumers' increasing interest in high-quality and long-lasting perfumes fuels this segment. Home care products, including air fresheners and cleaning agents, utilize perfume ingredients to enhance the sensory experience, making this a growing segment. Laundry care products, such as detergents and fabric softeners, heavily rely on fragrance chemicals to provide fresh and appealing scents, contributing to consumer satisfaction and brand loyalty. The cosmetics segment, encompassing skincare, haircare, and personal care products, benefits from the use of perfume ingredients to enhance product appeal and differentiation. Other applications include industrial and institutional products where fragrance plays a crucial role in masking odors and improving user experience. This diverse application landscape underscores the versatility of perfume ingredients chemicals in meeting varied consumer needs across different sectors.
Segments:
Based on Product Type:
- Synthetic Aroma Chemicals
- Alcohol
- Esters
- Ethers
- Ketone
- Others (Thiols, Dienals, etc.)
- Essential Oils
- Orange
- Citronella
- Peppermint
- Eucalyptus
- Others (Rose, Sandalwood, Orange etc.)
Based on Application:
- Fine Fragrance
- Home Care
- Laundry Care
- Cosmetics
- Others
Based on the Geography:
- US.
- Canada
- Mexico
Regional Analysis
The United States dominates the region, accounting for approximately 70% of the market share. This dominance is attributed to the presence of major fragrance houses, a robust retail sector, and high consumer spending on personal care products. The U.S. market is characterized by a growing demand for natural and organic ingredients, reflecting increasing health and environmental consciousness among consumers. Canada follows with about 20% of the market share, showing similar trends in eco-friendly and sustainable fragrances. The Canadian market benefits from a diverse consumer base and strong regulations supporting product safety and quality.
Mexico holds the remaining 10% of the North American market share, presenting significant growth potential. The Mexican perfume ingredients market is experiencing rapid expansion due to rising disposable incomes and a growing middle class. Local manufacturers are increasingly partnering with international fragrance houses to develop unique scents that appeal to both domestic and global markets. Across North America, there's a notable shift towards personalized fragrances and niche perfumes, driving innovation in ingredient formulations.
Key Player Analysis
- BASF SE
- Eternis Fine Chemicals
- YingYang (China) Aroma Chemical Group
- KDAC CHEM Pvt. Ltd.
- Frutarom Harmony Organics Pvt. Ltd.
- GODAVARI BIOREFINERIES LTD
- Givuadan Firmenich
- International Flavors and Fragrances Inc.
- Takasago International Corporation
- Huabao International Holdings Limited
- Henkel AG & Co KGaA ADR
- Charkit Chemical Company LLC
Competitive Analysis
The North America Perfume Ingredients Chemicals Market is highly competitive, with leading players such as BASF SE, International Flavors and Fragrances Inc., Givuadan Firmenich, Takasago International Corporation, and Henkel AG & Co KGaA ADR dominating the landscape. BASF SE leverages its extensive R&D capabilities and diversified product portfolio to maintain a competitive edge. International Flavors and Fragrances Inc. and Givuadan Firmenich excel in innovation and customer-centric approaches, continuously developing unique and high-quality fragrance ingredients. Takasago International Corporation stands out with its expertise in both natural and synthetic ingredients, catering to the rising demand for eco-friendly products. Henkel AG & Co KGaA ADR emphasizes strategic partnerships and acquisitions to expand its market presence. These companies compete on the basis of product quality, innovation, and sustainability, driving continuous advancements in the market. The competitive landscape is further characterized by the need for compliance with stringent regulations and the ability to meet evolving consumer preferences for natural and personalized fragrances.
Recent Developments
- In January 2023, S H Kelkar and Company revealed that its wholly owned subsidiary, Keva Europe B.V. acquired a 100% stake in PFW Aroma Ingredients B.V. (PFW) from Keva UK. The acquisition has strengthened the aroma chemicals business of the company.
- In August 2022, Oriental Aromatics Ltd. announced an investment of nearly INR 1.3 - 1.5 billion (USD 15.69 - 18.10 million) for the development of a hydrogenation plant in Vadodara for specialty aroma chemicals. The plant is expected to be commissioned by the H2 of F.Y. 2024.
- In May 2022, DSM Group, a Dutch company, acquired Firmenich, a Switzerland-based perfume manufacturer.
Market Concentration & Characteristics
The North America Perfume Ingredients Chemicals Market exhibits moderate to high market concentration, with a few dominant players such as BASF SE, International Flavors and Fragrances Inc., and Givuadan Firmenich holding significant market shares. These leading companies leverage their extensive R&D capabilities, diverse product portfolios, and robust distribution networks to maintain their competitive positions. The market is characterized by a strong emphasis on innovation, driven by consumer demand for both synthetic and natural ingredients. Companies invest heavily in developing eco-friendly and sustainable products to align with evolving consumer preferences and regulatory requirements. The market also features a dynamic interplay between traditional luxury fragrances and emerging trends towards personalized and niche scents. This combination of established leaders and the continuous introduction of new, innovative products creates a vibrant and competitive market environment, fostering growth and development in the industry.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Application, and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The North America Perfume Ingredients Chemicals Market is expected to see continued growth due to rising consumer demand for personalized and premium fragrances.
- Advancements in synthetic aroma chemicals will enhance fragrance variety and consistency.
- Increasing preference for natural and sustainable ingredients will drive demand for essential oils.
- E-commerce expansion will boost accessibility and sales of perfume ingredients.
- Regulatory trends towards safety and sustainability will push companies to innovate in compliance with stricter standards.
- The market will witness a rise in direct-to-consumer (D2C) perfume brands offering unique experiences.
- Growth in the personal care and cosmetics industries will positively impact the demand for fragrance chemicals.
- Companies will invest more in ethical sourcing and sustainable production practices.
- Technological advancements in fragrance formulation will lead to the development of new and unique scent profiles.
- Collaboration between manufacturers, retailers, and regulatory bodies will intensify to combat counterfeiting and ensure product authenticity.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the North America Perfume Ingredients Chemicals Market?
What factors are driving the growth of the North America Perfume Ingredients Chemicals Market?
What are the key segments within the North America Perfume Ingredients Chemicals Market?
What are some challenges faced by the North America Perfume Ingredients Chemicals Market?
Who are the major players in the North America Perfume Ingredients Chemicals Market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 North America Perfume Ingredients Chemicals Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global North America Perfume Ingredients Chemicals Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 1,842.28 million → 2032: USD 3,020.97 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 North America Perfume Ingredients Chemicals Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. North America Perfume Ingredients Chemicals Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 North America Perfume Ingredients Chemicals Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 North America Perfume Ingredients Chemicals Market Drivers
- 3.3 North America Perfume Ingredients Chemicals Market Restraints & Challenges
- 3.4 North America Perfume Ingredients Chemicals Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 North America Perfume Ingredients Chemicals Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 North America Perfume Ingredients Chemicals Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, North America Perfume Ingredients Chemicals category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 North America Perfume Ingredients Chemicals Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. North America Perfume Ingredients Chemicals Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to North America Perfume Ingredients Chemicals. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 North America Perfume Ingredients Chemicals Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 North America Perfume Ingredients Chemicals Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 North America Perfume Ingredients Chemicals Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in North America Perfume Ingredients Chemicals (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in North America Perfume Ingredients Chemicals
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global North America Perfume Ingredients Chemicals Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America North America Perfume Ingredients Chemicals Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe North America Perfume Ingredients Chemicals Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific North America Perfume Ingredients Chemicals Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America North America Perfume Ingredients Chemicals Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East North America Perfume Ingredients Chemicals Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa North America Perfume Ingredients Chemicals Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. North America Perfume Ingredients Chemicals Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
