
Market Overview:
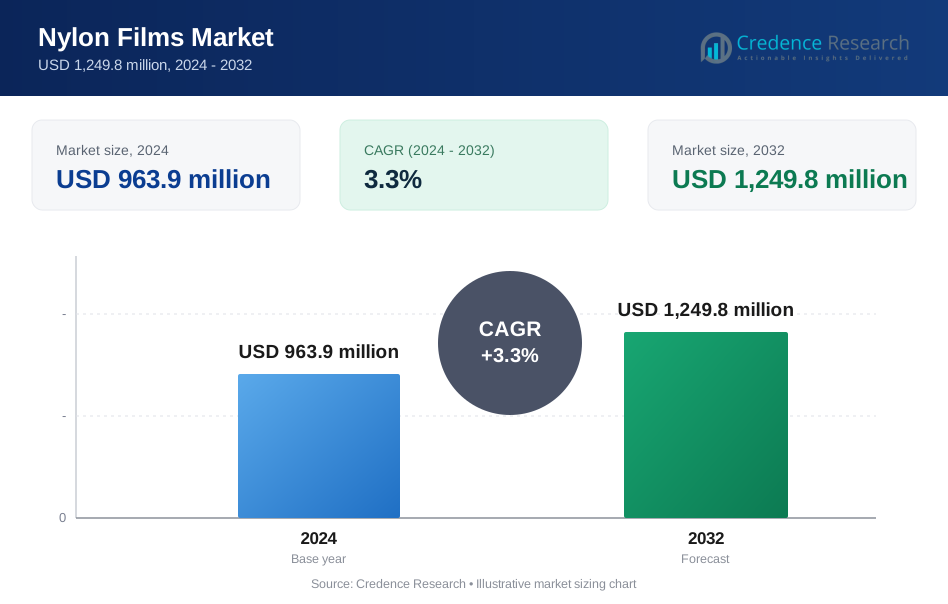
The Nylon films market is projected to grow from USD 963.9 million in 2024 to an estimated USD 1,249.8 million by 2032, with a compound annual growth rate of 3.3% from 2024 to 2032.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Nylon Films Market Size 2024 | USD 963.9 million |
| Nylon Films Market, CAGR | 3.3% |
| Nylon Films Market Size 2032 | USD 1,249.8 million |
Market growth is driven by rising demand for high-barrier flexible packaging across food and pharmaceutical sectors. Nylon films support longer shelf life and protect products from moisture and oxygen exposure. Processed food consumption continues to expand, supporting film usage in vacuum and retort packaging. Industrial users prefer nylon films for puncture resistance and heat stability. Medical packaging demand supports growth due to sterilization compatibility. Lightweight packaging trends also favor nylon films over rigid materials. Improved film processing enhances clarity, strength, and sealing efficiency.
Asia Pacific leads the market due to strong packaging demand from food processing and consumer goods industries. China and India benefit from large manufacturing bases and rising packaged food consumption. North America shows stable demand from medical packaging and industrial applications. Europe maintains growth through sustainable packaging initiatives and advanced material usage. Emerging markets in Southeast Asia and Latin America gain traction from urbanization and retail expansion. Local film production capacity supports faster adoption across developing regions.

Market Insights:
- The market overview shows growth from USD 963.9 million in 2024 to USD 1,249.8 million by 2032, at a CAGR of 3.3%, driven by steady packaging demand.
- Asia-Pacific leads with about 42% share due to strong food processing and manufacturing scale, followed by North America at 25% and Europe at 22%, supported by pharmaceutical and industrial use.
- Asia-Pacific is also the fastest-growing region, holding 42% share, driven by urbanization, packaged food expansion, and rising local film production capacity.
- By end use, food packaging accounts for nearly 55% share due to shelf life and safety needs, while pharmaceutical applications contribute around 18% from regulated packaging demand.
- By material, BOPA films hold about 60% share for clarity and barrier strength, while composite polyamide accounts for roughly 40% due to multi-layer performance needs.
Market Drivers:
Rising Demand For High-Barrier Flexible Packaging Across End-Use Industries
The Nylon films market gains momentum from rising demand for high-barrier flexible packaging. Food manufacturers prefer nylon films for strong oxygen and moisture resistance. Shelf life extension remains a key purchase factor for packaged food brands. Pharmaceutical companies rely on nylon films for product protection and safety. Medical packaging needs stable materials during sterilization cycles. Nylon films support puncture resistance in heavy-duty packaging formats. Brand owners favor consistent performance across transport conditions. This demand supports steady volume growth across applications.
- For instance, Toray Industries reports its BOPA films achieve oxygen transmission rates below 50 cc/m²/day, supporting long shelf-life food packaging applications.
Growing Preference For Lightweight And Durable Packaging Materials
Lightweight packaging demand supports wider use of nylon films across industries. Logistics firms prefer reduced material weight for lower transport costs. Nylon films maintain strength despite thinner gauges. Consumer goods brands adopt flexible packs for handling ease. Industrial users value durability during storage and transit. Packaging converters benefit from material efficiency gains. The Nylon films market benefits from durability without performance trade-offs. Material reliability sustains long-term customer contracts.
- For instance, UFlex Ltd. offers MLP packs with 20% PCR content and has developed specialty polymeric films to replace nylon, enabling significant material reduction at the source while maintaining mechanical strength standards.
Expansion Of Processed And Ready-To-Eat Food Consumption
Processed food consumption continues to rise across urban markets. Nylon films protect ready-to-eat meals from contamination risks. Vacuum packaging formats depend on strong sealing properties. Frozen food producers require materials with low temperature tolerance. Nylon films maintain integrity under thermal stress. Food safety regulations encourage reliable packaging solutions. Packaging suppliers focus on quality consistency. This consumption shift supports stable market demand.
Increasing Use In Medical And Pharmaceutical Packaging Applications
Healthcare packaging requires materials with high safety standards. Nylon films support sterile barrier systems for medical devices. Pharmaceutical blister and pouch formats use nylon layers. Regulatory compliance favors proven material performance. Hospitals and suppliers demand traceable packaging quality. Nylon films withstand chemical exposure during handling. The Nylon films market benefits from healthcare sector trust. Medical demand provides steady revenue streams.
Market Trends:
Shift Toward Multi-Layer Film Structures For Performance Optimization
Manufacturers adopt multi-layer film structures for advanced performance needs. Nylon films integrate with PE and EVOH layers. This structure balances strength, sealability, and flexibility. Packaging designers target custom material properties. Multi-layer formats support diverse end-use requirements. Film converters invest in co-extrusion technologies. The Nylon films market follows demand for tailored solutions. Product differentiation becomes a key strategy.
Rising Focus On Improved Clarity And Aesthetic Appeal
Brand visibility drives focus on packaging clarity. Nylon films offer high transparency for product display. Retail packaging favors visual appeal on shelves. Clear films enhance consumer trust and product perception. Improved optics support premium food packaging formats. Film producers refine resin formulations for clarity. Packaging aesthetics influence brand positioning decisions. Visual quality becomes a selection factor.
- For instance, Unitika Ltd. highlights that its transparent nylon films achieve light transmittance above 90%, supporting premium retail food packaging.
Adoption Of Advanced Film Processing And Extrusion Technologies
Film producers invest in modern extrusion equipment. Advanced processes improve thickness control and strength. Production efficiency gains reduce material waste. Consistent film quality supports large-scale supply contracts. Automation improves output reliability. Nylon films benefit from tighter quality tolerance. Technology upgrades support cost control. Process innovation shapes supplier competitiveness.
Customization Of Film Grades For Specific Industrial Applications
End users demand films tailored to application needs. Nylon films see grade variations for heat, impact, and flexibility. Industrial packaging needs higher puncture resistance. Food packaging prefers balanced barrier performance. Medical users require clean and uniform surfaces. Custom grades support niche applications. The Nylon films market aligns with application-specific demand. Customization enhances supplier value.
Market Challenges Analysis:
Volatility In Raw Material Prices And Supply Stability Issues
Raw material price volatility challenges cost planning for manufacturers. Nylon resin prices fluctuate due to petrochemical dependency. Supply disruptions affect production schedules. Smaller producers face margin pressure during price swings. Long-term contracts become difficult to manage. Cost uncertainty impacts pricing strategies. The Nylon films market faces risk from input instability. Manufacturers seek procurement efficiency to reduce exposure.
Recycling Limitations And Environmental Compliance Pressure
Environmental regulations challenge traditional nylon film usage. Recycling multi-layer structures remains complex. Waste management systems lack nylon recovery scale. Sustainability targets pressure packaging suppliers. Customers demand lower environmental impact materials. Compliance costs increase operational burden. Nylon films face scrutiny from regulators and consumers. Environmental adaptation requires investment and innovation.
Market Opportunities:
Development Of Sustainable And Recyclable Nylon Film Solutions
Sustainable packaging creates new growth paths for manufacturers. Nylon films can evolve with recyclable mono-material designs. Research focuses on easier material separation. Brands seek compliant packaging solutions. Regulatory support encourages innovation. Sustainable grades attract premium buyers. The Nylon films market can expand through eco-focused offerings. Innovation supports long-term relevance.
Growth Potential In Emerging Packaging And Industrial Markets
Emerging economies show rising demand for packaged goods. Urbanization increases packaged food consumption. Industrial activity supports demand for protective films. Local manufacturing expansion favors regional suppliers. Infrastructure growth boosts industrial packaging needs. Nylon films suit diverse climate conditions. The Nylon films market gains traction in developing regions. Expansion supports volume growth opportunities.
Market Segmentation Analysis:
By Grade
Nylon 6 holds wide adoption due to balanced strength, flexibility, and cost control. Food and industrial packaging users prefer this grade for reliable barrier performance. Nylon 66 serves applications that require higher heat resistance and mechanical strength. Automotive, electrical, and heavy-duty packaging rely on this grade. The Nylon films market uses both grades to address diverse performance needs. Grade selection depends on thermal stability, durability, and end-use exposure conditions.
- For instance, the Mitsubishi Chemical Group notes that while Nylon 66 (PA66) films can withstand short-term exposures up to 170°C–180°C, their continuous allowable service temperature in air is typically rated between 80°C and 95°C, supporting its use as an electrical insulator in environments with moderate thermal demands.
By Thickness
Up to 10 microns suits lightweight and cost-sensitive packaging formats. This range supports sachets and small consumer packs. Thickness between 11 to 20 microns sees strong demand in food packaging. The 21 to 30 microns range serves vacuum and retort packaging needs. Above 30 microns supports industrial and chemical packaging. Thickness choice reflects protection level and handling stress.
- For instance, Mondi Group produces high-performance multi-layer barrier films, often incorporating nylon (PA) layers, which are engineered for the high puncture resistance required for vacuum-sealed meat packaging used by large food processors.
By Material
Bi-Axially Oriented Polyamide offers high clarity and strong barrier properties. Food and pharmaceutical packaging favor this material type. Composite Polyamide supports multi-layer structures for enhanced performance. Industrial and chemical packaging rely on composite designs. Material selection balances strength, sealability, and application complexity.
By End Use
Food remains the leading end-use segment due to shelf life and safety needs. Pharmaceutical packaging depends on sterile barrier performance. Electrical applications use nylon films for insulation and protection. Chemical packaging values puncture resistance and stability. Other uses include consumer and industrial goods. End-use demand reflects functional performance priorities.
Segmentation:
By Grade
- Nylon 6
- Nylon 66
By Thickness
- Up to 10 Microns
- 11 to 20 Microns
- 21 to 30 Microns
- Above 30 Microns
By Material
- Bi-Axially Oriented Polyamide (BOPA)
- Composite Polyamide (CPA)
By End Use
- Food (Meat, Cereals, Cheese, Processed Food)
- Pharmaceutical
- Electrical
- Chemical
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
Asia-Pacific
Asia-Pacific leads the global landscape with an estimated market share of about 42%. The Nylon films market benefits from strong food packaging demand across China, India, and Southeast Asia. Expanding urban populations support higher consumption of packaged and processed foods. Regional manufacturers invest in flexible packaging capacity to serve domestic demand. Cost-efficient production supports competitive pricing. Industrial growth also raises demand from electrical and chemical applications. Local supply chains improve market responsiveness.
North America
North America holds nearly 25% of the global market share. The Nylon films market gains support from advanced food processing and pharmaceutical sectors. Strong regulatory standards favor high-performance packaging materials. Medical and pharmaceutical packaging drives steady volume demand. Industrial users rely on nylon films for durability and safety. Technology adoption supports consistent product quality. Stable consumption patterns ensure predictable demand across end-use segments.
Europe, Latin America, And Middle East & Africa
Europe accounts for around 22% of total market share. The Nylon films market benefits from strong adoption in Western Europe due to advanced packaging standards. Sustainability policies influence material selection across food and pharmaceutical packaging. Eastern Europe shows moderate growth from industrial expansion. Latin America contributes close to 7% share, supported by retail and food packaging growth. Middle East & Africa hold about 4% share, driven by rising packaged food demand. Infrastructure development supports gradual market expansion.
Key Player Analysis:
- Toray Industries
- Mondi Group
- Uflex Ltd.
- Unitika Ltd.
- Mitsubishi Chemical Corporation
- Domo Chemicals
- Amcor
- Cosmo Films
- KOLON Industries
- Honeywell International
Competitive Analysis:
The Nylon films market shows a moderately consolidated competitive structure with global and regional players. Large manufacturers focus on scale efficiency, product quality, and supply reliability. Companies invest in advanced extrusion and orientation technologies to improve film performance. Product portfolios cover food, pharmaceutical, and industrial packaging needs. Strategic partnerships help expand geographic reach and customer access. Cost control and raw material sourcing remain key competitive factors. Players compete on consistency, customization capability, and long-term supply contracts. Innovation supports differentiation in high-barrier and specialty film grades.
Recent Developments:
- Honeywell International announced on October 22, 2025, a significant organizational restructuring ahead of multiple planned business separations, including the completion of Solstice Advanced Materials' spin-off scheduled for October 30, 2025, and the planned separation of its Aerospace Technologies business anticipated in the second half of 2026. This restructuring positions Honeywell to focus on its core advanced materials and specialty chemicals operations while creating independent publicly traded companies better positioned to serve their respective markets. In the nylon distribution arena, Honeywell expanded its partnership with M. Holland to include flexible packaging applications, broadening nylon distribution channels to meet growing demand across food packaging, pharmaceuticals, and other flexible packaging segments requiring high-performance materials.
- Cosmo Films, now operating as Cosmo First Limited, significantly strengthened its market position through capacity expansion and strategic partnerships in 2025. In June 2025, the company commissioned a new BOPP (Biaxially-Oriented Polypropylene) production line, increasing total capacity by 45% to 277,000 metric tons per annum, positioning the company to capture growing demand for specialty films across global markets. The company's commitment to sustainable solutions is evident through its focus on mono-material structures designed for easy recyclability, helping customers reduce carbon footprints while maintaining performance across flexible packaging, labeling, and industrial applications. Building on its manufacturing expansion, Cosmo First entered a strategic 50-50 joint venture with Filmax Corporation, a leading South Korean films and chemicals company, announced in November 2025, combining Cosmo First's cutting-edge technology and global supply chain expertise with Filmax's robust brand equity and market reach in South Korea to introduce and scale multiple business verticals including specialty and consumer films, chemicals, and rigid packaging into the South Korean market while leveraging Cosmo's global networks to take Filmax products to international markets.
- Domo Chemicals is accelerating its transition toward a specialized, low-carbon polyamide portfolio while strengthening its regional manufacturing capabilities across Asia and Europe. At K 2025 in October, the company showcased Domamid MBB, a mass-balanced, bio-attributed PA 6 with up to 69% bio-attributed content and ISCC PLUS certification, representing a significant CO₂ reduction compared to fossil-based alternatives and serving applications in food and pharmaceutical packaging, textiles, and engineering plastics. Domo is simultaneously advancing halogen-free flame-retardant solutions for evolving e-mobility requirements, introducing Technyl Star halogen-free FR solutions for EV battery modules and busbars, and developing breakthrough materials for battery housing applications in response to accelerating vehicle electrification and safety demands.
Report Coverage:
The research report offers an in-depth analysis based on By Grade, By Thickness, By Material, By End Use, and By Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand for high-barrier flexible packaging will continue to strengthen across food and medical applications.
- Food packaging will remain the largest consumption area due to shelf life and safety needs.
- Pharmaceutical packaging will support stable long-term demand through strict protection standards.
- Multi-layer nylon film structures will see wider adoption to improve strength and barrier balance.
- Customized film grades will gain importance for specialized industrial and chemical uses.
- Emerging economies will drive volume growth through urbanization and packaged food expansion.
- Manufacturing upgrades will improve efficiency and product consistency.
- Sustainability goals will influence material design and production methods.
- Regional production capacity will expand to meet local demand.
- Strategic partnerships will shape competition and market reach.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Nylon films market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Nylon films market projected to grow between 2025 and 2032?
Which Nylon films market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Nylon films market?
Who are the leading companies in the Nylon films market?
Which region commanded the largest share of the Nylon films market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Nylon Films Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Nylon Films Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 963.9 million → 2032: USD 1,249.8 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Nylon Films Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Nylon Films Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Nylon Films Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Nylon Films Market Drivers
- 3.3 Nylon Films Market Restraints & Challenges
- 3.4 Nylon Films Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Nylon Films Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Nylon Films Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Nylon Films category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Nylon Films Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Nylon Films Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Nylon Films market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Nylon Films Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Nylon Films Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Nylon Films Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Nylon Films (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Nylon Films Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Nylon Films Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Nylon Films Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Nylon Films Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Nylon Films Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Nylon Films Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Nylon Films Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Nylon Films Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Nylon Films Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
