
Market Overview
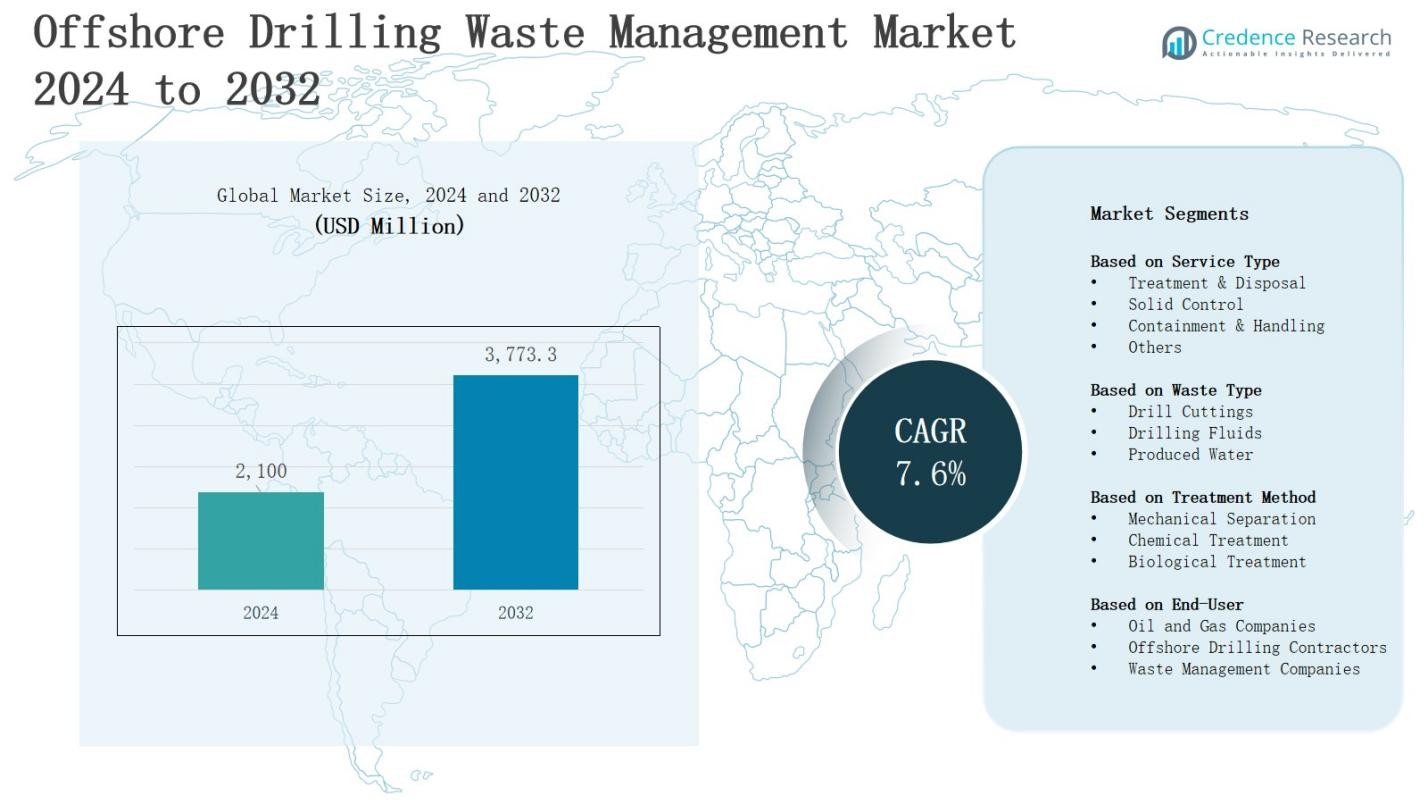
The offshore drilling waste management market is projected to grow from USD 2,100 million in 2024 to USD 3,773.3 million by 2032, registering a CAGR of 7.6% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Offshore Drilling Waste Management Market Size 2024 | USD 2,100 Million |
| Offshore Drilling Waste Management Market, CAGR | 7.6% |
| Offshore Drilling Waste Management Market Size 2032 | USD 3,773.3 Million |
The offshore drilling waste management market is driven by strict environmental regulations, rising offshore exploration, and increasing focus on sustainable waste handling practices. Companies adopt advanced treatment technologies to minimize ecological impact and meet compliance standards. Growth in deepwater and ultra-deepwater drilling activities further fuels demand for efficient waste management solutions. Trends include the integration of automation, real-time monitoring, and eco-friendly disposal methods to enhance operational efficiency. The shift toward circular economy practices and rising investments in oilfield waste recycling are strengthening market opportunities, positioning waste management as a critical component of sustainable offshore drilling operations.
The offshore drilling waste management market demonstrates diverse geographical dynamics, with North America leading at 36% share, driven by strict regulations and established infrastructure. Europe follows with 27%, supported by sustainable practices in the North Sea. Asia-Pacific holds 22%, fueled by deepwater exploration in China, India, and Southeast Asia. Latin America captures 8%, led by Brazil and Mexico, while the Middle East & Africa account for 7% with rising activity in West Africa and the Arabian Gulf. Key players include Baker Hughes, Halliburton, NOV, CLEAN HARBORS, Inc., and Augean.
Market Insights
- The offshore drilling waste management market is valued at USD 2,100 million in 2024 and projected to reach USD 3,773.3 million by 2032, growing at a 7.6% CAGR.
- Treatment and disposal dominate service type with 42% share, driven by strict regulations and environmental safety needs, while solid control holds 28%, and containment and handling account for 20%.
- Drill cuttings lead waste type with 46% share in 2024, followed by drilling fluids at 34% and produced water at 20%, reflecting high offshore waste volumes and regulatory pressures.
- Mechanical separation holds 40% share of treatment methods, followed by chemical treatment at 35% and biological treatment at 25%, supported by efficiency, compliance, and demand for eco-friendly solutions.
- North America leads regionally with 36% share, followed by Europe at 27%, Asia-Pacific at 22%, Latin America at 8%, and Middle East & Africa at 7%, supported by exploration activities.
Market Drivers
Stringent Environmental Regulations and Compliance Requirements
The offshore drilling waste management market is strongly driven by strict environmental laws and international conventions aimed at reducing pollution from oil and gas operations. Governments and regulatory bodies enforce rules that demand safe handling, treatment, and disposal of drilling waste. Companies invest in advanced systems to ensure compliance while avoiding penalties. It creates consistent demand for specialized solutions. Rising awareness of environmental sustainability further supports investments in cleaner, more efficient technologies across offshore operations.
- For instance, Halliburton introduced its BaraSure® drilling waste minimization system, which uses advanced solids-control equipment to reduce waste volumes offshore and ensure compliance with MARPOL Annex V regulations.
Expansion of Offshore Exploration and Production Activities
The offshore drilling waste management market benefits from the growing expansion of offshore oil and gas exploration in deepwater and ultra-deepwater fields. Rising global energy demand pushes operators to invest in complex projects requiring advanced waste management. It generates higher volumes of drilling waste that must be effectively managed. Growing exploration in emerging regions increases demand for service providers. The expansion strengthens the importance of reliable, scalable, and sustainable waste management infrastructure in the sector.
- For instance, TWMA’s 2024 contract with a UAE-based energy operator to provide sustainable drilling waste solutions, marking the company’s growing footprint in the Middle East.
Technological Advancements in Waste Treatment Solutions
The offshore drilling waste management market experiences strong growth through continuous technological innovation in waste treatment and disposal methods. Companies adopt advanced thermal, chemical, and mechanical processes to treat drill cuttings, fluids, and contaminated water. It enhances efficiency, reduces costs, and minimizes environmental harm. Automation and digital monitoring improve real-time decision-making and ensure better compliance. The development of eco-friendly disposal and recycling technologies supports industry sustainability goals while driving widespread adoption in offshore projects worldwide.
Focus on Circular Economy and Resource Recovery
The offshore drilling waste management market gains momentum from the global shift toward circular economy principles and resource recovery. Companies seek to reuse and recycle drilling waste materials to extract valuable by-products. It reduces landfill use and supports cost savings. Growing emphasis on corporate sustainability strategies drives investment in recycling infrastructure. Partnerships between oilfield service providers and waste management firms expand resource recovery initiatives. This approach strengthens long-term environmental protection and aligns with evolving industry standards.
Market Trends
Integration of Digital Technologies and Automation
The offshore drilling waste management market is witnessing a growing shift toward digitalization and automation to enhance efficiency and accuracy. Operators adopt real-time monitoring systems, IoT-enabled sensors, and automated waste treatment units to optimize processes. It helps in reducing human error, minimizing operational downtime, and ensuring compliance with environmental standards. Data-driven decision-making allows proactive maintenance and better resource allocation. The trend supports cost reduction while improving sustainability performance across offshore drilling projects worldwide.
- For instance, BMT’s IRMS technology enables remote monitoring of offshore assets, transmitting real-time environmental and performance data to support operational decisions during critical phases like platform abandonment.
Adoption of Eco-Friendly and Sustainable Solutions
The offshore drilling waste management market reflects a strong move toward eco-friendly practices that minimize environmental impact. Companies are deploying biodegradable chemicals, low-toxicity drilling fluids, and advanced cuttings reinjection methods. It ensures compliance with international environmental regulations while enhancing corporate responsibility. Investment in green technologies improves operational sustainability and reduces long-term costs. This trend aligns with the global energy industry’s broader push toward cleaner operations and supports the market’s steady transformation toward environmentally sound solutions.
- For instance, in Norway's North Sea region, companies strictly follow zero-discharge policies using advanced thermomechanical cuttings cleaners and bioremediation to treat and reduce drilling waste on-site.
Growing Demand for Recycling and Resource Recovery
The offshore drilling waste management market is experiencing increasing emphasis on recycling and resource recovery to reduce waste volumes and recover valuable materials. Oilfield service providers are adopting technologies to extract hydrocarbons and reusable minerals from drilling waste. It reduces dependence on disposal sites and lowers overall operational costs. Recycling initiatives also strengthen sustainability strategies for operators. The trend creates new revenue streams while reducing ecological damage, positioning recycling as a core element of waste management.
Regional Expansion into Emerging Offshore Fields
The offshore drilling waste management market is expanding into emerging offshore exploration regions such as West Africa, Latin America, and Asia-Pacific. These regions are witnessing growing investment in deepwater and ultra-deepwater drilling projects. It generates higher waste volumes and raises demand for reliable waste treatment solutions. Local governments encourage international collaboration to develop sustainable infrastructure. The trend highlights the rising global need for advanced waste management capabilities to support expanding offshore exploration and production activities.
Market Challenges Analysis
High Operational Costs and Complex Infrastructure Requirements
The offshore drilling waste management market faces significant challenges due to the high costs of advanced treatment technologies, specialized equipment, and compliance-driven operations. Operators must invest heavily in infrastructure such as thermal treatment units, cuttings reinjection systems, and chemical treatment facilities. It increases the overall project expenditure and limits adoption among smaller operators. The complexity of integrating waste management systems with offshore drilling platforms further adds to operational delays. Rising transportation costs for offshore waste disposal also remain a persistent challenge.
Stringent Regulatory Frameworks and Environmental Risks
The offshore drilling waste management market is constrained by strict international and regional environmental regulations that demand continuous monitoring and compliance. It increases administrative burdens and often requires frequent upgrades to technologies, driving higher costs for operators. Non-compliance risks severe penalties, reputational damage, and project delays. Environmental risks such as spills, contamination, and ineffective waste handling amplify concerns for stakeholders. The growing pressure to adopt sustainable practices creates challenges for companies struggling with cost constraints and resource limitations.
Market Opportunities
Advancements in Sustainable Technologies and Recycling Solutions
The offshore drilling waste management market presents strong opportunities through advancements in sustainable treatment and recycling technologies. Companies are developing innovative methods to recover hydrocarbons, reuse drilling fluids, and recycle solid waste into usable by-products. It reduces disposal costs while generating added revenue streams. Adoption of eco-friendly solutions enhances compliance with international regulations and strengthens corporate sustainability initiatives. Growing demand for closed-loop systems and biodegradable chemicals expands the scope for service providers offering green solutions globally.
Expansion of Offshore Exploration in Emerging Regions
The offshore drilling waste management market is set to benefit from increasing exploration activities in regions such as Africa, Latin America, and Asia-Pacific. Rising investments in deepwater and ultra-deepwater projects create higher volumes of drilling waste requiring efficient solutions. It provides opportunities for companies to establish partnerships, expand service networks, and introduce advanced technologies in untapped markets. Governments in these regions encourage sustainable practices, creating favorable conditions for market growth. This expansion supports long-term demand for reliable waste management infrastructure.
Market Segmentation Analysis:
By Service Type
In the offshore drilling waste management market, treatment and disposal services hold the dominant share of 42% in 2024. The segment leads due to rising regulatory pressure for safe disposal and the increasing need to minimize environmental impact. Solid control accounts for 28%, driven by demand for efficient separation of solids from drilling fluids. Containment and handling represent 20%, supported by offshore safety protocols. Other services make up 10%, covering niche applications and specialized requirements.
- For instance, National Oilwell Varco (NOV) delivers centrifuge-based solids control systems such as the HS-2172, which operators use for improved recovery of drilling fluids while reducing waste volumes.
By Waste Type
Drill cuttings dominate the offshore drilling waste management market with a 46% share in 2024, as they are generated in large volumes during exploration and production activities. Effective management of drill cuttings is crucial to avoid environmental risks. Drilling fluids hold 34%, fueled by the need to treat high volumes of synthetic and water-based fluids. Produced water accounts for 20%, reflecting increasing volumes from aging offshore wells and stricter discharge regulations.
By Treatment Method
Mechanical separation leads the offshore drilling waste management market with a 40% share in 2024. It remains the most widely adopted method due to its cost-effectiveness and operational efficiency in separating solids and liquids. Chemical treatment follows with 35%, driven by its effectiveness in treating contaminated fluids and produced water. Biological treatment captures 25%, supported by the growing emphasis on eco-friendly solutions and sustainability goals, though its adoption is limited to regions with advanced regulatory frameworks.
- For instance, Halliburton offers its BaraSolve™ Cuttings Reinjection technology, which uses mechanical separation to minimize offshore discharge while safely managing drill cuttings.
Segments:
Based on Service Type
- Treatment & Disposal
- Solid Control
- Containment & Handling
- Others
Based on Waste Type
- Drill Cuttings
- Drilling Fluids
- Produced Water
Based on Treatment Method
- Mechanical Separation
- Chemical Treatment
- Biological Treatment
Based on End-User
- Oil and Gas Companies
- Offshore Drilling Contractors
- Waste Management Companies
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
The offshore drilling waste management market in North America holds the largest share of 36% in 2024. The region benefits from mature offshore oil and gas operations in the Gulf of Mexico and strict regulatory frameworks that enforce safe waste handling. It drives continuous investments in advanced treatment and disposal technologies. Companies prioritize recycling and eco-friendly solutions to align with environmental standards. The presence of leading service providers strengthens regional dominance. High exploration activities and established infrastructure sustain long-term demand.
Europe
Europe accounts for 27% of the offshore drilling waste management market in 2024. The North Sea remains the focal point of drilling operations, supported by stringent EU regulations on waste treatment and disposal. It encourages the adoption of sustainable methods such as cuttings reinjection and chemical treatment. Governments and operators emphasize eco-friendly practices, creating opportunities for innovation. Investments in decommissioning projects further add to waste volumes requiring management. The region maintains strong growth potential through technology-driven sustainability initiatives.
Asia-Pacific
The offshore drilling waste management market in Asia-Pacific represents 22% of global share in 2024. Rapid industrialization and rising energy demand in China, India, and Southeast Asia fuel offshore exploration projects. It drives higher waste generation and creates demand for cost-effective treatment methods. Local governments strengthen regulations to reduce environmental risks and attract global service providers. Deepwater projects in regions like the South China Sea expand market opportunities. Increasing investments in infrastructure ensure steady adoption of advanced waste management systems.
Latin America
Latin America captures 8% of the offshore drilling waste management market in 2024. Brazil and Mexico lead regional growth with ongoing offshore exploration and production projects. It generates large volumes of drill cuttings and produced water, creating significant demand for treatment services. Regulatory pressure is gradually increasing, prompting investments in sustainable solutions. Partnerships with international players enhance service capabilities. Regional energy reforms and offshore licensing rounds contribute to expanding market opportunities for waste management providers.
Middle East & Africa
The offshore drilling waste management market in the Middle East & Africa holds 7% share in 2024. The region is driven by offshore exploration in West Africa and the Arabian Gulf. It requires efficient waste management solutions due to rising drilling volumes and environmental risks. Governments encourage sustainable practices, but infrastructure gaps limit widespread adoption. International service providers collaborate with national oil companies to bridge capability gaps. Ongoing investments in offshore projects create steady growth opportunities for waste management solutions.
Key Player Analysis
- Imdex Limited
- Ridgeline Canada Inc.
- Halliburton
- Derrick Corporation
- NOV
- CLEAN HARBORS, Inc.
- GN Solids Control
- Secure Energy Services
- Augean
- Baker Hughes Company
- Geminor
- Newpark Drilling Fluids LLC
Competitive Analysis
The offshore drilling waste management market is highly competitive, with companies focusing on technology innovation, regulatory compliance, and sustainability to strengthen their market position. It is characterized by the presence of established players such as Baker Hughes Company, Halliburton, NOV, and CLEAN HARBORS, Inc., which offer comprehensive waste management solutions integrated with drilling services. Augean, Secure Energy Services, and Ridgeline Canada Inc. focus on specialized treatment and disposal services tailored to regional needs. Derrick Corporation and GN Solids Control emphasize solid control technologies that improve drilling efficiency while reducing environmental risks. Newpark Drilling Fluids LLC and Imdex Limited concentrate on developing eco-friendly fluids and advanced monitoring systems to support sustainable operations. Geminor expands its role through recycling and resource recovery initiatives, addressing growing demand for circular economy practices. The competitive landscape is shaped by strategic partnerships, service expansions, and investments in advanced treatment methods. It continues to evolve as operators demand cost-effective, compliant, and environmentally responsible waste management solutions across offshore regions.
Recent Developments
- In April 2025, TWMA announced a three-year contract with TotalEnergies UK, starting October 2024, to deploy its RotoMill technology for on-site drill cuttings processing, reducing transport requirements and carbon emissions.
- In February 2023, Halliburton introduced a new cuttings reinjection system designed to reduce the environmental impact of offshore drilling operations
- In July 2025, Goldman Sachs Alternatives agreed to acquire Liquid Environmental Solutions, highlighting growing investment interest in waste management and circular economy opportunities across the energy sector.
Report Coverage
The research report offers an in-depth analysis based on Service Type, Waste Type, Treatment Method, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for advanced waste management technologies will rise with increasing offshore exploration and production activities.
- Strict environmental regulations will continue to drive adoption of eco-friendly drilling waste treatment and disposal methods.
- Recycling and resource recovery initiatives will gain traction, supporting sustainability and reducing overall operational waste volumes.
- Digital monitoring systems and automation will improve operational efficiency, compliance tracking, and real-time waste management decision-making.
- Deepwater and ultra-deepwater projects will generate higher waste volumes, increasing need for efficient treatment solutions.
- International partnerships between oilfield service providers and local operators will expand global market service capabilities.
- Biodegradable chemicals and green technologies will see wider use to meet growing environmental sustainability goals.
- Regional growth in Asia-Pacific, Latin America, and Africa will create new opportunities for market expansion.
- Investments in circular economy practices will transform waste into valuable by-products, reducing environmental and economic impact.
- Market competition will intensify with companies focusing on innovation, cost efficiency, and compliance-driven service models.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Offshore drilling waste management market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Offshore drilling waste management market projected to grow between 2025 and 2032?
Which Offshore drilling waste management market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Offshore drilling waste management market?
Who are the leading companies in the Offshore drilling waste management market?
Which region commanded the largest share of the Offshore drilling waste management market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Offshore Drilling Waste Management Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Offshore Drilling Waste Management Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 2,100 million → 2032: USD 3,773.3 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Offshore Drilling Waste Management Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Offshore Drilling Waste Management Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Offshore Drilling Waste Management Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Offshore Drilling Waste Management Market Drivers
- 3.3 Offshore Drilling Waste Management Market Restraints & Challenges
- 3.4 Offshore Drilling Waste Management Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Offshore Drilling Waste Management Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Offshore Drilling Waste Management Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Offshore Drilling Waste Management category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Offshore Drilling Waste Management Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Offshore Drilling Waste Management Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Offshore Drilling Waste Management. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Offshore Drilling Waste Management Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Offshore Drilling Waste Management Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Offshore Drilling Waste Management Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Offshore Drilling Waste Management (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Offshore Drilling Waste Management
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Offshore Drilling Waste Management Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Offshore Drilling Waste Management Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Offshore Drilling Waste Management Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Offshore Drilling Waste Management Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Offshore Drilling Waste Management Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Offshore Drilling Waste Management Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Offshore Drilling Waste Management Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Offshore Drilling Waste Management Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
