
Market Overview
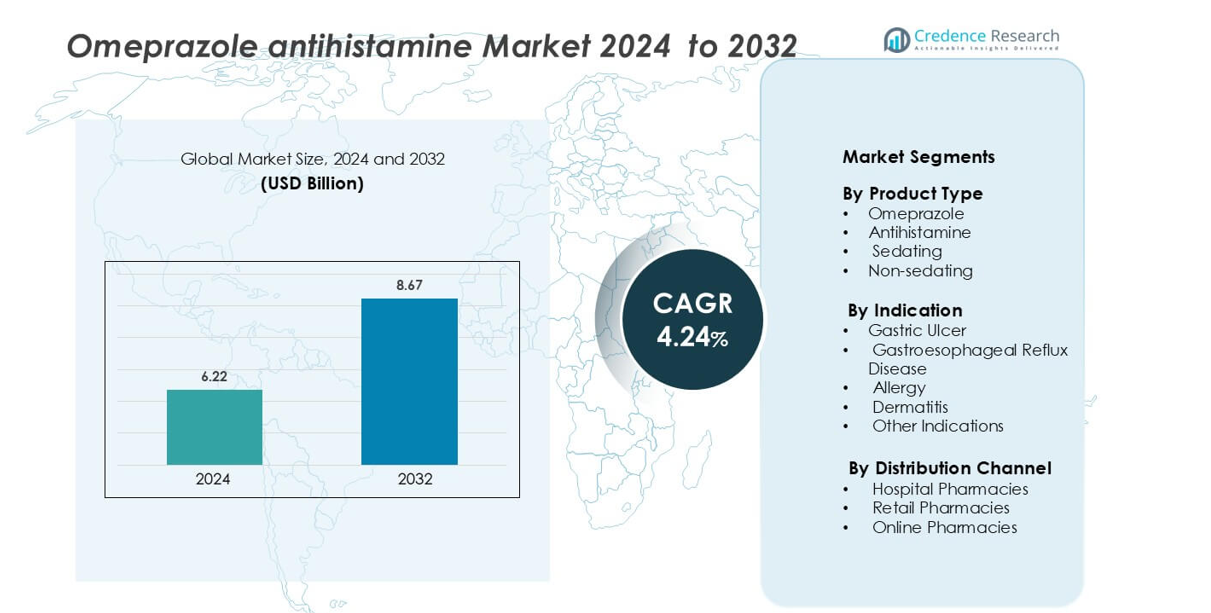
Omeprazole antihistamine Market size was valued USD 6.22 billion in 2024 and is anticipated to reach USD 8.67 billion by 2032, at a CAGR of 4.24% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Omeprazole Antihistamine Market Size 2024 | USD 6.22 billion |
| Omeprazole Antihistamine Market, CAGR | 4.24% |
| Omeprazole Antihistamine Market Size 2032 | USD 8.67 billion |
The omeprazole antihistamine market features strong competition among leading pharmaceutical companies focusing on innovation, safety, and treatment effectiveness. Major players include Pfizer Inc., Bayer AG, Takeda Pharmaceutical Company Limited, Johnson & Johnson, Novartis AG, GlaxoSmithKline PLC, AstraZeneca PLC, Sanofi S.A., Merck & Co., Inc., and Teva Pharmaceutical Industries Ltd. These companies are expanding their portfolios through improved formulations, long-acting non-sedating antihistamines, and enhanced omeprazole delivery systems. Asia Pacific dominates the global market with a 37% share, driven by high prevalence of acid reflux and allergic disorders, growing healthcare accessibility, and rapid urbanization across countries such as China, India, and Japan.
Market Insights
- The omeprazole and antihistamine market was valued at USD 6.22 billion in 2024 and is projected to reach USD 8.67 billion by 2032, growing at a CAGR of 4.24% during the forecast period.
- Rising prevalence of gastrointestinal and allergic disorders drives market growth, with omeprazole leading the product type segment holding a 46% share due to its effectiveness in GERD and ulcer treatment.
- Market trends include increasing adoption of non-sedating antihistamines and advanced oral formulations that improve patient compliance and therapeutic outcomes.
- The market is competitive, with key players such as Pfizer Inc., Bayer AG, Takeda Pharmaceutical Company Limited, and AstraZeneca PLC focusing on product innovation, regulatory approvals, and OTC product expansion.
- Asia Pacific dominates with a 37% share, followed by North America at 29% and Europe at 26%, supported by rising healthcare expenditure and growing access to prescription and over-the-counter medications.
Market Segmentation Analysis
By Product Type
The omeprazole segment dominates the market with a 46% share, driven by its widespread use in managing acid-related disorders such as gastric ulcers and gastroesophageal reflux disease (GERD). Omeprazole’s strong efficacy in reducing stomach acid secretion and its inclusion in standard treatment protocols enhance its adoption globally. The availability of both prescription and over-the-counter formulations supports accessibility across diverse patient groups. Additionally, the increasing prevalence of gastrointestinal conditions caused by unhealthy diets and stress continues to strengthen demand for omeprazole-based products.
- For instance, in one multi-center trial, 81% of gastric ulcer patients receiving 20 mg daily healed after four weeks. Other studies confirm that most patients with peptic ulcers heal within this timeframe.
By Indication
Gastroesophageal reflux disease (GERD) leads the indication segment with a 39% share due to rising cases linked to obesity, sedentary lifestyles, and poor dietary habits. Omeprazole-based therapies are the preferred treatment for long-term acid suppression, improving patient outcomes and quality of life. The allergy segment also shows notable growth driven by non-sedating antihistamines used for respiratory allergies. Increasing awareness of early diagnosis and chronic GERD management supports the segment’s sustained market dominance.
- For instance, Omeprazole 20 mg once daily produced complete heartburn resolution in 48% of patients by week four, compared with just 5% in the placebo group.
By Distribution Channel
Retail pharmacies hold the largest share at 51%, supported by their widespread availability and consumer preference for direct access to both prescription and over-the-counter medications. Pharmacies play a crucial role in distributing omeprazole and antihistamine drugs for gastrointestinal and allergy-related conditions. Growing patient convenience and accessibility in urban and semi-urban areas further enhance their dominance. Online pharmacies are rapidly expanding due to digital health adoption and home delivery options, while hospital pharmacies remain vital for dispensing medications in inpatient care and chronic condition management.
Key Growth Drivers
Rising Prevalence of Gastrointestinal and Allergic Disorders
The increasing global incidence of gastrointestinal diseases such as GERD, peptic ulcers, and acid reflux is a primary growth driver for the omeprazole and antihistamine market. Sedentary lifestyles, poor dietary patterns, and stress have led to higher cases of gastric and acid-related conditions. Similarly, rising air pollution, changing weather patterns, and allergen exposure are fueling the demand for antihistamines to manage allergic rhinitis, dermatitis, and respiratory allergies. The dual therapeutic demand across digestive and allergy-related treatments supports strong market expansion. Growing adoption of combination therapies and self-medication practices further accelerates product consumption in both segments.
- For instance, a 2006 trial found that esomeprazole was significantly more effective than omeprazole for patients with moderate to severe esophagitis (LA grades C or D).
Expanding Over-the-Counter (OTC) Availability and Accessibility
The shift toward over-the-counter accessibility of omeprazole and non-sedating antihistamines has significantly improved patient convenience and boosted sales. Consumers increasingly prefer OTC medications for mild to moderate symptoms of acidity, allergies, and nasal congestion. Regulatory approvals allowing wider retail availability of drugs such as omeprazole and loratadine are strengthening distribution networks globally. Retail pharmacies and e-commerce platforms have become major sales channels, expanding reach in both developed and emerging markets. This growing accessibility, coupled with increasing healthcare awareness and self-treatment culture, continues to drive the market’s overall growth trajectory.
- For instance, Pfizer launched Nexium 24HR as an OTC product, extending access to over 20,000 retail stores across the U.S., leading to double-digit growth in its digestive health segment.
Technological Advancements and Product Innovation
Continuous innovation in drug formulations and delivery systems enhances treatment effectiveness and patient compliance. Pharmaceutical companies are investing in developing sustained-release capsules, chewable tablets, and orally disintegrating formulations to improve convenience and bioavailability. In antihistamines, advancements have focused on non-sedating and long-acting compounds that minimize side effects while offering 24-hour symptom relief. Digital health tools and AI-based prescription management systems further support appropriate usage and adherence. The increasing adoption of novel drug delivery platforms not only boosts treatment outcomes but also provides companies with opportunities for product differentiation and market competitiveness.
Key Trends and Opportunities
Growing Adoption of Combination Therapies
The market is witnessing a strong trend toward combination drugs that address multiple symptoms simultaneously. Physicians increasingly prescribe formulations combining omeprazole with antihistamines or antibiotics to manage reflux-related coughs, allergic rhinitis with GERD, or H. pylori infections. This integrated treatment approach enhances patient outcomes while reducing polypharmacy risks. Pharmaceutical companies are capitalizing on this trend by developing multi-symptom relief products with optimized dosages and minimal side effects. The growing clinical evidence supporting such combinations and the convenience of single-dose regimens present lucrative opportunities for market expansion, particularly in emerging economies with high self-medication rates.
- For instance, a crossover study with 12 volunteers showed that adding ranitidine (150 mg or 300 mg) at bedtime to a twice-daily omeprazole regimen was more effective at suppressing nocturnal acid secretion (keeping intragastric pH > 4) than adding a third dose of omeprazole.
Expansion of Digital Health and Online Pharmacies
The integration of digital health solutions and e-commerce platforms is transforming the pharmaceutical distribution landscape. Online pharmacies enable easy access to omeprazole and antihistamine medications, supported by home delivery and teleconsultation services. This shift is particularly beneficial for chronic patients requiring regular refills. Moreover, digital prescription tools and patient adherence apps help ensure safe use and proper dosage. As internet penetration and digital literacy increase, especially in Asia-Pacific and Latin America, online pharmacy adoption is expected to grow. This digital shift creates new revenue streams and strengthens customer engagement in the long term.
- For instance, the UK-based digital health company Healthera rolled out a same-hour prescription delivery option and partnered with ride-share services to serve over 50 major pharmacies, offering direct-to-patient drug delivery for a broad range of medications.
Key Challenges
Side Effects and Drug Interaction Risks
Despite their effectiveness, both omeprazole and antihistamines face challenges related to side effects and potential drug interactions. Long-term omeprazole use can cause nutrient malabsorption, kidney complications, or gut microbiota imbalance. Sedating antihistamines may impair alertness, while non-sedating variants can still interact with other central nervous system medications. These safety concerns often lead to stricter prescription monitoring and limit extended use. Moreover, the growing emphasis on personalized medicine and regulatory oversight requires continuous pharmacovigilance efforts. Pharmaceutical companies must focus on patient education and risk mitigation strategies to maintain trust and compliance among healthcare professionals and consumers.
Rising Generic Competition and Price Pressure
The market faces significant pricing challenges due to the widespread availability of generic omeprazole and antihistamine formulations. Patent expirations have opened the market to multiple low-cost manufacturers, particularly in developing regions. While this expands accessibility, it also leads to intense price competition, compressing profit margins for branded producers. Additionally, reimbursement constraints in several countries push healthcare providers and consumers toward cost-effective generics. To remain competitive, leading companies are investing in brand differentiation, novel dosage forms, and patient-centric marketing. However, balancing affordability with innovation remains a persistent challenge across global markets.
Regional Analysis
North America
North America accounts for 29% of the global omeprazole and antihistamine market, driven by a high prevalence of GERD, allergies, and acid-related disorders. The United States leads the region due to a mature pharmaceutical sector and strong demand for OTC medications. Advanced healthcare infrastructure and high consumer awareness support market penetration across both urban and rural areas. Strategic partnerships among major drug manufacturers and retail pharmacy chains also enhance product accessibility. Canada contributes through expanding e-commerce drug distribution and rising self-medication practices for mild allergic and gastric conditions.
Europe
Europe holds a 26% share of the market, supported by well-established healthcare systems and strong demand for antihistamines in managing seasonal allergies. The United Kingdom, Germany, and France are key contributors due to high prescription rates for non-sedating antihistamines and proton pump inhibitors like omeprazole. Stringent drug quality regulations ensure safety and efficacy, boosting patient trust. Increasing adoption of generic formulations and online pharmacy expansion further strengthen the market. Moreover, Europe’s aging population and rising gastrointestinal health concerns continue to drive steady regional growth.
Asia Pacific
Asia Pacific leads the global omeprazole and antihistamine market with a 37% share, supported by rapid urbanization, population growth, and rising gastrointestinal and allergic disease prevalence. China, India, and Japan represent the largest consumer bases due to high pollution levels and dietary changes contributing to GERD and allergy cases. Expanding healthcare access and affordability of generic drugs further drive regional demand. Growing investment by domestic pharmaceutical companies and government efforts to improve OTC drug availability enhance market penetration. Strong e-commerce growth and digital pharmacy adoption continue to boost regional sales.
Latin America
Latin America captures 5% of the market, with Brazil and Mexico as leading contributors. The region’s growth is driven by expanding access to affordable medications and rising awareness of gastrointestinal and allergy treatments. Increasing retail pharmacy networks and improving healthcare infrastructure support the wider availability of omeprazole and antihistamine drugs. Economic development and lifestyle changes have also contributed to higher acid reflux and allergy cases. Local pharmaceutical manufacturing and government-supported healthcare reforms are expected to strengthen regional distribution channels and product accessibility.
Middle East & Africa
The Middle East & Africa region holds a 3% market share, driven by growing healthcare investments and improving pharmaceutical distribution systems. The UAE, Saudi Arabia, and South Africa are key markets supported by the rising burden of allergies, GERD, and skin-related disorders. Expanding retail pharmacies and increasing use of OTC medications are contributing to market growth. Government health programs promoting access to essential drugs are also improving patient outcomes. As awareness of gastrointestinal and allergic conditions increases, the region is poised for gradual but consistent market expansion
Market Segmentations:
By Product Type
- Omeprazole
- Antihistamine
- Sedating
- Non-sedating
By Indication
- Gastric Ulcer
- Gastroesophageal Reflux Disease
- Allergy
- Dermatitis
- Other Indications
By Distribution Channel
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The omeprazole antihistamine market features intense competition among major global pharmaceutical companies. Leading participants such as Pfizer Inc., Bayer AG, Takeda Pharmaceutical Company Limited, and Johnson & Johnson are expanding portfolios through innovative gastrointestinal therapies and combination drug formulations. Novartis AG and GlaxoSmithKline PLC focus on clinical advancements and strategic collaborations to improve efficacy and patient compliance. AstraZeneca PLC and Sanofi S.A. emphasize research partnerships and regional expansion to strengthen brand presence in emerging economies. Merck & Co., Inc. and Teva Pharmaceutical Industries Ltd. invest in generic omeprazole formulations to capture cost-sensitive markets. Continuous product innovation, patent extensions, and regulatory approvals drive competition, while increased emphasis on over-the-counter (OTC) availability enhances consumer accessibility. Strategic alliances, mergers, and targeted marketing campaigns support sustained growth and broader market penetration across therapeutic segments and regions.
Key Player Analysis
- Pfizer Inc.
- Bayer AG
- Takeda Pharmaceutical Company Limited
- Johnson & Johnson
- Novartis AG
- GlaxoSmithKline PLC
- AstraZeneca PLC
- Sanofi S.A.
- Merck & Co., Inc.
- Teva Pharmaceutical Industries Ltd.
Recent Developments
- In February 2024, Alkaloid developed the ready-to-use liquid omeprazole, which is primarily designed to treat reflux esophagitis and GERD in young children unable to swallow tablets, as well as in adult patients who have difficulty swallowing.
- In November 2023, Cipla officially launched the authorized generic version of its own branded product in the U.S. market. This is a common strategy to capture market share before patent challenges from other generic companies succeed.
- In March 2023, Tiefenbacher Pharmaceuticals launched bilastine, an innovative anti-allergy medicine for patients suffering from allergic symptoms, such as hay fever and urticaria, as an over-the-counter (OTC) drug in Germany.
- In June 2022, Purna Pharmaceuticals, with its marketing partner Cipla, received the first and only FDA approval for the FDC of Fexofenadine Hydrochloride and Omeprazole Magnesium (60 mg/20 mg and 180 mg/20 mg). The product is branded for the treatment of symptoms associated with gastroesophageal reflux disease (GERD) in patients with a history of acid-related damage who also require histamine-1 (H1) receptor antagonist therapy.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Indication, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will continue to grow due to rising cases of GERD and allergic disorders.
- Demand for non-sedating antihistamines will increase because of better safety and longer relief.
- OTC availability of omeprazole and antihistamine drugs will expand in developing regions.
- Technological innovations will enhance formulation stability and bioavailability of oral drugs.
- Pharmaceutical companies will focus on digital marketing and e-pharmacy partnerships.
- Asia Pacific will remain the leading regional market with strong consumer demand.
- North America will benefit from high awareness and established healthcare infrastructure.
- Increasing adoption of combination therapies will create new treatment opportunities.
- Regulatory emphasis on product safety and quality control will drive innovation.
- Continuous R&D investment in drug delivery systems will strengthen market competitiveness

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Omeprazole Antihistamine Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Omeprazole Antihistamine Market projected to grow between 2025 and 2032?
Which Omeprazole Antihistamine Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Omeprazole Antihistamine Market?
Who are the leading companies in the Omeprazole Antihistamine Market?
Which region commanded the largest share of the Omeprazole Antihistamine Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 6.22 billion → 2032: USD 8.67 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Omeprazole Antihistamine Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Omeprazole Antihistamine Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Omeprazole Antihistamine Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Omeprazole Antihistamine Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Omeprazole Antihistamine Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Omeprazole Antihistamine Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Omeprazole Antihistamine Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Omeprazole Antihistamine Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 6.22 billion → 2032: USD 8.67 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Omeprazole Antihistamine Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Omeprazole Antihistamine Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Omeprazole Antihistamine Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Omeprazole Antihistamine Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

