
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Organic Hair Care Market Size 2024 | USD 10,242.1 million |
| Organic Hair Care Market , CAGR | 6.83% |
| Organic Hair Care Market Size 2032 | USD 17,406.0 million |
Market Overview:
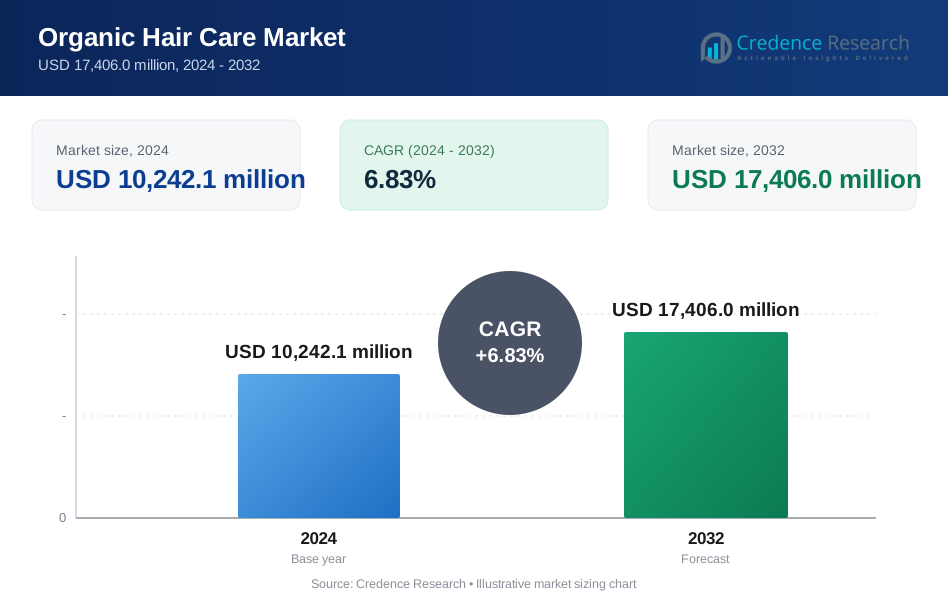
The Organic Hair Care Market size was valued at USD 6,572.0 million in 2018 to USD 10,242.1 million in 2024 and is anticipated to reach USD 17,406.0 million by 2032, at a CAGR of 6.83% during the forecast period.
The organic hair care market is experiencing significant growth due to rising consumer awareness of the potential health risks associated with synthetic ingredients in conventional products. Increasing concern over issues such as scalp sensitivity, allergic reactions, and long-term chemical exposure has led to greater demand for plant-based, non-toxic formulations. Consumers are prioritizing clean beauty, seeking transparency in product labeling and opting for sulfate-free, paraben-free, and cruelty-free alternatives. Additionally, the broader wellness and sustainability movements are encouraging ethical sourcing and eco-friendly packaging, further influencing purchase behavior. As digital literacy grows, access to product reviews, ingredient breakdowns, and influencer endorsements enhances informed decision-making. E-commerce platforms have made organic products more accessible, enabling niche brands to gain visibility alongside global players. Regulatory support favoring safer cosmetic formulations, combined with a shift in lifestyle preferences toward natural and holistic health solutions, continues to strengthen the market’s momentum across both developed and emerging economies.
North America leads the organic hair care market, driven by high consumer awareness, strong retail infrastructure, and widespread adoption of clean beauty practices. The region benefits from established brands and a supportive regulatory environment that encourages transparency and product safety. In Europe, consumer preference for organic and sustainable products is deeply rooted, particularly in Western countries with stringent environmental standards and growing demand for certified organic goods. Asia-Pacific emerges as a high-potential region, propelled by a blend of traditional herbal practices and modern wellness trends. Consumers in this region are increasingly embracing natural hair care as part of a broader shift toward healthier lifestyles. Latin America is gradually expanding its organic hair care footprint, with Brazil acting as a regional hub due to its rich biodiversity and cultural affinity for natural beauty solutions. The Middle East and Africa are also witnessing growing interest, especially in urban centers, where rising disposable incomes and awareness drive adoption.

Market Insights:
- The Organic Hair Care Market reached USD 10,242.1 million in 2024 and is projected to grow to USD 17,406.0 million by 2032, driven by a 6.83% CAGR.
- Growing awareness of the health risks posed by synthetic ingredients is pushing consumers toward plant-based, toxin-free hair care solutions.
- Regulatory support for clean formulations and transparent labeling is prompting brands to adopt certified organic ingredients and ethical manufacturing practices.
- A cultural shift toward holistic wellness is boosting demand for scalp-nourishing, ayurvedic, and aromatherapy-infused products across global markets.
- Digital platforms and influencers play a vital role in educating consumers, boosting visibility for D2C organic brands, and driving e-commerce sales.
- High production costs and lack of pricing parity with conventional alternatives limit accessibility, especially in cost-sensitive markets.
- North America leads in market share, Europe follows with strong regulatory backing, and Asia-Pacific is the fastest-growing region due to herbal traditions and rising disposable income.
Market Drivers:
Rising Consumer Preference for Natural and Clean Beauty Solutions
The growing awareness of potential health risks associated with synthetic chemicals in personal care products is driving consumers toward safer, plant-based alternatives. Consumers increasingly seek products free from sulfates, parabens, and artificial fragrances. The shift is fueled by a broader clean beauty movement that emphasizes transparency and trust in ingredient sourcing. Brands that clearly communicate their commitment to organic, cruelty-free, and non-toxic formulations gain stronger customer loyalty. The Organic Hair Care Market benefits from this trend, particularly among health-conscious and environmentally aware consumers. It positions itself as a safer, more sustainable option aligned with modern wellness values.
- For instance, BASF’s 2025 launch of Verdessence® Maize, a natural styling polymer, and Dehyton® PK45 GA/RA, a betaine derived from Rainforest Alliance Certified coconut oil, demonstrates the industry’s commitment to biodegradable, plant-based alternatives that do not compromise on performance.
Regulatory Pressure and Support for Safer Formulations
Governments and regulatory bodies in several regions are tightening restrictions on the use of harmful chemicals in cosmetic and personal care products. Stricter labeling requirements and bans on certain synthetic ingredients compel manufacturers to reformulate their offerings. This regulatory shift encourages the use of certified organic ingredients, which enhances product credibility in competitive markets. The emphasis on compliance drives innovation and accelerates the transition toward cleaner product lines. Consumers increasingly rely on certifications and safety standards to inform their purchasing decisions. The Organic Hair Care Market gains traction by aligning with these evolving compliance frameworks and offering certified, regulation-compliant products.
- For example, the Modernization of Cosmetics Regulation Act (MoCRA), effective January 2025, requires manufacturers to register facilities, submit complete product listings with full ingredient disclosure, and maintain safety documentation, including ingredient sourcing and testing records.
Cultural Shift Toward Holistic and Wellness-Based Lifestyles
A significant lifestyle shift toward holistic health practices is influencing consumer behavior across global markets. Hair care routines are now seen as part of broader self-care and wellness regimens rather than simple grooming activities. Consumers value products that nourish the scalp and hair while supporting long-term health benefits. This cultural evolution supports the demand for herbal, ayurvedic, and aromatherapy-based organic hair care products. It also encourages experimentation with natural remedies and alternative treatment options. The market responds by expanding offerings that emphasize therapeutic benefits and natural restoration.
Digital Influence and Direct-to-Consumer Brand Growth
Social media platforms, beauty influencers, and wellness blogs have become powerful tools for shaping consumer preferences in the hair care segment. Digital content drives awareness about ingredient safety, DIY organic solutions, and product comparisons. E-commerce platforms provide easier access to a wide range of organic hair care brands, including emerging niche players. Consumers increasingly research products online before purchasing, often prioritizing those with strong ethical positioning and transparent branding. Direct-to-consumer models enable smaller brands to build loyal communities and share their sustainability commitments. The Organic Hair Care Market capitalizes on this digital shift by strengthening its presence across online channels and tailoring offerings to digitally active consumers.
Market Trends:
Growing Demand for Multifunctional Organic Hair Care Products
Consumers are increasingly seeking hair care solutions that offer multiple benefits in a single product. Products that combine cleansing, nourishment, scalp care, and styling properties are gaining traction. This trend is particularly visible in shampoo-conditioner hybrids, leave-in treatments with botanical extracts, and masks that double as scalp therapy. The Organic Hair Care Market is responding by introducing formulations that integrate essential oils, vitamins, and adaptogens to meet diverse needs. It reflects the consumer’s preference for convenience without compromising on clean and effective ingredients. The shift toward minimalist routines drives innovation in multiuse organic products.
- For example, Innersense Organic Beauty’s Hair Renew Scalp Hairbath and Hair Renew Soothing Conditioner, launched in January 2025, exemplify this trend with a clinically proven treatment system that delivers visible scalp health improvements in just 30 days.
Surge in Ayurvedic and Herbal Ingredient Adoption
Traditional herbal remedies are gaining global recognition due to their perceived safety and efficacy. Brands are incorporating ingredients like amla, bhringraj, neem, tea tree oil, and aloe vera to appeal to health-conscious buyers. This trend reflects a resurgence of interest in ancient hair care practices that emphasize balance, nourishment, and scalp wellness. The Organic Hair Care Market is increasingly blending modern cosmetic science with time-tested herbal formulations to build credibility and trust. It allows brands to differentiate their offerings while aligning with consumer preferences for authenticity and plant-derived ingredients. Demand for naturally derived functional components continues to rise across all product types.
Increased Focus on Sustainable and Zero-Waste Packaging
Environmental awareness is playing a key role in influencing purchasing behavior within the beauty and personal care space. Consumers prefer brands that adopt eco-conscious packaging strategies, including recyclable bottles, biodegradable materials, and refillable systems. The Organic Hair Care Market is evolving to meet these expectations by reducing plastic usage and embracing circular economy models. It encourages innovation in solid bars, compostable containers, and packaging sourced from post-consumer recycled materials. This sustainable shift helps brands reinforce their ethical positioning and deepen customer loyalty. Retailers are also adopting low-waste practices, reflecting alignment with consumer values.
- For example, Lush Cosmetics has pioneered “naked” solid shampoos and conditioners, eliminating packaging entirely, while RMS Beauty shifted to 100% post-consumer recycled plastic lids in 2022, setting a new industry benchmark for luxury eco-conscious packaging.
Expansion of Gender-Neutral and Inclusive Product Lines
There is a noticeable trend toward gender-neutral hair care products that cater to diverse hair types and cultural preferences. Consumers increasingly prioritize performance and ethical values over traditional gender-based branding. The Organic Hair Care Market is adapting by launching inclusive formulations suitable for textured, curly, straight, and color-treated hair across all demographics. It promotes accessibility and diversity in product messaging and design. Inclusive marketing and broader product availability appeal to younger audiences who value representation and authenticity. This trend supports long-term brand relevance in an evolving personal care landscape.
Market Challenges Analysis:
High Production Costs and Pricing Pressures Limit Accessibility
Organic hair care products often require premium-quality ingredients that are sourced through certified and sustainable processes. These inputs tend to be more expensive than synthetic alternatives, leading to higher manufacturing costs. Brands must also invest in rigorous quality testing and certification to meet organic labeling standards, which increases operational expenses. The Organic Hair Care Market faces pricing pressure as consumers compare it with lower-cost conventional products. It becomes difficult for some brands to strike a balance between affordability and authenticity without compromising margins. Price-sensitive consumers may hesitate to make the switch, limiting penetration in certain emerging markets.
Lack of Standardization and Market Misinformation Undermine Trust
The absence of universally recognized definitions and regulations for “organic” in personal care leaves room for vague labeling and marketing claims. Some brands take advantage of this gap by promoting partially organic or “natural-inspired” products without meeting strict standards. This practice creates confusion among consumers and diminishes confidence in the category. The Organic Hair Care Market must address these trust issues to maintain credibility and long-term growth. It relies on third-party certifications and transparent communication to distinguish genuine products from misleading ones. Increased industry standardization and consumer education remain critical to overcoming misinformation and greenwashing concerns.

Market Opportunities:
Expansion in Emerging Markets with Rising Disposable Incomes
Emerging economies present a strong growth avenue for brands that offer clean-label personal care solutions. Rising awareness of wellness, urbanization, and increasing disposable incomes are encouraging consumers to shift from conventional to organic products. Localized marketing, cultural relevance, and region-specific formulations help brands connect with new audiences. The Organic Hair Care Market can grow by addressing unique hair types, climatic needs, and traditional preferences across regions. It benefits from collaborations with local distributors and influencers to build brand credibility. Targeted outreach in Tier 2 and Tier 3 cities offers untapped potential.
Innovation in Product Formats and Sustainable Packaging
There is growing consumer interest in innovative formats such as solid shampoo bars, concentrated serums, and waterless formulations. These solutions reduce packaging waste and support eco-conscious lifestyles. Brands that invest in biodegradable packaging, refillable containers, and zero-waste retail concepts gain a competitive edge. The Organic Hair Care Market stands to benefit by integrating sustainability into both formulation and packaging strategies. It appeals to environmentally aware consumers who seek ethical and convenient product experiences. Continued investment in R&D can accelerate the adoption of these forward-looking solutions.
Market Segmentation Analysis:
The Organic Hair Care Market is segmented by product type, gender, application, and sale channel, each contributing uniquely to overall market growth.
By product types, shampoos hold the largest share due to their regular use and consumer preference for chemical-free cleansing solutions. Conditioners and hair oils are gaining traction, driven by growing interest in scalp nourishment and moisture retention. Hair masks also show strong potential, particularly in premium and salon-grade categories.
- For instance, Medimix’s Total Care Shampoo, launched in May 2022 in India, is formulated with herbal and organic ingredients, directly addressing the demand for premium, natural hair care solutions.
By gender, the women’s segment dominates due to higher adoption of organic beauty routines and a wide range of product offerings. The men’s segment is expanding steadily with the rise of male grooming awareness and interest in clean-label hair care.
By application, hair nourishment and scalp care lead demand, reflecting consumer focus on long-term hair health. Hair strengthening and styling products are growing as consumers seek multifunctional and naturally derived solutions.
- For instance, CavinKare’s Nyle Natural and Pure range are formulated to address issues like dryness, frizz, and color treatment, using no-sulfate, herbal ingredients for safer, more effective results.
By sale channel, hypermarkets and supermarkets remain key contributors due to broad accessibility and product variety. Online stores are rapidly expanding their share, offering convenience and niche brand visibility. Specialty and convenience stores, along with other distribution channels, support reach in both urban and semi-urban markets. The Organic Hair Care Market adapts to shifting consumer expectations through diverse and targeted segmentation strategies.
Segmentation:
By Product Type:
- Shampoos
- Conditioners
- Hair Oils
- Hair Masks
By Gender:
- Men
- Women
By Application:
- Hair Nourishment
- Scalp Care
- Hair Strengthening
- Hair Styling
By Sale Channel:
- Hypermarkets/Supermarkets
- Specialty Stores
- Online Stores
- Convenience Stores
- Other Distribution Channels
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
The North America Organic Hair Care Market size was valued at USD 1,146.16 million in 2018 to USD 1,742.33 million in 2024 and is anticipated to reach USD 2,861.55 million by 2032, at a CAGR of 6.4% during the forecast period. North America holds a strong position in the Organic Hair are Market with the second-largest regional share. High consumer awareness, widespread clean beauty adoption, and well-developed retail infrastructure support steady growth. The market benefits from the presence of premium brands and increasing regulatory scrutiny over synthetic ingredients. Consumers in the U.S. and Canada actively seek sulfate-free, cruelty-free, and ethically sourced hair care products. It continues to expand through e-commerce and brand partnerships that target health-conscious buyers. Ongoing product innovation and demand for transparency drive further momentum in this region.
The Europe Organic Hair Care Market size was valued at USD 1,712.02 million in 2018 to USD 2,758.49 million in 2024 and is anticipated to reach USD 4,892.83 million by 2032, at a CAGR of 7.4% during the forecast period. Europe represents the second-largest share of the Organic Hair Care Market and leads in regulatory innovation. Consumers in Germany, France, and the UK demonstrate strong preferences for certified organic and environmentally friendly products. The region benefits from stringent cosmetic regulations that encourage clean labeling and sustainability. Major retailers and boutique brands alike prioritize transparency, natural ingredients, and recyclability. It responds to demand through diverse product offerings that address both performance and ecological concerns. Cultural emphasis on wellness and long-term scalp health also sustains market growth.
The Asia Pacific Organic Hair Care Market size was valued at USD 2,870.01 million in 2018 to USD 4,390.65 million in 2024 and is anticipated to reach USD 7,275.72 million by 2032, at a CAGR of 6.5% during the forecast period. Asia Pacific holds the largest market share and leads the Organic Hair Care Market in absolute value. Rapid urbanization, rising incomes, and strong cultural ties to herbal hair care support widespread adoption. Consumers in India, China, Japan, and South Korea are shifting toward wellness-focused beauty regimes. Brands leverage traditional remedies, including ayurvedic and botanical ingredients, to meet local preferences. It sees continuous growth through digital platforms and influencer-led marketing. Strong demand from both urban millennials and older consumers reinforces its regional dominance.
The Latin America Organic Hair Care Market size was valued at USD 335.83 million in 2018 to USD 550.59 million in 2024 and is anticipated to reach USD 997.37 million by 2032, at a CAGR of 7.7% during the forecast period. Latin America contributes a smaller but growing share to the Organic Hair Care Market. Brazil stands out as a regional hub, supported by its biodiversity and established beauty culture. Consumers are increasingly drawn to clean, natural formulations that incorporate native ingredients like acai and coconut. The region faces challenges in affordability and regulatory alignment but shows strong potential in urban centers. It benefits from growing wellness trends and international brand expansion. Regional manufacturers are also entering the market with competitive, locally relevant offerings.
The Middle East Organic Hair Care Market size was valued at USD 395.64 million in 2018 to USD 630.18 million in 2024 and is anticipated to reach USD 1,101.80 million by 2032, at a CAGR of 7.2% during the forecast period. The Middle East shows increasing interest in organic personal care solutions driven by rising affluence and changing lifestyle preferences. Consumers are seeking products that address dryness and damage common in hot climates. The Organic Hair Care Market in the region grows through premium positioning and retail partnerships. High demand in the UAE and Saudi Arabia is influencing regional strategies for sustainable and luxury formulations. It gains traction from growing tourism, wellness tourism, and global brand presence. Product availability through high-end retail and e-commerce channels enhances its appeal.
The Africa Organic Hair Care Market size was valued at USD 112.38 million in 2018 to USD 169.87 million in 2024 and is anticipated to reach USD 276.76 million by 2032, at a CAGR of 6.3% during the forecast period. Africa holds the smallest share in the Organic Hair Care Market but offers long-term growth potential. Local demand is rising for products that cater to natural, textured, and protective hair care routines. Urban consumers in South Africa, Nigeria, and Kenya show increasing interest in ingredient safety and scalp health. The market faces structural challenges, including limited product accessibility and low regulatory standardization. It benefits from grassroots brands focused on authenticity and community-driven solutions. International and diaspora-led ventures are also supporting gradual regional expansion.
Key Player Analysis:
- L'Oréal
- Procter & Gamble
- Unilever
- Aveda
- Weleda
- Acure Organics
- Innersense Organic Beauty
- Ceremonia
- Prose Beauty Inc.
- 100% PURE
Competitive Analysis:
The Organic Hair Care Market features a competitive landscape marked by both established global brands and agile niche players. Key companies such as Aveda, The Body Shop, Avalon Organics, and John Masters Organics focus on product transparency, eco-friendly packaging, and certified organic ingredients to maintain brand loyalty. It continues to evolve as emerging brands enter the market through direct-to-consumer models, leveraging digital marketing and influencer outreach. Competitive advantage hinges on ingredient sourcing, sustainability credentials, and formulation innovation. Larger corporations expand their portfolios through acquisitions and partnerships with smaller organic-focused brands. Product differentiation and region-specific formulations remain essential to capture diverse consumer segments.
Recent Developments:
- In April 2025, Sky Organics launched two new certified-organic hair care products designed specifically to nourish curls and promote scalp health. These additions-which include a curl-enhancing shampoo and a clarifying scalp treatment-joined the brand’s existing line and became available at Walmart stores across the United States. The launch responds to growing consumer desire for clean, targeted formulations that support both curly texture and scalp wellness
- In Sep 2024, Innersense Organic Beauty partnered with Mash Beauty Lab to enter the Japanese market. The collaboration enables Innersense products-known for their clean, plant-based formulations-to be distributed through Mash’s established retail channels across Japan. It extends brand visibility in Asia and connects with consumers who prioritize transparency and sustainability in personal care choices
- .In January 2023, Procter & Gamble acquired Mielle Organics, a textured haircare brand rooted in natural ingredients and focused on Black women’s hair care needs. The acquisition, which allows Mielle to operate as an independent subsidiary, aims to expand access to high-quality hair products for Black women globally.
Market Concentration & Characteristics:
The Organic Hair Care Market exhibits moderate market concentration, with a mix of multinational corporations and independent brands competing across global and regional segments. It remains highly fragmented due to low entry barriers and growing consumer demand for specialized, clean-label products. The market is characterized by rapid innovation, short product life cycles, and strong brand differentiation based on ingredient purity, ethical sourcing, and sustainability. Companies focus on niche marketing, product certification, and online distribution to strengthen market presence. It responds quickly to evolving consumer preferences and regulatory changes, making agility and transparency critical competitive factors.
Report Coverage:
The research report offers an in-depth analysis based on product type, gender, application, and sale channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand for clean-label, non-toxic hair care products will continue to rise across both developed and emerging markets.
- E-commerce and direct-to-consumer channels will drive market accessibility and brand expansion.
- Innovation in waterless, concentrated, and solid hair care formats will gain traction for sustainability-conscious consumers.
- Brands will increase investments in plant-based R&D and bioactive ingredient development.
- Certified organic formulations will become more prominent, driven by stricter global regulatory frameworks.
- Regional players will grow by tailoring products to local hair types, climates, and cultural preferences.
- Transparent labeling and third-party certifications will influence purchase decisions and brand trust.
- Collaborations with dermatologists and wellness professionals will enhance product credibility.
- Inclusive product lines targeting all hair textures and genders will capture broader market share.
- Eco-friendly packaging solutions and circular economy models will shape brand strategies and consumer loyalty.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Consumer Preference for Natural and Clean Beauty Solutions
Increasing awareness of the health risks associated with synthetic chemicals in hair care is pushing consumers toward organic, plant-based alternatives. This shift is reinforced by the clean beauty movement, which values transparency, non-toxic ingredients, and ethical sourcing.
Regulatory Pressure and Support for Safer Formulations
Stricter regulations and labeling requirements in major markets are compelling manufacturers to reformulate products with certified organic ingredients. Compliance with evolving safety standards enhances consumer trust and accelerates the adoption of organic hair care products.
Cultural Shift Toward Holistic and Wellness-Based Lifestyles
Consumers are integrating hair care into broader wellness routines, seeking products that offer scalp nourishment and long-term health benefits. This trend is driving demand for ayurvedic, herbal, and aromatherapy-infused organic hair care solutions.
Digital Influence and Direct-to-Consumer Brand Growth
Social media, beauty influencers, and e-commerce platforms are increasing consumer access to information and organic product options. This digital shift enables niche brands to reach wider audiences and educates consumers on ingredient safety and sustainability.
Innovation in Sustainable Packaging and Product Formats
Growing environmental awareness is prompting brands to invest in eco-friendly packaging and innovative formats like solid bars and waterless products. These sustainable solutions appeal to ethically minded consumers and differentiate brands in a competitive market.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
How COVID-19 Impacted the global Organic Hair Care market?
What are the key segments within the Organic Hair Care Market?
What are some challenges faced by the Organic Hair Care Market?
Who are the major players in the Organic Hair Care Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Gender
- 1.2.1 Men
- 1.2.2 Women
- 1.3 By Application
- 1.3.1 Hair Nourishment
- 1.3.2 Scalp Care
- 1.3.3 Hair Strengthening
- 1.3.4 Hair Styling
- 1.4 By Product Type
- 1.4.1 Shampoos
- 1.4.2 Conditioners
- 1.4.3 Hair Oils
- 1.4.4 Hair Masks
- 1.5 By Sale Channel
- 1.5.1 Hypermarkets/Supermarkets
- 1.5.2 Specialty Stores
- 1.5.3 Online Stores
- 1.5.4 Convenience Stores
- 1.5.5 Other Distribution Channels
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 10,242.1 million → 2032: USD 17,406.0 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Organic Hair Care Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Organic Hair Care Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Organic Hair Care Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Organic Hair Care Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Organic Hair Care Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Organic Hair Care Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Organic Hair Care Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Organic Hair Care Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 10,242.1 million → 2032: USD 17,406.0 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Organic Hair Care Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Gender - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Men
- 12.3.7.2 Women
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Hair Nourishment
- 12.4.7.2 Scalp Care
- 12.4.7.3 Hair Strengthening
- 12.4.7.4 Hair Styling
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Shampoos
- 12.5.7.2 Conditioners
- 12.5.7.3 Hair Oils
- 12.5.7.4 Hair Masks
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Sale Channel - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Hypermarkets/Supermarkets
- 12.6.7.2 Specialty Stores
- 12.6.7.3 Online Stores
- 12.6.7.4 Convenience Stores
- 12.6.7.5 Other Distribution Channels
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Organic Hair Care End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Organic Hair Care Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Organic Hair Care Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Organic Hair Care Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 L'Oréal
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Procter & Gamble
- 18.4 Unilever
- 18.5 Aveda
- 18.6 Weleda
- 18.7 Acure Organics
- 18.8 Innersense Organic Beauty
- 18.9 Ceremonia
- 18.10 Prose Beauty Inc.
- 18.11 100% PURE
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

