
Market Overview
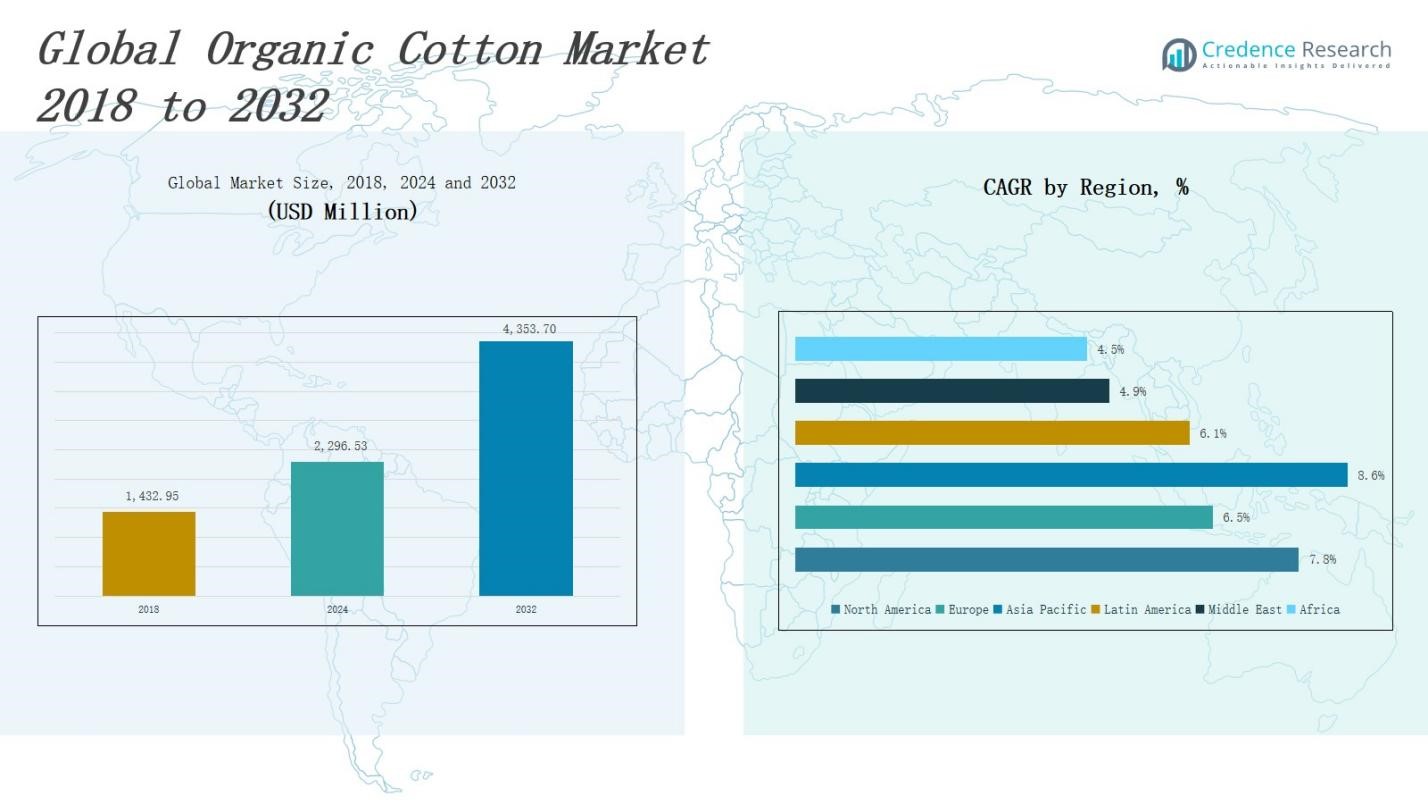
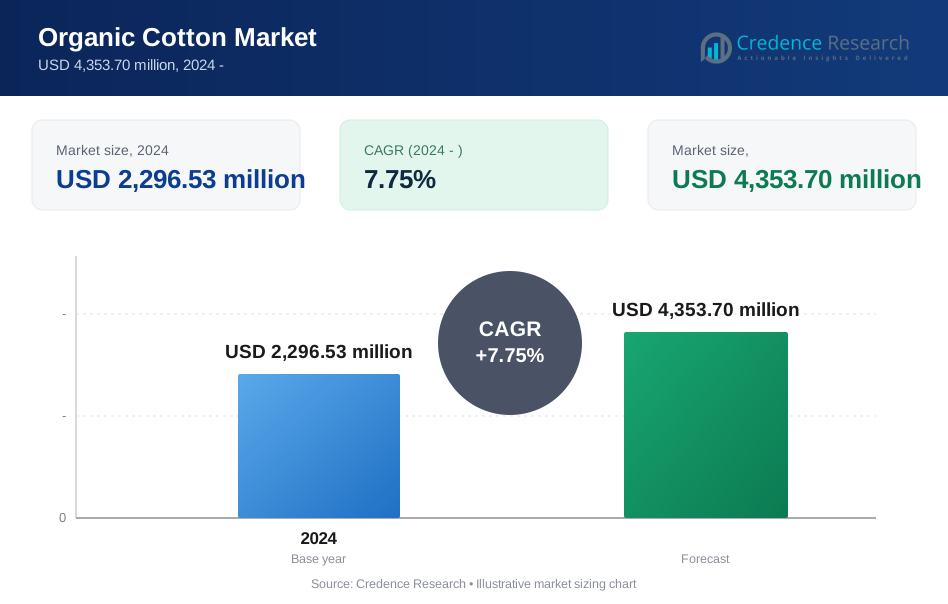
The Organic Cotton Market size was valued at USD 1,432.95 million in 2018 to USD 2,296.53 million in 2024 and is anticipated to reach USD 4,353.70 million by 2032, at a CAGR of 7.75% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Organic Cotton Market Size 2024 | USD 2,296.53 Million |
| Organic Cotton Market , CAGR | 7.75% |
| Organic Cotton Market Size 2032 | USD 4,353.70 Million |
The Organic Cotton Market is driven by rising consumer demand for sustainable and chemical-free textiles, supported by increasing awareness of environmental and health concerns. Stringent regulations on synthetic pesticides and growing adoption of eco-friendly farming practices further stimulate market expansion. Brands prioritize traceability and ethical sourcing, aligning with corporate sustainability goals. Key trends include the integration of blockchain for supply chain transparency, expansion of certified organic cotton cultivation, and growing use in athleisure, baby wear, and home textiles. E-commerce platforms and sustainable fashion movements accelerate consumer engagement, reshaping the global textile industry toward organic and socially responsible alternatives.
The Organic Cotton Market spans North America, Europe, Asia Pacific, Latin America, the Middle East, and Africa, with Asia Pacific holding the largest share due to strong production in India and China. North America and Europe follow, driven by high consumer awareness and sustainable fashion demand. Latin America, the Middle East, and Africa show steady growth supported by expanding cultivation and imports. Key players in the market include Cargill, Olam International, Dunavant Enterprises, Bombay Hemp Company, Louis Dreyfus Company, Texhong Textile Group, Organic Cotton Colours, Cotton Connect, and Numi Organic Tea.
Market Insights
- The Organic Cotton Market was valued at USD 1,432.95 million in 2018 and is projected to reach USD 4,353.70 million by 2032, growing at a CAGR of 7.75%.
- Rising demand for chemical-free textiles, especially in babywear, intimate apparel, and home textiles, is accelerating market growth globally.
- Government regulations and certifications such as GOTS enhance market credibility and drive adoption across supply chains.
- Asia Pacific leads the market with over 35% share due to large-scale cultivation in India and China and rising domestic consumption.
- High production costs, lower yields, and complex certification requirements challenge scalability and profitability for small producers.
- North America and Europe collectively hold over 45% of the global share, driven by strong consumer awareness and corporate sustainability commitments.
- Key players include Cargill, Olam International, Dunavant Enterprises, Bombay Hemp Company, Organic Cotton Colours, Louis Dreyfus Company, and Cotton Connect.
Market Drivers
Rising Consumer Demand for Sustainable and Chemical-Free Textiles
The Organic Cotton Market is gaining momentum due to increasing consumer preference for eco-friendly and non-toxic textiles. Shoppers seek alternatives free from harmful chemicals and pesticides, especially in baby clothing, intimate wear, and daily apparel. Awareness about allergic reactions and skin sensitivities is driving demand. Consumers are becoming more informed about environmental degradation linked to conventional cotton farming. It prompts brands to switch to organic sources. Retailers are expanding sustainable collections to capture this segment.
- For instance, Pact produces basics and activewear made almost entirely from certified organic cotton, with their processes reported to use 81% less water and 62% less energy compared to conventional methods.
- For instance, the Indian government’s Paramparagat Krishi Vikas Yojana program promotes organic farming through subsidies and technical support, helping increase organic cotton cultivation in the country.
Corporate Sustainability Goals and Ethical Sourcing Practices
The Organic Cotton Market aligns well with corporate sustainability targets across the apparel industry. Brands are integrating responsible sourcing policies to meet ESG commitments. Ethical concerns surrounding labor conditions in conventional cotton supply chains also drive change. Companies prioritize organic cotton to ensure social compliance and environmental stewardship. It supports long-term brand equity and consumer loyalty. Sustainable sourcing has become central to strategic planning for fashion and lifestyle brands.
Technological Advancements and Supply Chain Transparency Initiatives
The Organic Cotton Market is advancing through improved supply chain visibility and digital tools. Blockchain integration enables end-to-end traceability, ensuring product authenticity. Digital platforms streamline certification tracking and audit processes. It allows brands to validate sourcing claims and promote transparency to conscious consumers. Technology adoption also reduces fraud and builds accountability. These advancements support growth and help meet rising global demand for verified organic cotton products.
Market Trends
Growing Integration of Organic Cotton in Fashion and Lifestyle Brands
The Organic Cotton Market is witnessing rising adoption by mainstream and premium fashion brands integrating sustainability into their core collections. Leading labels are expanding their organic cotton offerings in athleisure, denim, and everyday basics to meet evolving consumer expectations. This shift reflects growing alignment with ethical fashion trends. It encourages design innovation using natural fibers without compromising style. Major retailers now feature dedicated organic lines. Demand from both luxury and fast fashion segments supports widespread market expansion.
- For instance, Adidas has committed to using 100% sustainable cotton, including organic cotton, across all its products by 2025, and is publicly tracking its progress through international platforms.
Increased Focus on Circular Economy and Closed-Loop Practices
The Organic Cotton Market is being reshaped by circular economy principles. Brands are emphasizing recyclability, reusability, and biodegradable product life cycles. Organic cotton aligns naturally with these goals due to its minimal chemical processing and lower environmental footprint. It supports closed-loop systems that reduce textile waste and resource consumption. Retailers and manufacturers are introducing take-back programs and upcycled collections. Consumer preference for sustainable disposal options is accelerating circular adoption in textile sourcing strategies.
- For instance, H&M has implemented global in-store take-back programs that collect used clothing-including items made from organic cotton-which are then sorted for resale, recycling, or upcycling into new textile products, supporting closed-loop systems and reducing textile waste.
Technological Enablement for Supply Chain Traceability and Verification
The Organic Cotton Market is evolving through the deployment of blockchain and digital tools that enhance transparency across the value chain. These technologies verify organic credentials, document every production step, and strengthen trust among stakeholders. It helps eliminate greenwashing and counters fraudulent claims. Brands using traceability solutions increase consumer confidence and meet compliance mandates. Real-time data monitoring and automated certification processes are driving efficiency. Such systems create a reliable and scalable organic supply framework.
Expansion of Organic Cotton Cultivation in Emerging Economies
The Organic Cotton Market is expanding with increased cultivation efforts in regions like India, Turkey, and parts of Africa. Farmers are shifting to organic methods due to better long-term soil health, market premiums, and access to global buyers. Training programs and NGO support assist in this transition. It strengthens the supply base and reduces dependency on synthetic inputs. Rising demand from export markets creates strong incentives for sustainable agricultural adoption. Regional initiatives improve supply chain resilience.
Market Challenges Analysis
High Production Costs and Limited Yield Impact Profitability
The Organic Cotton Market faces significant pressure from high cultivation costs and comparatively lower yields. Organic farming requires more labor, longer crop cycles, and strict compliance with certification standards. These factors increase production expenses and reduce profitability for farmers and suppliers. It challenges scalability and discourages smallholders from transitioning to organic practices. Price-sensitive markets often resist premium pricing, limiting broader adoption. Brands struggle to balance cost-efficiency with sustainable sourcing goals in competitive retail environments.
Certification Complexity and Supply Chain Inconsistencies
The Organic Cotton Market is constrained by complex certification processes and inconsistent supply chain infrastructure. Obtaining and maintaining certifications such as GOTS or OE100 involves time-consuming audits, documentation, and compliance checks. It creates entry barriers for small-scale producers. Disruptions in logistics, limited ginning capacity, and fragmented supply networks further affect traceability and quality control. These gaps increase the risk of contamination with conventional cotton. Brands face reputational risks if they cannot guarantee authenticity throughout sourcing.
Market Opportunities
Rising Demand for Sustainable Fashion in Emerging Markets
The Organic Cotton Market presents strong growth potential in emerging economies with expanding middle-class populations and increasing environmental awareness. Consumers in regions such as Asia-Pacific and Latin America are beginning to prioritize eco-friendly fashion choices. Brands can capture this shift by offering affordable organic cotton products tailored to local preferences. It enables retailers to enter untapped markets with high volume potential. Government programs supporting sustainable agriculture further strengthen regional adoption. Local sourcing can also reduce costs and enhance supply resilience.
Innovation in Blended Fabrics and Functional Applications
The Organic Cotton Market offers opportunities through product innovation and diversified applications. Blending organic cotton with other sustainable fibers, such as hemp or bamboo, creates functional fabrics with improved durability, softness, and moisture management. It opens doors for use in activewear, home textiles, and medical apparel. Brands can differentiate through unique fabric compositions that align with consumer expectations for both performance and sustainability. Advances in textile processing and dyeing technologies enhance value-added offerings. Niche markets seeking organic-certified uniforms and institutional wear remain underexplored.
Market Segmentation Analysis:
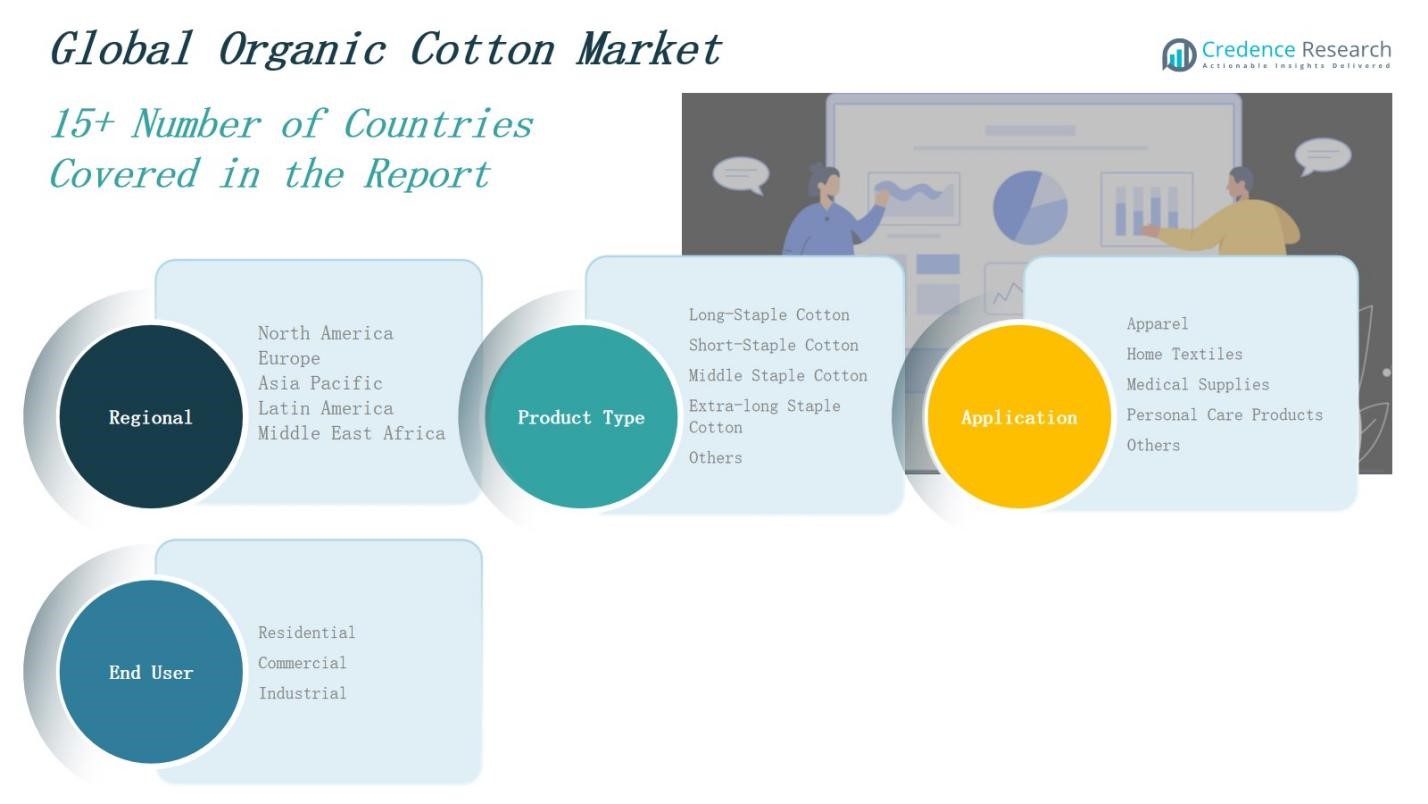
By Product Type
The Organic Cotton Market segments by product type into long-staple cotton, short-staple cotton, middle staple cotton, extra-long staple cotton, and others. Long-staple and extra-long staple cotton dominate due to their superior fiber strength, softness, and durability, which are ideal for premium textiles and apparel. Short-staple and middle staple cotton remain in use for basic garments and household products. It supports diverse manufacturing needs across quality tiers, sustaining volume and value growth in multiple textile segments.
- For instance, in India, the Suvin variety of long-staple cotton, cultivated mainly in Tamil Nadu, is prized for its quality and widely used in high-end textile production, supported by government initiatives to enhance fiber quality.
By Application
The Organic Cotton Market classifies applications into apparel, home textiles, medical supplies, personal care products, and others. Apparel holds the largest share, driven by growing demand for sustainable clothing from eco-conscious consumers and fashion brands. Home textiles follow closely, supported by rising organic bedding and towel preferences. It also finds adoption in personal care and medical segments where skin sensitivity and chemical-free materials are essential. Emerging uses continue to broaden application potential.
- For example, companies like Welspun Group and Springs Global have introduced organic cotton bedding collections catering to environmentally conscious buyers.
By End User
The Organic Cotton Market segments by end user into residential, commercial, and industrial categories. The residential segment leads, with consumers actively choosing organic cotton for clothing, home linens, and hygiene products. The commercial sector includes hotels and wellness centers prioritizing eco-friendly textiles. It gains traction in the industrial segment through demand for uniforms and workwear made from sustainable fabrics. The expanding use across these sectors strengthens overall market penetration and adoption.
Segments:
Based on Product Type
- Long-Staple Cotton
- Short-Staple Cotton
- Middle Staple Cotton
- Extra-long Staple Cotton
- Others
Based on Application:
- Apparel
- Home Textiles
- Medical Supplies
- Personal Care Products
- Others
Based on End User:
- Residential
- Commercial
- Industrial
Based on Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
The North America Organic Cotton Market size was valued at USD 424.49 million in 2018 to USD 669.90 million in 2024 and is anticipated to reach USD 1,275.19 million by 2032, at a CAGR of 7.8% during the forecast period. North America holds a significant share of the global market due to early adoption of sustainable fashion and strong demand for certified organic products. Major brands in the U.S. and Canada promote transparency and ethical sourcing. It benefits from robust retail infrastructure and advanced supply chain systems. Increasing awareness around environmental impact and consumer health fuels product uptake. Regional regulations and certifications ensure high product standards and traceability. North America contributes over 25% of the global market share.
Europe
The Europe Organic Cotton Market size was valued at USD 267.02 million in 2018 to USD 404.45 million in 2024 and is anticipated to reach USD 697.08 million by 2032, at a CAGR of 6.5% during the forecast period. Europe ranks as the second-largest market, driven by strong regulatory frameworks and environmental consciousness. Fashion retailers across Germany, France, and the UK integrate organic cotton into mainstream and luxury lines. It benefits from initiatives promoting circular fashion and ethical consumerism. Demand for organic home textiles and personal care items continues to rise. Government incentives and NGO partnerships support sustainable farming. Europe holds nearly 20% of the global market share.
Asia Pacific
The Asia Pacific Organic Cotton Market size was valued at USD 619.61 million in 2018 to USD 1,030.08 million in 2024 and is anticipated to reach USD 2,073.12 million by 2032, at a CAGR of 8.6% during the forecast period. Asia Pacific dominates the global market, accounting for the largest share due to its role as a major producer and exporter. Countries like India, China, and Turkey lead organic cotton cultivation. It benefits from low production costs and increasing domestic consumption. Local and international brands expand organic offerings to meet rising consumer demand. Government schemes support sustainable agriculture and rural livelihoods. Asia Pacific contributes over 35% of the global market share.
Latin America
The Latin America Organic Cotton Market size was valued at USD 67.68 million in 2018 to USD 107.12 million in 2024 and is anticipated to reach USD 179.73 million by 2032, at a CAGR of 6.1% during the forecast period. Latin America shows steady growth, supported by Brazil and Argentina’s organic farming expansion. Regional awareness about environmental sustainability and export opportunities drives cultivation. It experiences growing demand from regional fashion and textile industries. Cross-border trade and global certifications strengthen international market access. Infrastructure development and government backing enhance supply efficiency. Latin America represents around 5% of global market share.
Middle East
The Middle East Organic Cotton Market size was valued at USD 33.13 million in 2018 to USD 47.57 million in 2024 and is anticipated to reach USD 72.77 million by 2032, at a CAGR of 4.9% during the forecast period. The region has limited cultivation but growing demand for imported organic textiles. UAE and Saudi Arabia lead in luxury apparel consumption with interest in sustainable alternatives. It sees moderate adoption driven by retail diversification and sustainability goals. E-commerce platforms enhance consumer access to organic cotton goods. Strategic imports from Asia and Europe meet quality requirements. The Middle East holds under 3% of the global market share.
Africa The Africa Organic Cotton Market size was valued at USD 21.03 million in 2018 to USD 37.43 million in 2024 and is anticipated to reach USD 55.80 million by 2032, at a CAGR of 4.5% during the forecast period. Africa has untapped potential as both a producer and consumer. Countries like Tanzania, Uganda, and Benin engage in organic cotton farming with NGO and international support. It faces infrastructure and certification challenges but benefits from fertile land and low input dependency. Export-oriented cultivation supports European and Asian supply chains. Local awareness is growing through educational programs. Africa accounts for less than 2% of global market share but holds high growth potential.
Key Player Analysis
- Bombay Hemp Company
- Dunavant Enterprises, Inc.
- Organic Cotton Colours
- Numi Organic Tea
- Cargill, Inc.
- Louis Dreyfus Company
- Allenberg Cotton Company
- Olam International
- Texhong Textile Group Limited
- Cotton Connect
Competitive Analysis
The Organic Cotton Market features a competitive landscape marked by vertically integrated players and strategic collaborations across farming, processing, and retail. Key companies such as Cargill, Dunavant Enterprises, Olam International, and Louis Dreyfus Company leverage global sourcing networks and strong supply chain control. Emerging players like Bombay Hemp Company and Organic Cotton Colours focus on innovation, traceability, and eco-certifications to gain market share. It reflects high entry barriers due to certification complexity and sourcing challenges. Companies invest in sustainable farming programs, farmer training, and digital traceability tools to enhance transparency. Partnerships with fashion brands and retailers help expand end-user reach. The market also sees competition from regional suppliers that cater to niche organic textile applications. Product differentiation, quality consistency, and brand positioning remain essential for maintaining a competitive edge. The Organic Cotton Market continues to attract new entrants aligned with ethical fashion trends and sustainability-driven consumer expectations.
Recent Developments
- In May 2023, Indigo Ag announced it delivered 31,000 bales of sustainably grown cotton under its Market+Source Scope 3 program to VF Corporation and other apparel brands.
- In May 2025, the Organic Cotton Accelerator (OCA) expanded its Farm Programme to support over 100,000 farmers and published a Life Cycle Assessment highlighting the environmental benefits of organic cotton cultivation in India.
- On April 1, 2025, OEKO-TEX® implemented new regulations, including the introduction of the STANDARD 100 ORGANIC COTTON certification and stricter chemical screening protocols to ensure product safety and traceability.
- In December 2024, Haelixa entered a three-year agreement with C&A to implement DNA-based markers for tracing organic cotton. This partnership enables full supply chain verification from farm to finished garment using forensic-level PCR testing.
Market Concentration & Characteristics
The Organic Cotton Market shows moderate to high market concentration, with a mix of multinational corporations and regionally integrated suppliers controlling significant portions of global production and trade. Major players such as Cargill, Olam International, and Dunavant Enterprises maintain strong upstream networks and direct sourcing relationships with certified farms. The market is characterized by long certification cycles, limited scalability, and high traceability requirements, which create entry barriers for small producers. It relies on consistent quality standards and ethical compliance, making supplier partnerships and audit capabilities critical. Product differentiation is based on fiber quality, sustainability certifications, and supply chain transparency. Demand is largely driven by apparel, but diversified use in home textiles and personal care adds resilience. The Organic Cotton Market operates under strong regulatory oversight and consumer scrutiny, reinforcing the importance of credibility, documentation, and environmental stewardship. Retailer-brand collaborations and technological tools shape procurement strategies and long-term supply security.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Application, End-User and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for organic cotton will grow due to increased consumer focus on sustainability and skin-friendly textiles.
- Fashion brands will expand organic cotton collections to meet ethical sourcing goals.
- Certified farming practices will gain more adoption across emerging economies.
- Blockchain and digital traceability tools will enhance supply chain transparency.
- Government incentives and NGO partnerships will support organic farming initiatives.
- Retailers will strengthen collaborations with certified suppliers to ensure quality and compliance.
- Use of organic cotton in home textiles and personal care will expand steadily.
- Challenges in yield and cost efficiency will prompt innovation in cultivation methods.
- Regional sourcing strategies will reduce dependency on single-country production.
- E-commerce growth will increase access to organic cotton products across global markets.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Consumer Preference for Sustainable and Chemical-Free Textiles
Growing awareness of environmental and health impacts associated with conventional cotton is driving consumers to seek organic alternatives, especially in sensitive categories like babywear, intimate apparel, and home textiles. This shift is prompting brands and retailers to expand their organic cotton offerings to capture eco-conscious market segments.
Stringent Regulations and Certification Standards
Government policies restricting synthetic pesticide use and the proliferation of certifications such as GOTS are boosting market credibility and adoption. These standards ensure product integrity, increase buyer confidence, and provide a competitive edge to brands that comply, further accelerating organic cotton uptake.
Corporate Sustainability and Ethical Sourcing Initiatives
Major apparel and textile brands are integrating organic cotton into their supply chains to meet ESG commitments and address ethical concerns related to labor and environmental stewardship. This alignment with corporate sustainability goals is driving large-scale adoption and long-term market growth.
Technological Advancements in Supply Chain Transparency
The integration of blockchain and digital traceability tools is enhancing supply chain visibility, enabling brands to verify sourcing claims and build consumer trust. These technologies help eliminate fraud, ensure compliance, and support the scaling of organic cotton supply networks.
Expansion of Organic Cotton Cultivation in Emerging Economies
Supportive government programs, NGO initiatives, and market premiums are encouraging farmers in countries like India, Turkey, and parts of Africa to transition to organic cotton. This expansion strengthens the global supply base and meets rising demand from both domestic and export markets.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Organic Cotton Market?
What factors are driving the growth of the Organic Cotton Market?
What are the key segments within the Organic Cotton Market?
What are some challenges faced by the Organic Cotton Market?
Who are the major players in the Organic Cotton Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Residential
- 1.2.2 Commercial
- 1.2.3 Industrial
- 1.3 By Application
- 1.3.1 Apparel
- 1.3.2 Home Textiles
- 1.3.3 Medical Supplies
- 1.3.4 Personal Care Products
- 1.3.5 Others
- 1.4 By Product Type
- 1.4.1 Long-Staple Cotton
- 1.4.2 Short-Staple Cotton
- 1.4.3 Middle Staple Cotton
- 1.4.4 Extra-long Staple Cotton
- 1.4.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2,296.53 million → 2032: USD 4,353.70 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Organic Cotton Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Organic Cotton Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Organic Cotton Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Organic Cotton Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Organic Cotton Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Organic Cotton Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Organic Cotton Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Organic Cotton Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2,296.53 million → 2032: USD 4,353.70 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Organic Cotton Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Residential
- 12.3.7.2 Commercial
- 12.3.7.3 Industrial
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Apparel
- 12.4.7.2 Home Textiles
- 12.4.7.3 Medical Supplies
- 12.4.7.4 Personal Care Products
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Long-Staple Cotton
- 12.5.7.2 Short-Staple Cotton
- 12.5.7.3 Middle Staple Cotton
- 12.5.7.4 Extra-long Staple Cotton
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Organic Cotton End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Organic Cotton Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Organic Cotton Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Organic Cotton Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Cargill, Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Olam International
- 18.4 Dunavant Enterprises, Inc.
- 18.5 Bombay Hemp Company
- 18.6 Louis Dreyfus Company
- 18.7 Texhong Textile Group Limited
- 18.8 Organic Cotton Colours
- 18.9 Cotton Connect
- 18.10 Numi Organic Tea
- 18.11 Allenberg Cotton Company
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

