
Market Overview
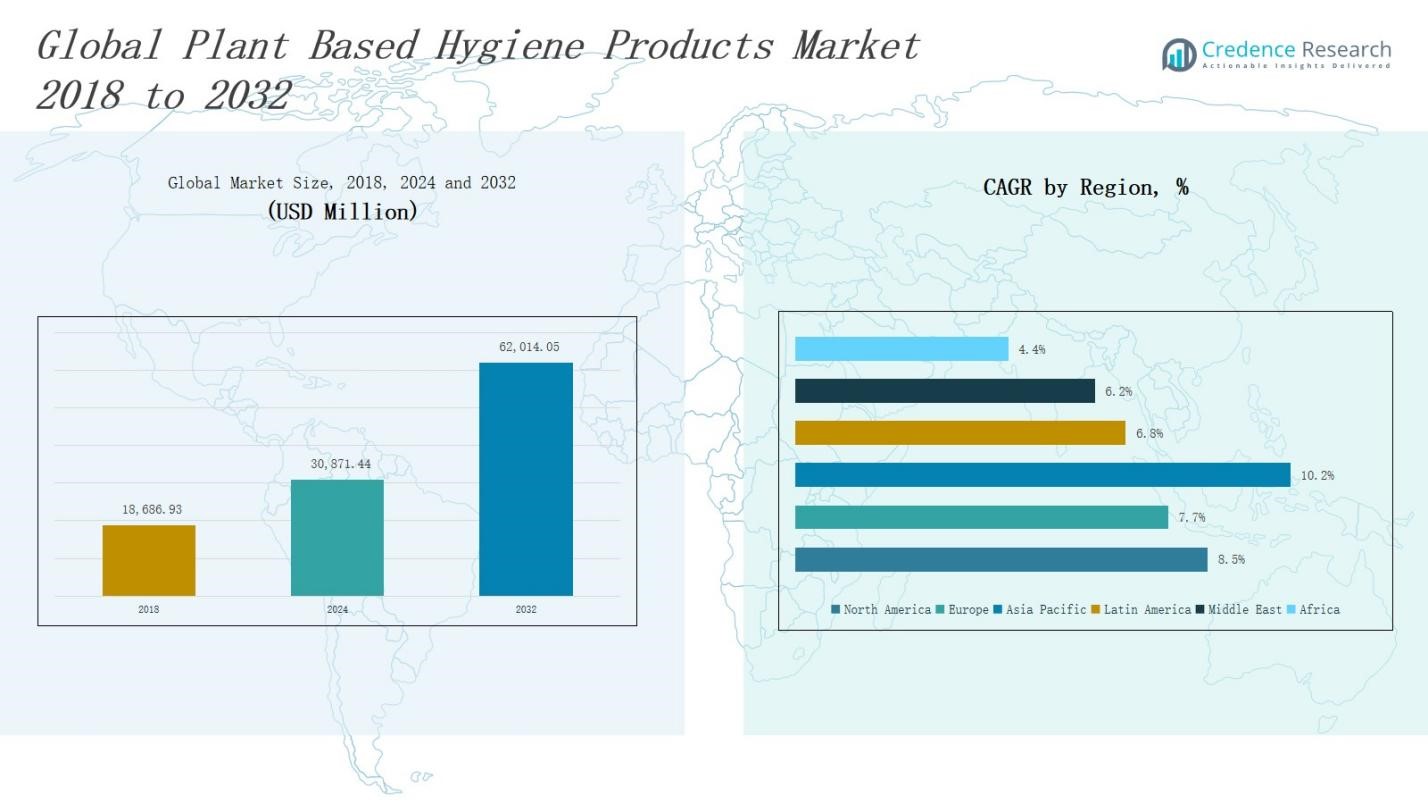
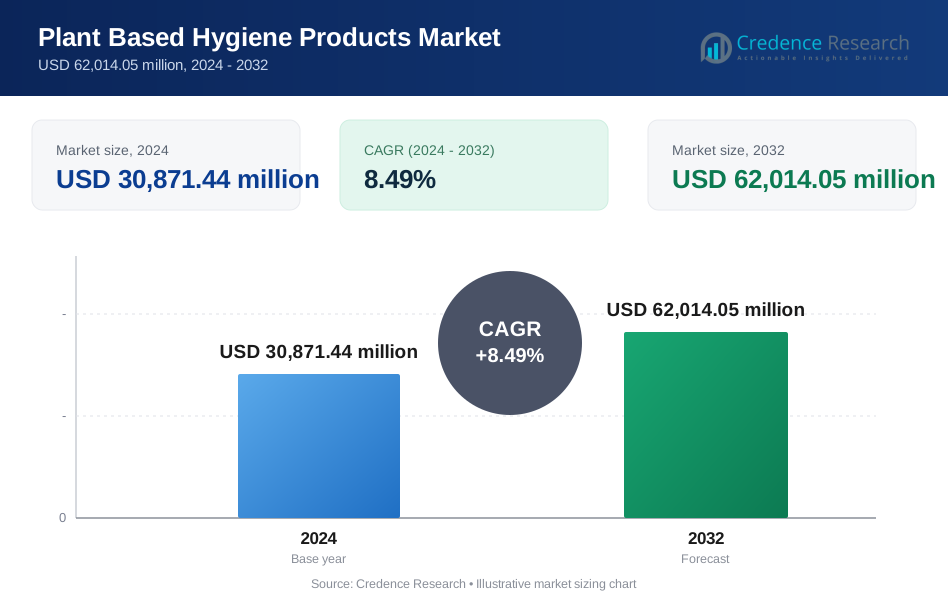
The Plant Based Hygiene Products Market size was valued at USD 18,686.93 million in 2018 to USD 30,871.44 million in 2024 and is anticipated to reach USD 62,014.05 million by 2032, at a CAGR of 8.49% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Plant Based Hygiene Products Market Size 2024 | USD 30,871.44 Million |
| Plant Based Hygiene Products Market , CAGR | 8.49% |
| Plant Based Hygiene Products Market Size 2032 | USD 62,014.05 Million |
The Plant-Based Hygiene Products Market is driven braising consumer demand for sustainable, chemical-free personal care solutions and increasing awareness of environmental impact. Shifting preferences toward organic and biodegradable materials support rapid adoption across feminine hygiene, baby care, and personal cleansing segments. Government regulations promoting eco-friendly products and corporate ESG commitments further stimulate innovation. Market trends include the integration of compostable packaging, use of plant-derived fibers such as bamboo and cotton, and expansion of gender-neutral and inclusive product lines. E-commerce platforms and social media influence accelerate product visibility and consumer engagement, driving continued market expansion and brand differentiation.
The Plant Based Hygiene Products Market spans key regions including North America, Europe, Asia Pacific, Latin America, the Middle East, and Africa. North America holds the largest share, while Asia Pacific shows the fastest growth. Europe remains strong with strict eco-regulations, and Latin America, the Middle East, and Africa present emerging opportunities. Major players include Saathi, Natracare, Bamboo Babe, Rael, LOLA, Organyc, Cora, Heyday, Pinkie, and Tsuno. These companies drive market expansion through sustainable innovation, inclusive design, and strong retail and e-commerce presence across global and regional markets.
Market Insights
- The Plant Based Hygiene Products Market was valued at USD 18,686.93 million in 2018 and is projected to reach USD 62,014.05 million by 2032, growing at a CAGR of 8.49%.
- Consumer demand for sustainable, chemical-free hygiene solutions drives growth across feminine hygiene, baby care, and personal cleansing categories.
- Brands leverage compostable packaging, bamboo and cotton fibers, and gender-neutral products to meet evolving preferences.
- North America leads the market with over 35% share, followed by Europe and Asia Pacific, which shows the fastest growth at a 10.2% CAGR.
- High production costs, limited shelf life, and performance concerns challenge market adoption, especially in price-sensitive regions.
- E-commerce, influencer marketing, and direct-to-consumer models expand reach for both emerging and established brands globally.
- Key players include Saathi, Natracare, Bamboo Babe, Rael, LOLA, Organyc, Cora, Heyday, Pinkie, and Tsuno, driving innovation and ethical practices across global regions.
Market Drivers
Rising Consumer Preference for Sustainable and Chemical-Free Alternatives
The Plant Based Hygiene Products Market is primarily driven by increasing consumer awareness of health and environmental concerns. Individuals actively seek products free from harsh chemicals, parabens, and synthetic fragrances. This shift toward natural, plant-derived ingredients reflects a broader demand for sustainable living. It supports brands offering biodegradable and non-toxic hygiene solutions. The market benefits from consumers’ willingness to pay a premium for cleaner labels. It continues to attract health-conscious and eco-aware demographics.
For instance, True Botanicals uses organic and wildcrafted plant ingredients—such as chebula and algae extract—in all of its anti-aging oils and serums. The brand is MADE SAFE certified, vegan, and sources ingredients responsibly to meet demand for health- and eco-conscious skincare.
Growing Environmental Regulations and Green Certifications
Government regulations and international guidelines play a critical role in shaping the Plant Based Hygiene Products Market. Regulatory bodies enforce bans and restrictions on harmful chemicals in personal care products. It compels manufacturers to reformulate with safer, plant-based inputs. Certifications like USDA Organic, ECOCERT, and cruelty-free seals further influence purchase behavior. These standards validate product claims and build trust with consumers. It helps market players align with evolving sustainability mandates.
Innovation in Biodegradable Packaging and Materials
Advancements in eco-friendly materials and packaging innovation support the expansion of the Plant Based Hygiene Products Market. Companies develop compostable wrappers, refill systems, and biodegradable absorbents made from bamboo, organic cotton, and corn starch. It aligns with global efforts to reduce landfill waste and microplastic pollution. Consumers increasingly favor brands with plastic-free and low-impact designs. It encourages new product formats and sustainable packaging solutions. Market leaders invest in R&D to meet these expectations.
For instance, futuralga, a Spanish company that creates AlgaEcopack, a biodegradable tray made from macroalgae (seaweed) that replaces polystyrene trays for fruits and vegetables, fully compostable and renewable.
Evolving Retail Channels and Influencer-Driven Demand
Digital transformation and influencer marketing accelerate visibility for plant-based hygiene products. The Plant Based Hygiene Products Market gains traction through social platforms, online reviews, and direct-to-consumer models. E-commerce enables access to niche and premium offerings beyond traditional retail. It allows small and emerging brands to compete with established players. Influencers promote product transparency and eco-values. This engagement builds brand loyalty and supports continued market growth across global consumer segments.
Market Trends
Adoption of Biodegradable and Plastic-Free Packaging Solutions
Brands in the Plant Based Hygiene Products Market increasingly shift toward biodegradable, compostable, and plastic-free packaging formats. It reflects growing consumer and regulatory pressure to minimize single-use plastics and landfill waste. Packaging made from materials like sugarcane fiber, cornstarch, and recycled paper sees rising demand. Companies aim to offer fully sustainable products by aligning packaging with natural product ingredients. It strengthens brand positioning among eco-conscious buyers. Retailers also promote such offerings on sustainability-driven shelves.
For instance, Yumi juices use 100% biodegradable vegetable-based bottles for their High Pressure Processed juices, combining health goals with environmental responsibility.
Expansion of Gender-Neutral and Inclusive Hygiene Products
The Plant Based Hygiene Products Market witnesses strong momentum from brands launching gender-neutral and inclusive hygiene lines. Companies develop products that cater to diverse gender identities, body types, and skin sensitivities. It reflects a broader social shift toward inclusive personal care. Labels avoid gendered language and offer neutral designs and scents. It helps break stereotypes and improve market accessibility. Inclusive innovation expands the market reach and aligns with changing consumer values.
For instance, Vuokkoset is releasing a fully gender-neutral ‘For Menstruation’ product line with pads and liners designed to be inclusive of all genders, further broadening the conversation on menstrual diversity.
Growing Use of Organic and Functional Botanicals
Functional botanicals such as aloe vera, witch hazel, chamomile, and tea tree oil are gaining ground in plant-based hygiene formulations. The Plant Based Hygiene Products Market uses these ingredients for their antimicrobial, soothing, and healing properties. Brands highlight their use in marketing claims to build trust and support health-conscious buying decisions. It supports differentiation in a competitive space. Product lines now emphasize therapeutic value along with sustainability. This trend drives both premiumization and consumer loyalty.
Rise of Direct-to-Consumer Brands and E-Commerce Innovation
E-commerce platforms, subscription services, and social commerce are transforming the Plant Based Hygiene Products Market. It enables direct engagement with consumers and supports data-driven personalization. DTC brands leverage digital content, influencer reviews, and sustainable narratives to build loyal communities. Online-first companies scale quickly by bypassing traditional retail. It also helps smaller players enter the market with lower barriers. The shift to online sales supports innovation and speeds up product feedback cycles.
Market Challenges Analysis
High Production Costs and Price Sensitivity Among Consumers
The Plant Based Hygiene Products Market faces challenges due to high production costs associated with organic ingredients, sustainable materials, and eco-friendly packaging. It often leads to higher retail prices compared to conventional hygiene products. This cost disparity limits adoption in price-sensitive markets and among low-income consumers. Manufacturers struggle to balance quality, certification requirements, and affordability. Economies of scale remain difficult for small and mid-sized brands. It affects their competitiveness against larger mainstream players.
Limited Shelf Life and Performance Perception Issues
Plant-based formulations sometimes suffer from limited shelf life due to the absence of synthetic preservatives. The Plant Based Hygiene Products Market must address concerns over product stability and long-term usability. Consumers may question the performance of natural ingredients compared to chemical-based alternatives. It creates skepticism in categories like deodorants, wet wipes, and feminine care. Brands must invest in education and transparent labeling to overcome doubts. Misconceptions about efficacy hinder widespread consumer acceptance.
Market Opportunities
Expansion into Emerging Markets with Growing Eco-Conscious Demographics
The Plant Based Hygiene Products Market presents strong opportunities in emerging economies where awareness of sustainable living is rising. Urbanization, higher disposable income, and digital access drive interest in natural and chemical-free hygiene solutions. It enables brands to tap into a young, health-conscious population seeking safe and ethical alternatives. Governments support green initiatives, creating a favorable regulatory environment. Companies offering affordable plant-based products can establish early brand loyalty. Local partnerships and education campaigns further expand market penetration.
Product Diversification Across Niche and Underserved Categories
Opportunities exist to diversify product portfolios across underserved segments like senior care, postnatal hygiene, and intimate wellness. The Plant Based Hygiene Products Market can expand by developing targeted solutions using safe, plant-derived ingredients. Brands introducing innovative formats such as reusable pads, dry shampoos, or zero-waste options meet evolving consumer preferences. It encourages premiumization while promoting sustainability. Technological advancements in formulation and preservation enable greater variety without compromising quality. Customized offerings aligned with lifestyle values strengthen brand engagement.
Market Segmentation Analysis:
By Product Type
The Plant Based Hygiene Products Market includes a wide range of offerings tailored to consumer needs. Plant-based sanitary pads and tampons hold the largest share due to strong demand for eco-friendly menstrual care. Plant-based diapers and wipes show fast growth, driven by rising preference for natural baby care. Panty liners, body cleansers, and soaps appeal to consumers seeking gentle, biodegradable options. It also includes niche categories under “Others” gaining traction in specialty retail.
For instance, Saathi produces sanitary pads using bamboo and banana fibers, creating biodegradable options that avoid synthetic chemicals while supporting menstrual health initiatives in India.
By Ingredient
Key ingredients driving innovation in the Plant Based Hygiene Products Market include plant fibers, essential oils, plant-derived surfactants, and natural fragrances. Plant fibers such as bamboo and organic cotton dominate due to their absorbency and biodegradability. Essential oils offer antimicrobial and soothing benefits, especially in feminine hygiene and cleansing products. Plant-derived surfactants and enzymes support natural foaming and cleansing actions. It reflects consumer preference for functional yet safe hygiene formulations.
For example, Cora incorporates coconut-derived surfactants and essential oils like lavender and chamomile in its feminine hygiene products to provide natural antimicrobial benefits and skin-soothing effects.
By Application
The Plant Based Hygiene Products Market segments its application into feminine hygiene, baby care, personal cleansing, and others. Feminine hygiene leads the segment due to rising adoption of natural menstrual care products. Baby care products gain popularity among parents seeking toxin-free, skin-safe alternatives. Personal cleansing sees strong demand for plant-based body washes and intimate care solutions. It also includes emerging uses in senior care and wellness categories under the “Others” segment.
Segments:
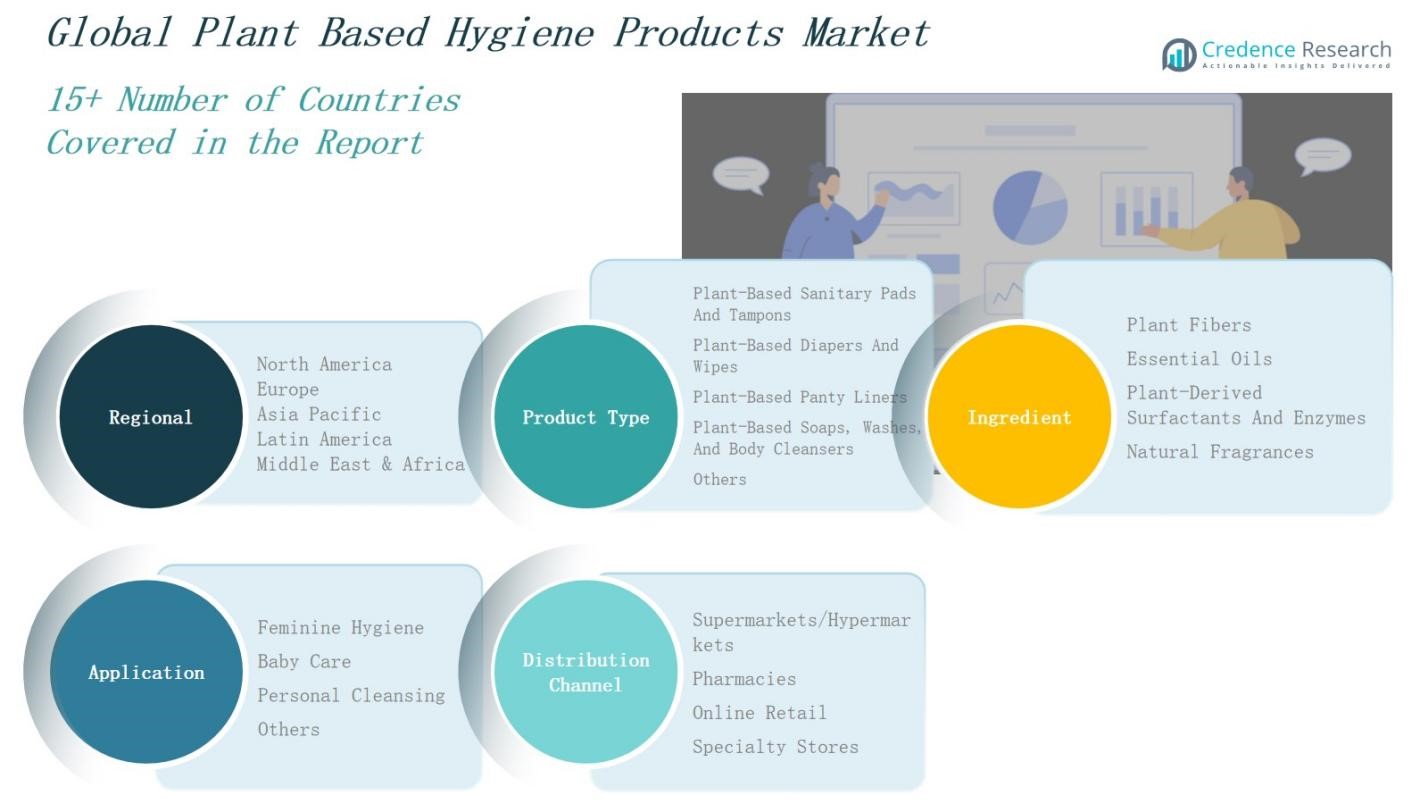
Based on Product Type
- Plant-Based Sanitary Pads and Tampons
- Plant-Based Diapers and Wipes
- Plant-Based Panty Liners
- Plant-Based Soaps, Washes, and Body Cleansers
- Others
Based on Ingredient
- Plant Fibers
- Essential Oils
- Plant-Derived Surfactants and Enzymes
- Natural Fragrances
Based on Application
- Feminine Hygiene
- Baby Care
- Personal Cleansing
- Others
Based on Distribution Channel
- Supermarkets/Hypermarkets
- Pharmacies
- Online Retail
- Specialty Stores
Based on Region
- North America (U.S., Canada, Mexico)
- Europe (UK, France, Germany, Italy, Spain, Russia, Rest of Europe)
- Asia Pacific (China, Japan, South Korea, India, Australia, Southeast Asia, Rest of Asia Pacific)
- Latin America (Brazil, Argentina, Rest of Latin America)
- Middle East (GCC, Israel, Turkey, Rest of Middle East)
- Africa (South Africa, Egypt, Rest of Africa)
Regional Analysis
North America
The North America Plant Based Hygiene Products Market size was valued at USD 8,060.42 million in 2018 to USD 13,176.08 million in 2024 and is anticipated to reach USD 26,542.32 million by 2032, at a CAGR of 8.5% during the forecast period. North America holds the largest share in the global market, accounting for over 35% of total revenue. High consumer awareness, strong presence of sustainable brands, and advanced retail infrastructure drive growth. It benefits from early adoption of organic hygiene solutions and high spending on premium personal care. U.S. leads the regional demand, followed by Canada and Mexico. Major players expand through direct-to-consumer models and green-certified innovations.
Europe
The Europe Plant Based Hygiene Products Market size was valued at USD 5,537.68 million in 2018 to USD 8,832.71 million in 2024 and is anticipated to reach USD 16,750.78 million by 2032, at a CAGR of 7.7% during the forecast period. Europe captures nearly 24% of the global share, supported by stringent environmental regulations and strong demand for ethical products. Countries such as Germany, France, and the UK lead regional growth. It benefits from institutional support for biodegradable and cruelty-free hygiene items. Consumers prefer products with third-party certifications and plastic-free packaging. Retailers promote natural offerings through specialty and mainstream outlets.
Asia Pacific
The Asia Pacific Plant Based Hygiene Products Market size was valued at USD 3,461.38 million in 2018 to USD 6,216.43 million in 2024 and is anticipated to reach USD 14,201.53 million by 2032, at a CAGR of 10.2% during the forecast period. Asia Pacific represents over 20% of the global market and ranks as the fastest-growing region. Rising urbanization, income growth, and demand for clean-label products fuel regional expansion. China, India, Japan, and South Korea lead market adoption. It sees increased investment from both multinational and regional brands targeting younger, eco-conscious consumers. E-commerce channels play a major role in driving visibility.
Latin America
The Latin America Plant Based Hygiene Products Market size was valued at USD 882.58 million in 2018 to USD 1,439.93 million in 2024 and is anticipated to reach USD 2,560.11 million by 2032, at a CAGR of 6.8% during the forecast period. Latin America holds a modest 6% share but offers strong long-term potential. Brazil and Argentina account for most regional sales, driven by growing awareness of sustainable hygiene practices. It benefits from local manufacturing and rising availability of organic ingredients. Retailers adopt private label offerings to appeal to cost-conscious shoppers. Market penetration improves through pharmacy and digital platforms.
Middle East
The Middle East Plant Based Hygiene Products Market size was valued at USD 525.48 million in 2018 to USD 793.81 million in 2024 and is anticipated to reach USD 1,346.54 million by 2032, at a CAGR of 6.2% during the forecast period. The region contributes nearly 4% of global revenue, led by the UAE, Saudi Arabia, and Israel. Growing interest in wellness, halal-certified formulations, and sustainable packaging supports demand. It faces pricing and awareness challenges but gains traction through targeted campaigns. Multinationals invest in local adaptation and regional e-commerce partnerships. Government-led sustainability programs also support market growth.
Africa
The Africa Plant Based Hygiene Products Market size was valued at USD 219.38 million in 2018 to USD 412.47 million in 2024 and is anticipated to reach USD 612.76 million by 2032, at a CAGR of 4.4% during the forecast period. Africa holds the smallest share, under 2%, but presents emerging opportunities. South Africa, Egypt, and Nigeria lead regional demand. It sees gradual growth supported by NGO awareness initiatives and donor-backed hygiene projects. Price sensitivity remains a key barrier. Local brands explore affordable solutions using indigenous plant materials. It gains visibility through community-level retail and public health programs.
Key Player Analysis
- Bamboo Babe
- Natracare
- Cora
- Pinkie
- Heyday
- Rael
- Saathi
- Organyc
- Tsuno
- LOLA
Competitive Analysis
The Plant Based Hygiene Products Market features a competitive landscape driven by innovation, sustainability, and consumer trust. Key players such as Saathi, Natracare, Cora, Rael, and LOLA focus on biodegradable materials, organic ingredients, and plastic-free packaging. It includes emerging brands like Bamboo Babe, Heyday, and Pinkie that cater to niche demands with region-specific formulations and direct-to-consumer models. Companies differentiate through third-party certifications, cruelty-free claims, and inclusive product design. E-commerce and social media play a crucial role in shaping consumer perception and brand loyalty. The market sees consistent R&D investment to improve absorption, durability, and skin safety. Global and local players compete on price, performance, and sustainability credentials. The Plant Based Hygiene Products Market encourages continuous product diversification to meet evolving consumer expectations, particularly in feminine hygiene, baby care, and personal cleansing categories. Strategic partnerships, sustainable sourcing, and targeted marketing remain central to gaining market share.
Recent Developments
- In April 2025, Unilever acquired Wild Cosmetics, a UK-based brand known for its refillable and plant-based deodorants and body care products. The deal, valued at approximately £100 million, aims to strengthen Unilever’s position in the sustainable hygiene segment and expand its eco-conscious product portfolio.
- In April 2025, Planet Smart launched PlanetSorb, a biodegradable super-absorbent polymer designed to replace traditional SAPs in menstrual pads and baby diapers. This innovation supports the shift toward fully compostable hygiene products without compromising absorbency or performance.
- In April 2025, BASF introduced three new biodegradable ingredients for personal care applications: Verdessence® Maize (a corn starch polymer), Lamesoft® OP Plus (a wax-based opacifier), and Dehyton® PK45 GA/RA (a coconut-derived betaine). These launches highlight BASF’s commitment to natural, eco-friendly formulations.
- In early 2025, Brenntag partnered with Cambrium to bring NovaColl—a precision-fermented vegan collagen—into the UK and European personal care markets. This collaboration enhances access to sustainable, bio-based ingredients for skincare and hygiene product manufacturers.
Market Concentration & Characteristics
The Plant Based Hygiene Products Market exhibits moderate market concentration, with a mix of global players and emerging regional brands competing across diverse product categories. It features companies such as Natracare, Rael, Saathi, and LOLA that maintain strong brand equity through sustainable innovation, ethical sourcing, and product transparency. The market is characterized by high consumer sensitivity to ingredients, packaging, and environmental impact, which drives continuous reformulation and product differentiation. It favors companies offering certified organic, biodegradable, and cruelty-free solutions. Competitive dynamics are shaped by direct-to-consumer strategies, influencer marketing, and e-commerce adoption. Barriers to entry remain moderate due to rising demand but are offset by the need for regulatory compliance, cost-effective manufacturing, and effective supply chain management. The Plant Based Hygiene Products Market supports rapid growth in feminine hygiene, baby care, and personal cleansing segments, while retailers promote eco-conscious lines through specialty and mainstream channels. Market players respond quickly to shifting consumer values and regional regulation.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Ingredient, Application, Distribution Channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for biodegradable and plastic-free hygiene products will continue to increase across global markets.
- Brands will expand gender-neutral and inclusive hygiene product lines to reach broader demographics.
- E-commerce and direct-to-consumer channels will play a larger role in market penetration and growth.
- Companies will invest in R&D to improve shelf life and performance of plant-based formulations.
- Emerging markets will see stronger adoption driven by rising awareness and urbanization.
- Strategic partnerships and local sourcing will help reduce production costs and increase affordability.
- Retailers will allocate more shelf space to sustainable hygiene products with eco-certifications.
- Influencer-led marketing will shape brand visibility and consumer trust in plant-based options.
- New product launches will focus on refillable, reusable, and zero-waste packaging formats.
- Regulatory standards will tighten, pushing brands toward higher transparency and ethical compliance.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Plant Based Hygiene Products Market?
What factors are driving the growth of the Plant Based Hygiene Products Market?
What are the key segments within the Plant Based Hygiene Products Market?
What are some challenges faced by the Plant Based Hygiene Products Market?
Who are the major players in the Plant Based Hygiene Products Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Plant Based Hygiene Products Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Plant Based Hygiene Products Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 30,871.44 million → 2032: USD 62,014.05 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Plant Based Hygiene Products Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Plant Based Hygiene Products Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Plant Based Hygiene Products Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Plant Based Hygiene Products Market Drivers
- 3.3 Plant Based Hygiene Products Market Restraints & Challenges
- 3.4 Plant Based Hygiene Products Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Plant Based Hygiene Products Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Plant Based Hygiene Products Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Plant Based Hygiene Products category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Plant Based Hygiene Products Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Plant Based Hygiene Products Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Plant Based Hygiene Products market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Plant Based Hygiene Products Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Plant Based Hygiene Products Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Plant Based Hygiene Products Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Plant Based Hygiene Products (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Plant Based Hygiene Products Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Plant Based Hygiene Products Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Plant Based Hygiene Products Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Plant Based Hygiene Products Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Plant Based Hygiene Products Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Plant Based Hygiene Products Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Plant Based Hygiene Products Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Plant Based Hygiene Products Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Plant Based Hygiene Products Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
