
Market Overview
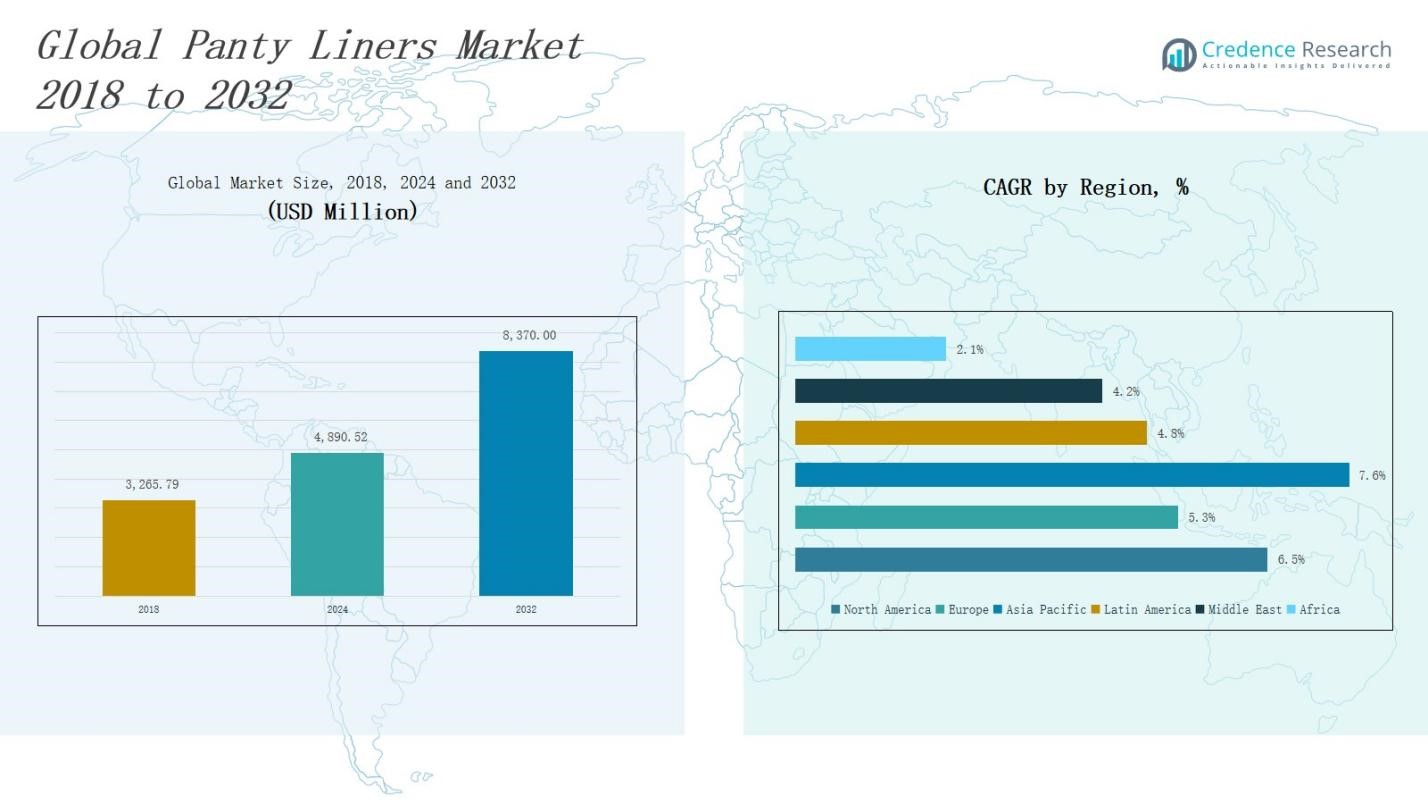
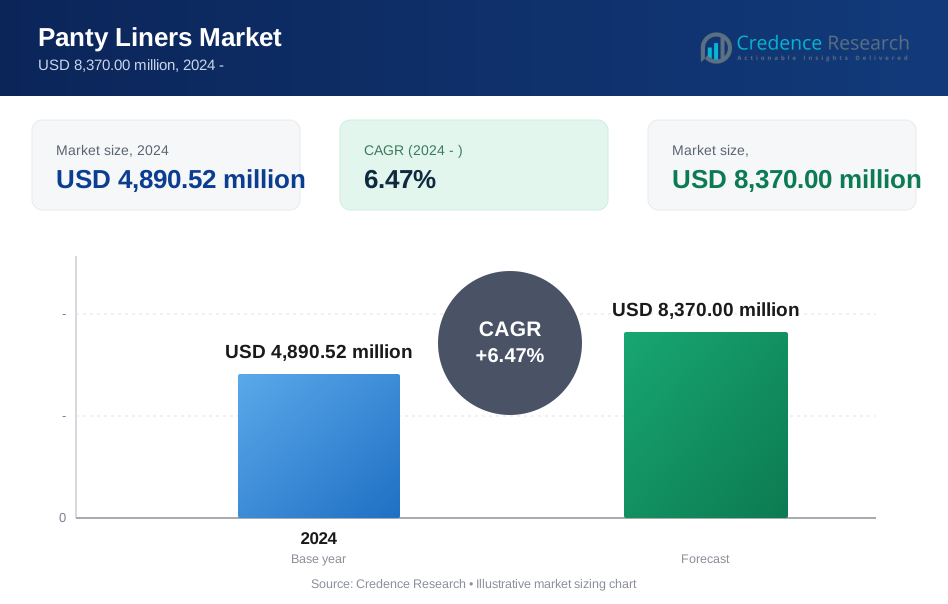
The Panty Liners Market size was valued at USD 3,265.79 million in 2018 to USD 4,890.52 million in 2024 and is anticipated to reach USD 8,370.00 million by 2032, at a CAGR of 6.47% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Panty Liners Market Size 2024 | USD 4,890.52 Million |
| Panty Liners Market, CAGR | 6.47% |
| Panty Liners Market Size 2032 | USD 8,370.00 Million |
The Panty Liners Market is driven by rising awareness of feminine hygiene, increasing urbanization, and growing demand for convenient, discreet personal care products. Expanding female workforce participation and changing lifestyles support daily use of panty liners for freshness and light discharge management. Trends include product innovations such as ultra-thin, breathable, and organic variants, along with eco-friendly packaging to align with sustainability goals. Brands are leveraging e-commerce platforms and influencer marketing to boost consumer engagement. The market is also witnessing rising adoption in emerging economies due to improved access, education, and government initiatives promoting menstrual hygiene awareness.
The Panty Liners Market spans North America, Europe, Asia Pacific, Latin America, the Middle East, and Africa, with North America holding the largest share and Asia Pacific showing the fastest growth. It sees rising adoption due to urbanization, awareness, and improved retail access across regions. Key players include Procter & Gamble, Kimberly-Clark, Unilever, Johnson & Johnson, Essity, Kao Corporation, Unicharm, Edgewell, Ontex, First Quality Enterprises, Hengan Group, and The Honest Company, each competing through innovation, sustainability, and multi-channel distribution strategies tailored to regional consumer preferences.
Market Insights
- The Panty Liners Market was valued at USD 3,265.79 million in 2018 and is expected to reach USD 8,370.00 million by 2032, growing at a CAGR of 6.47%.
- Key growth drivers include increasing awareness of feminine hygiene, urbanization, and expanding female workforce participation.
- Product innovation in ultra-thin, breathable, organic, and eco-friendly panty liners supports demand across diverse demographics.
- Limited awareness and cultural resistance in emerging markets restrict adoption, especially in rural and conservative regions.
- North America holds the largest market share, while Asia Pacific leads in growth due to rising income levels and e-commerce expansion.
- Europe shows strong preference for organic and dermatologically safe options, driven by stringent regulations and wellness trends.
- Leading players such as Procter & Gamble, Unilever, Kimberly-Clark, and The Honest Company compete through innovation, sustainability, and omni-channel strategies.
Market Drivers
Rising Focus on Feminine Hygiene and Health Awareness
The Panty Liners Market benefits from growing awareness around feminine hygiene and health. Consumers increasingly recognize the importance of daily hygiene routines, leading to regular use of panty liners beyond menstrual cycles. Campaigns by healthcare organizations and government bodies encourage sanitary product usage, especially in developing regions. Education and awareness programs play a key role in influencing buyer behavior. It aligns with personal care trends focused on wellness, comfort, and proactive hygiene management.
Expanding Female Workforce and Lifestyle Shifts
The rise in female workforce participation across urban and semi-urban areas strongly supports demand in the Panty Liners Market. Women prefer products that offer all-day freshness, especially during long work hours and travel. It caters to changing routines and evolving lifestyle needs. Busy schedules encourage the adoption of quick, convenient hygiene solutions. The demand intensifies in regions experiencing rising economic independence among women. This trend continues to fuel sustained market expansion globally.
For instance, Kimberly-Clark’s Kotex line expanded its range of travel-friendly panty liners designed for convenience and freshness on the go, addressing demands from women with hectic and mobile lifestyles.
Product Innovation in Materials, Design, and Functionality
Advancements in material science and product design significantly drive the Panty Liners Market. Manufacturers introduce ultra-thin, breathable, and dermatologically tested liners to meet user comfort and skin sensitivity needs. It also includes developments in odor control, absorbency, and adhesive technology. Organic and chemical-free alternatives appeal to health-conscious buyers. The integration of eco-friendly materials aligns with sustainability preferences. These innovations differentiate products and strengthen brand positioning in a highly competitive space.
For instance, Always launched panty liners featuring OdorLock technology that neutralizes odors while providing a breathable, ultra-thin feel, catering specifically to comfort and freshness needs.
Growing Availability Through Retail and Digital Channels
The Panty Liners Market benefits from increased accessibility through organized retail and digital commerce platforms. Supermarkets, pharmacies, and e-commerce channels offer wide product visibility and convenience. It supports impulse buying and trial of new variants. Online platforms enable tailored promotions and subscription services, enhancing customer retention. Direct-to-consumer brands leverage digital tools to reach younger demographics. Enhanced distribution infrastructure helps expand presence in rural and underserved markets, further increasing product penetration.
Market Trends
Surge in Demand for Organic and Biodegradable Panty Liners
The Panty Liners Market is witnessing a shift toward organic and biodegradable products driven by rising environmental awareness and consumer health concerns. Consumers seek products free from synthetic fragrances, dyes, and chlorine. It creates demand for plant-based liners made from cotton, bamboo, or corn fiber. Brands are investing in eco-certified materials and compostable packaging. This trend supports brand differentiation while catering to consumers prioritizing sustainability and skin-safe formulations in daily hygiene routines.
For instance, Eco by Naty Panty Liners, crafted from 100% plant-based, certified compostable materials, with high absorbency and zero oil-based plastic waste, ideal for sensitive skin types seeking sustainable hygiene solutions.
Focus on Ultra-Thin, Discreet, and Comfortable Designs
Modern consumers expect panty liners that offer both functionality and comfort. The Panty Liners Market is responding with ultra-thin, lightweight designs that are barely noticeable during use. It helps women incorporate liners into their everyday routine without discomfort. Enhanced adhesive technologies, flexible shapes, and breathable layers are becoming standard features. These product advancements improve retention, reduce irritation, and increase daily usage rates across age groups. Comfort-focused innovation remains a central theme in product development.
For instance, Plush panty liners stand out with their ultra-thin 1mm design made from 100% US cotton, offering superior softness and gentle skin contact for all-day comfort.
Growing Influence of Digital Marketing and Influencer Endorsements
Digital marketing plays a crucial role in shaping consumer behavior in the Panty Liners Market. Influencer endorsements, social media campaigns, and wellness blogs highlight the importance of daily hygiene. It helps normalize panty liner usage beyond menstruation. Startups and established brands use Instagram, YouTube, and TikTok to demonstrate product features and benefits. Personalized messaging appeals to Gen Z and millennial audiences. Digital content accelerates product discovery, consumer trust, and brand loyalty in an otherwise private product category.
Expansion of Subscription-Based and Direct-to-Consumer Models
Subscription services and direct-to-consumer strategies are reshaping the Panty Liners Market. Companies offer customized delivery plans that ensure privacy, convenience, and uninterrupted supply. It supports recurring revenue and improves customer retention. These models provide flexibility in product choices, packaging sizes, and timing. Consumers appreciate personalized solutions delivered discreetly. Startups entering the market are prioritizing DTC approaches to bypass traditional retail and engage with tech-savvy consumers more effectively across online platforms.
Market Challenges Analysis
Limited Awareness and Cultural Barriers in Emerging Markets
The Panty Liners Market faces challenges in regions where feminine hygiene remains a taboo subject. Limited awareness, misinformation, and cultural resistance restrict product adoption in rural and conservative areas. It affects market penetration despite growing availability. Many women are unaware of the benefits of daily liners or hesitate to use them due to societal norms. Educational outreach and behavior change campaigns remain inconsistent. These factors slow growth in developing economies with large untapped potential.
Price Sensitivity and Competition from Alternative Products
Affordability remains a major concern, especially in price-sensitive markets. The Panty Liners Market competes with reusable hygiene products and low-cost sanitary pads that often serve multiple needs. It must offer differentiated value to justify daily use expenses. High-quality, organic, or branded products may be inaccessible to low-income segments. Rising raw material and transportation costs also impact pricing strategies. Balancing product innovation with affordability continues to challenge both established and new market entrants.
Market Opportunities
Untapped Potential in Rural and Emerging Economies
The Panty Liners Market holds strong growth potential in rural and emerging economies where product awareness and access remain low. Rising literacy rates, healthcare outreach, and government-backed hygiene programs are creating a favorable environment for market expansion. It can benefit from localized campaigns, affordable SKUs, and educational initiatives to drive adoption. Partnerships with NGOs and community health workers can further bridge the awareness gap. Brands that tailor products to regional needs can unlock significant demand across underserved markets.
Innovation in Sustainable Materials and Customization
The push for sustainability creates new avenues for innovation in the Panty Liners Market. Consumers seek eco-conscious products that align with personal values and environmental responsibility. It creates opportunities for brands to develop liners using compostable, biodegradable, or reusable materials. Customization in size, shape, and packaging also enhances user appeal. Digital platforms enable targeted offerings based on lifestyle, usage patterns, and skin type. Companies investing in green technologies and user-centric designs can capture emerging demand across premium and conscious consumer segments.
Market Segmentation Analysis:
By Product Type
The Panty Liners Market includes two primary product types: disposable and reusable panty liners. Disposable liners dominate due to their convenience, widespread availability, and single-use hygiene assurance. Reusable liners are gaining attention among environmentally conscious consumers seeking sustainable alternatives. It reflects growing interest in washable, cloth-based products made from organic materials. Despite slower adoption, reusable options show potential in developed markets where eco-friendly lifestyles and reduced waste are key priorities.
For instance, Procter & Gamble’s Always liners are designed with ultra-thin, individually wrapped sheets that provide discreet, single-use protection and enable easy disposal for on-the-go consumers.
By Nature
The market segments by nature into organic and conventional panty liners. Conventional liners maintain a larger share due to established consumer preference and lower cost. However, demand for organic panty liners is rising as consumers prioritize skin-friendly, chemical-free products. The Panty Liners Market benefits from innovations in natural fiber usage, such as cotton and bamboo, in the organic category. It supports niche brands and premium lines focused on wellness and sustainability.
For instance, Always has introduced organic cotton panty liners that are fragrance-free and dermatologically tested, appealing to sensitive skin consumers.
By Price Category
The Panty Liners Market is categorized into economic, mid-range, and premium price tiers. Economic products see high volume sales in developing regions driven by affordability and mass-market reach. Mid-range liners offer a balance of quality and price, appealing to urban users with moderate income levels. Premium liners attract health-conscious consumers seeking specialized features like organic content, ultra-thin design, and superior comfort. It enables brands to differentiate through innovation, quality, and lifestyle alignment.
Segments
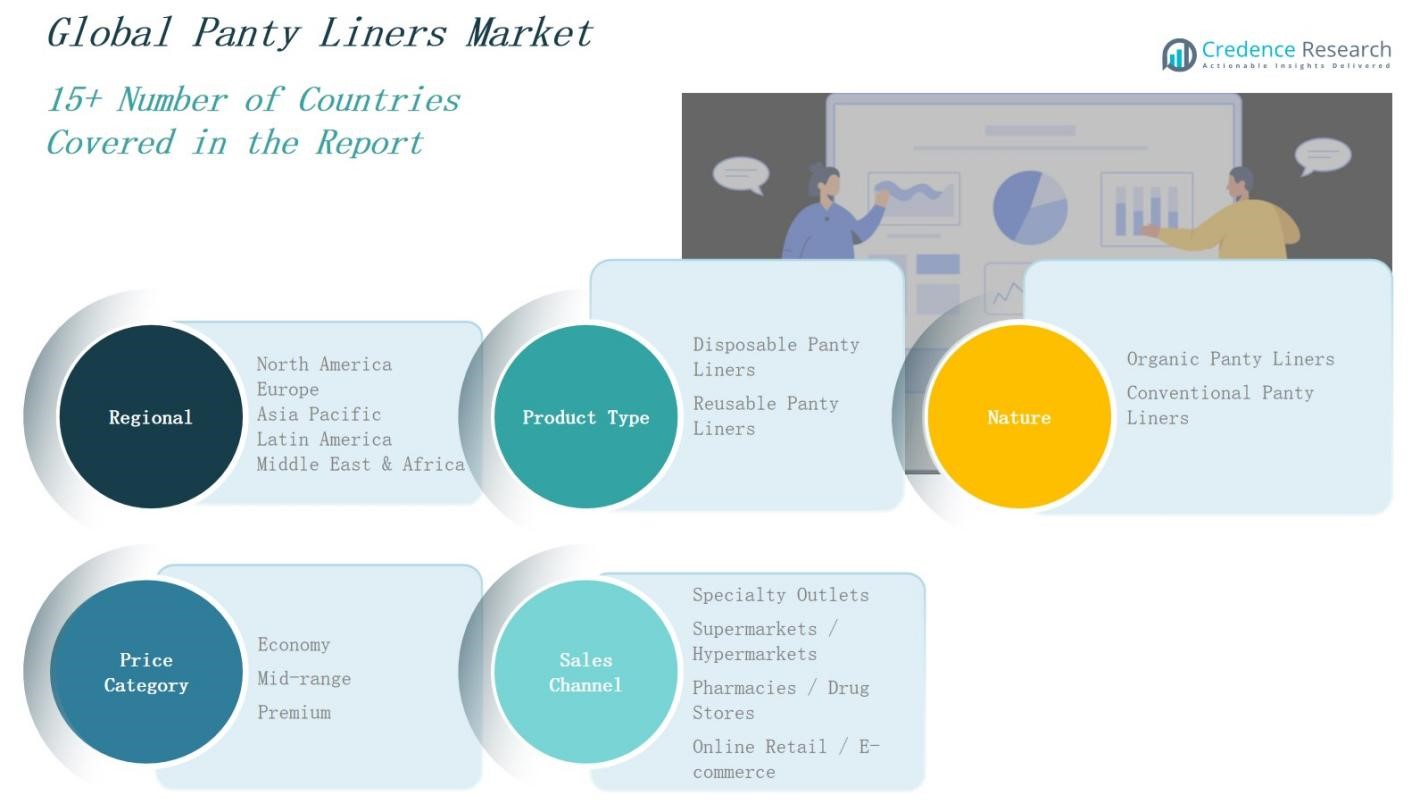
Based on Product Type
- Disposable Panty Liners
- Reusable Panty Liners
Based on Nature
- Organic Panty Liners
- Conventional Panty Liner
Based on Price Category
- Economic
- Mid-range
- Premium
Based on Sales Channel
- Specialty Outlets
- Supermarkets / Hypermarkets
- Pharmacies / Drug Stores
- Online Retail / E-commerce
Based on Region
- North America (U.S., Canada, Mexico)
- Europe (UK, France, Germany, Italy, Spain, Russia, Rest of Europe)
- Asia Pacific (China, Japan, South Korea, India, Australia, Southeast Asia, Rest of Asia Pacific)
- Latin America (Brazil, Argentina, Rest of Latin America)
- Middle East (GCC, Israel, Turkey, Rest of Middle East)
- Africa (South Africa, Egypt, Rest of Africa)
Regional Analysis
North America
The North America Panty Liners Market size was valued at USD 1,408.31 million in 2018 to USD 2,086.76 million in 2024 and is anticipated to reach USD 3,581.48 million by 2032, at a CAGR of 6.5% during the forecast period. North America holds the largest market share in the Panty Liners Market, driven by strong consumer awareness, high product penetration, and the presence of leading brands. It benefits from a well-established retail infrastructure and increasing demand for premium and organic variants. The U.S. accounts for the majority share due to greater disposable income and lifestyle-focused consumption patterns. Brands leverage digital platforms and subscription models to improve retention. Innovation, sustainability, and brand loyalty continue to define regional dynamics.
Europe
The Europe Panty Liners Market size was valued at USD 640.85 million in 2018 to USD 909.65 million in 2024 and is anticipated to reach USD 1,422.92 million by 2032, at a CAGR of 5.3% during the forecast period. Europe ranks as the second-largest market, supported by strong demand for eco-friendly and dermatologically safe products. It is driven by stringent regulations on chemical content and sustainability compliance. Western European countries show higher adoption of organic and biodegradable liners. Consumer education and wellness trends help shape purchase decisions. Distribution through pharmacies, supermarkets, and e-commerce ensures broad accessibility.
Asia Pacific
The Asia Pacific Panty Liners Market size was valued at USD 935.13 million in 2018 to USD 1,479.26 million in 2024 and is anticipated to reach USD 2,763.06 million by 2032, at a CAGR of 7.6% during the forecast period. Asia Pacific is the fastest-growing region in the Panty Liners Market due to urbanization, rising female workforce participation, and growing awareness of feminine hygiene. Countries like China, India, and Japan lead the expansion, supported by improved access to personal care products. It sees rapid growth in both premium and affordable segments. Companies invest in localized marketing and affordable SKUs to meet diverse consumer needs. E-commerce adoption and digital health campaigns also contribute to accelerating demand.
Latin America
The Latin America Panty Liners Market size was valued at USD 154.24 million in 2018 to USD 228.11 million in 2024 and is anticipated to reach USD 345.54 million by 2032, at a CAGR of 4.8% during the forecast period. The region shows steady growth supported by increasing female hygiene awareness and expanding retail networks. Brazil and Argentina are the leading contributors to regional demand. The Panty Liners Market here benefits from rising access to disposable hygiene products, though affordability remains a constraint. Mid-range and economic products perform well in price-sensitive demographics. Distribution partnerships and awareness campaigns are crucial to market expansion.
Middle East
The Middle East Panty Liners Market size was valued at USD 92.19 million in 2018 to USD 126.29 million in 2024 and is anticipated to reach USD 182.66 million by 2032, at a CAGR of 4.2% during the forecast period. The market in the Middle East grows steadily, supported by improving women’s health awareness and retail modernization. It is concentrated in GCC countries where consumer spending is higher. Demand centers around convenience and discreet packaging. Retail pharmacy chains and online platforms play a key role in product visibility. Cultural preferences and regulatory structures influence product design and marketing strategies.
Africa
The Africa Panty Liners Market size was valued at USD 35.07 million in 2018 to USD 60.45 million in 2024 and is anticipated to reach USD 74.33 million by 2032, at a CAGR of 2.1% during the forecast period. Africa represents the smallest market share in the Panty Liners Market but offers long-term potential. Low product awareness and limited access to hygiene solutions slow adoption. It depends on government initiatives, NGO efforts, and educational programs to promote sanitary practices. South Africa leads regional consumption, followed by Egypt. Affordable pricing, small pack sizes, and rural outreach will shape future market strategies.
Key Player Analysis
- Edgewell Personal Care Company
- Unilever PLC
- Hengan Group
- Ontex
- Procter & Gamble Company
- First Quality Enterprises Inc.
- The Honest Company
- Kimberly-Clark Corporation
- Essity AB
- Johnson & Johnson Services Inc.
- Kao Corporation
- Unicharm Corporation
Competitive Analysis
The Panty Liners Market features intense competition among global and regional players focused on product innovation, brand positioning, and distribution expansion. Key companies such as Procter & Gamble, Kimberly-Clark, Unilever, and Johnson & Johnson maintain strong market presence through wide product portfolios and strong retail networks. It also includes emerging brands like The Honest Company and Ontex targeting niche segments with organic and sustainable offerings. Players invest in R&D to develop thinner, skin-friendly, and eco-conscious products. E-commerce, private-label expansion, and personalized subscription models intensify the competitive landscape. Pricing, packaging, and promotional strategies further differentiate market leaders. Strategic mergers, regional partnerships, and market-specific product customization help companies strengthen their global footprint and meet evolving consumer needs.
Recent Developments
- In February 2025, H.B. Fuller launched its Full-Care 6550 SecureFix adhesive to enhance fit, comfort, and performance in panty liners designed for active users.
- In March 2024, Revaa, a brand dedicated to women's health and hygiene, introduced three product lines including "Menstrual Magic," which features offerings in the panty liners space.
- In 2023, Gyns introduced its Anion Sanitary Napkins & Panty Liners, aiming to provide sustainable, comfortable, and odor-controlling feminine hygiene products.
- In February 2025, H.B. Fuller introduced Full-Care 6550 SecureFix adhesive, optimized for active‑wear panty liners to enhance fit, comfort, and performance.
Market Concentration & Characteristics
The Panty Liners Market exhibits moderate to high market concentration, with a few multinational companies dominating global sales through strong brand equity, expansive distribution, and innovation capabilities. It features a mix of established players like Procter & Gamble, Kimberly-Clark, and Johnson & Johnson, alongside niche and emerging brands offering organic or sustainable alternatives. The market is characterized by brand loyalty, frequent product launches, and continuous R&D investment to improve comfort, absorbency, and eco-compatibility. It responds quickly to shifts in consumer preferences, especially in hygiene, wellness, and sustainability. Entry barriers include regulatory compliance, high marketing costs, and the need for extensive retail access. Price sensitivity varies across regions, creating space for private labels in cost-conscious segments. The Panty Liners Market remains dynamic, driven by both premiumization and value-based offerings, with companies leveraging digital platforms, subscription models, and targeted campaigns to strengthen customer engagement and expand market share in competitive and evolving environments.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Nature, Price Category, Sales Channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for organic and biodegradable panty liners will continue to grow with rising environmental and health awareness.
- Brands will expand into rural and underserved areas through affordable SKUs and awareness campaigns.
- Product innovation will focus on ultra-thin, breathable, and skin-friendly materials for daily comfort.
- E-commerce and direct-to-consumer channels will play a larger role in reaching younger consumers.
- Subscription-based models will gain popularity for convenience and brand loyalty.
- Private label brands will strengthen presence in cost-sensitive regions with competitive pricing.
- Influencer marketing and digital advertising will drive product visibility and trial.
- Companies will invest in localized manufacturing to improve supply chain efficiency and regional customization.
- Urbanization and rising female workforce participation will continue to support everyday panty liner usage.
- Strategic collaborations and acquisitions will help major players expand portfolios and enter new markets.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Focus on Feminine Hygiene and Health Awareness
Increased education and awareness campaigns by governments and NGOs are encouraging women to adopt daily hygiene routines, driving regular use of panty liners beyond menstrual cycles. This shift is particularly impactful in developing regions where awareness was previously low.
Expanding Female Workforce and Lifestyle Shifts
Growing participation of women in the workforce and changing urban lifestyles are boosting demand for convenient, discreet hygiene solutions like panty liners, which offer all-day freshness and comfort for busy routines.
Product Innovation in Materials, Design, and Functionality
Manufacturers are introducing ultra-thin, breathable, organic, and dermatologically tested panty liners, appealing to consumers seeking comfort, skin safety, and sustainability. These innovations help brands differentiate in a competitive market.
Growing Availability Through Retail and Digital Channels
The expansion of organized retail, e-commerce, and direct-to-consumer models has improved product accessibility, enabling wider reach, tailored promotions, and subscription services that drive trial and repeat purchases.
Surge in Demand for Organic and Biodegradable Panty Liners
Environmental and health concerns are fueling demand for organic, biodegradable, and chemical-free panty liners, prompting brands to invest in plant-based materials and eco-friendly packaging to attract conscious consumers.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Panty Liners Market?
What factors are driving the growth of the Panty Liners Market?
What are the key segments within the Panty Liners Market?
What are some challenges faced by the Panty Liners Market?
Who are the major players in the Panty Liners Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Nature
- 1.2.1 Organic Panty Liners
- 1.2.2 Conventional Panty Liners
- 1.3 By Product Type
- 1.3.1 Disposable Panty Liners
- 1.3.2 Reusable Panty Liners
- 1.4 By Sales Channel
- 1.4.1 Specialty Outlets
- 1.4.2 Supermarkets / Hypermarkets
- 1.4.3 Pharmacies / Drug Stores
- 1.4.4 Online Retail / E-commerce
- 1.5 By Price Category
- 1.5.1 Economic
- 1.5.2 Mid-range
- 1.5.3 Premium
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 4,890.52 million → 2032: USD 8,370.00 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Panty Liners Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Panty Liners Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Panty Liners Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Panty Liners Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Panty Liners Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Panty Liners Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Panty Liners Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Panty Liners Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 4,890.52 million → 2032: USD 8,370.00 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Panty Liners Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Nature - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Organic Panty Liners
- 12.3.7.2 Conventional Panty Liners
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Disposable Panty Liners
- 12.4.7.2 Reusable Panty Liners
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Sales Channel - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Specialty Outlets
- 12.5.7.2 Supermarkets / Hypermarkets
- 12.5.7.3 Pharmacies / Drug Stores
- 12.5.7.4 Online Retail / E-commerce
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Price Category - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Economic
- 12.6.7.2 Mid-range
- 12.6.7.3 Premium
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Panty Liners Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Panty Liners Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Panty Liners Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Procter & Gamble
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Kimberly-Clark
- 17.4 Unilever
- 17.5 Johnson & Johnson
- 17.6 Essity
- 17.7 Kao Corporation
- 17.8 Unicharm
- 17.9 Edgewell Personal Care
- 17.10 Ontex
- 17.11 The Honest Company
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

