
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
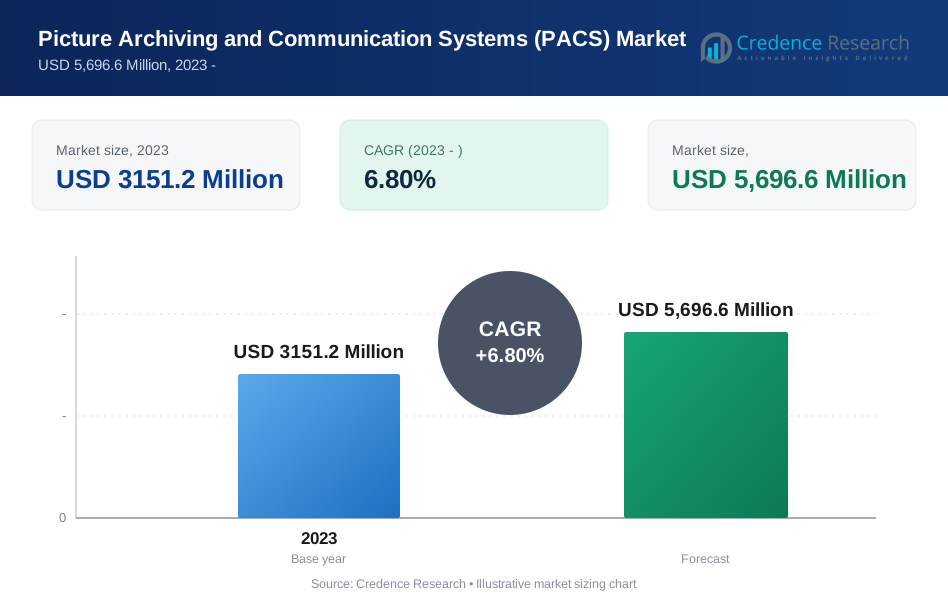
| Picture Archiving and Communication Systems (PACS) Market Size 2023 | USD 3151.2 Million |
| Picture Archiving and Communication Systems (PACS) Market, CAGR | 6.80% |
| Picture Archiving and Communication Systems (PACS) Market Size 2032 | USD 5696.6 Million |
Market Insights
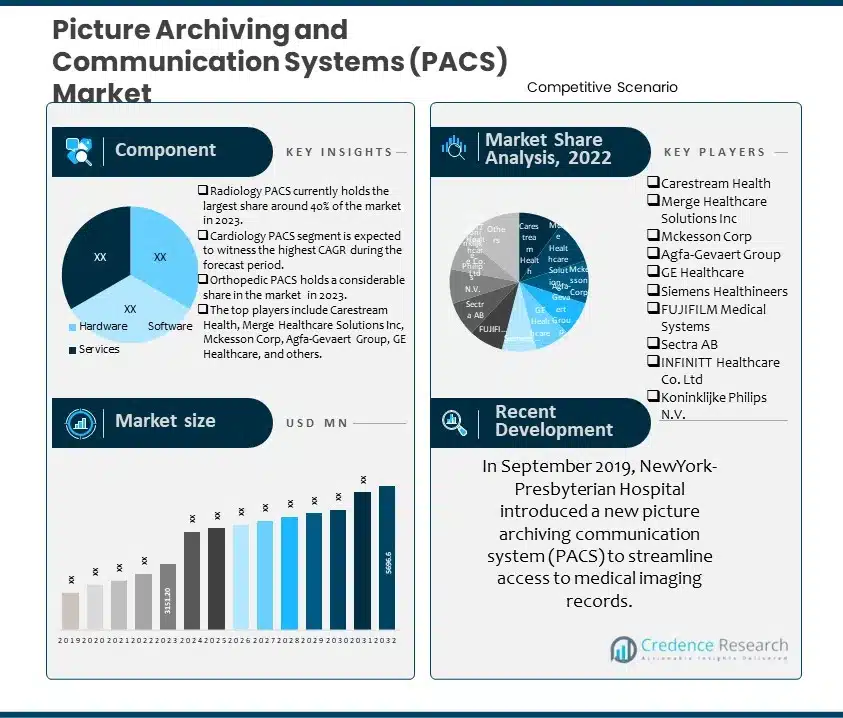
- The global demand for Picture Archiving and Communication Systems (PACS) was valued at USD 3151.2 Million in 2023 and is expected to reach USD 5696.6 Million in 2032, growing at a CAGR of 6.80% between 2024 and 2032.
- The On-premises deployment segment is the market leader, accounting for around 60-65% of total market share in 2023, while the Cloud-Based PACS segment is expected to witness rapid growth throughout the forecast period.
- Hospitals currently hold the largest share, around 65-70% of the PACS market in 2023, while Ambulatory Surgical Centers (ASCs) segment is expected to witness the highest CAGR during the forecast period.
- Radiology PACS currently holds the largest share, around 40% of the market in 2023. Radiology departments generate the most medical images, which is the main reason driving the market.
- Cardiology PACS segment is expected to witness the highest CAGR during the forecast period.
- The Web-Based/Cloud mode of access category is expected to expand quickly over the forecast period, while the Standalone/Local PACS segment will have the greatest market share in 2023.
- X-Ray PACS currently holds the largest share of the PACS market, around 40-45% as of 2023. Meanwhile, ultrasound PACS is expected to witness the highest CAGR during the forecast period due to its portability, expanding applications, and cost-effectiveness.
- North America is fueling the growth of the Picture Archiving and Communication Systems (PACS) industry with over one-third share in 2023, while Asia Pacific and Europe collectively account for just under 55% share in 2023. Europe held over 20% share in 2023.
Executive Summary
Market Definition
Picture Archiving and Communication Systems (PACS) is a medical imaging technology used primarily in healthcare organizations to store, retrieve, present, and share images produced by various medical hardware modalities, such as magnetic resonance imaging (MRI) scans, X-ray machines, computed tomography (CT) scans, and ultrasound machines. PACS has four main uses: it may be used instead of hard-copy films and management of physical archives, enables clinicians in different locations to review the same data simultaneously in order to collaborate or consult on a case, offers an electronic platform for images interfacing with other health IT automated systems such as a hospital information electronic health record (EHR) and radiology information system to facilitate data-sharing and provide clinicians with a more comprehensive view of the patient's medical history, and allows radiologists and other radiology and medical personnel to streamline and manage the workflow of patient exams.
Market Overview
The global Picture Archiving and Communication Systems (PACS) market has witnessed steady growth in recent years and is expected to grow at a CAGR of 6.80% between 2024 and 2032. The market was valued at USD 3151.2 million in 2023 and is expected to reach USD 5696.6 million in 2032.
The key driver boosting the growth rate of the Picture Archiving and Communication Systems (PACS) market is driven by increasing adoption of cloud technology across various industries, including healthcare, driven by its benefits in terms of scalability, flexibility, and cost-effectiveness. The increased demand for medical imaging and connection with various healthcare systems positively impacts the target market's expansion. The market for PACS is expanding due to the healthcare industry's increasing adoption of digital imaging technologies.
Furthermore, the expansion of the Picture Archiving and Communication Systems (PACS) market is actively driven by the consistency and efficiency of PACS, which operates effectively in storing, retrieving, and sharing medical images. The market is expected to grow significantly during the forecast period due to the rising adoption of PACS solutions in healthcare institutions.
In addition, the increased use of PACS in new medical devices and the need for advanced medical imaging solutions will create several new opportunities for the Picture Archiving and Communication Systems (PACS) market to expand during the forecast period.
Segmentation by Deployment Type
- On-premises segment holds the largest share in the global Picture Archiving and Communication Systems (PACS) market, around 60-65%. On-premises PACS solutions have been widely used in healthcare institutions due to concerns about data security, control, and compliance regulations. These systems are installed locally within the healthcare facility and managed by the institution's IT department.
- Cloud-Based PACS segment is expected to witness the highest CAGR during the forecast period. This growth is driven by increasing adoption of cloud technology across various industries, including healthcare, driven by its benefits in terms of scalability, flexibility, and cost-effectiveness.
Segmentation by Component
- Software held largest share around 70-80% of the market in 2023. This is due to its constantly evolves with new features and integrations, driving higher investment for upgrades and innovation.
- Services segment is expected to witness the highest CAGR during the forecast period. This growth is driven by shift towards cloud-based PACS solutions requires specialized services for migration, data security, and integration.
- The hardware segment currently holds the significant share of the PACS market due to complex functionalities, and diverse offerings.
Segmentation by Imaging Modality
- X-Ray PACS currently holds the largest share of the PACS market around 40-45% as of 2023. X-rays are the most commonly used imaging modality, generating a massive volume of images requiring storage and manipulation which drives the market growth of this segment.
- Ultrasound PACS is expected to witness the highest CAGR during the forecast period due to its portability, expanding applications, and cost-effectiveness.
Segmentation by End-User
- Hospitals currently hold the largest share around 65-70% of the PACS market in 2023. Hospitals handle a larger volume of medical images due to their diverse patient care services, which necessitates advanced imaging technologies like PACS. Additionally, hospitals having larger budgets, enabling them to invest in sophisticated PACS technology, which drives the market growth of this segment.
- Ambulatory Surgical Centers (ASCs) segment is expected to witness the highest CAGR during the forecast period. Increasing popularity of outpatient procedures rising demand for ASCs, driving the need for PACS solutions.
Segmentation by Type of PACS
- Radiology PACS currently holds the largest share around 40% of the market in 2023. Radiology departments generate the most medical images which main reason drives the market.
- Cardiology PACS segment is expected to witness the highest CAGR during the forecast period. The increasing prevalence of heart conditions is driving demand for specialized cardiac imaging and PACS solutions. For instance, in November 2023, Philips launched HealthSuite Imaging, a cloud-based next-generation PACS, at RSNA23. It offers AI-enabled clinical & operational workflows, high-speed remote access, integrated reporting, & workflow orchestration, easing IT management burdens.
Segmentation by Mode of Access
- Standalone/Local holds the largest share around 40% of the market in 2023. Standalone/Local provide enhanced adaptability and the ability to craft customized solutions that align with the unique workflows and requirements of an institution.
- Web-Based/Cloud PACS is expected to witness the highest CAGR during the forecast period.
Segmentation by Functionality
- Standalone PACS hold the largest share of the market around 60-65% as of 2023. Standalone PACS have a longer history and typically offer more straightforward and cost-effective options.
- Integrated PACS is expected to witness the highest CAGR during the forecast period.
Segmentation by Region
- North America held significant share around 38% of the market in 2023. This dominance is attributed to the due to the high adoption of advanced technology, and increasing medical imaging volumes in the region.
- Asia Pacific and Europe collectively account for just under 55% share in 2023, with Europe holding over 20% share in the same year.
- The rest of the world, including Latin America, the Middle East, and Africa, supplies the remaining demand for Picture Archiving and Communication Systems (PACS).
Technological advancements within the Picture Archiving and Communication Systems (PACS) industry, such as the digitalization of healthcare contributing to market growth.
North America's PACS market growth is driven by the high adoption of advanced technology and the presence of large players in the region. The United States, in particular, plays a significant role in the global market, with technological innovation and advancement optimizing the performance of PACS systems. This has led to the integration of PACS with AI, cloud-based solutions, and specialty PACS, further enhancing the growth of the market. For instance, in September 2019, NewYork-Presbyterian Hospital introduced a new picture archiving communication system (PACS) to streamline access to medical imaging records. The Philips IntelliSpace PACS will replace four separate systems, allowing physicians, patients, and staff to access all imaging records through one standardized platform. The adoption of a new PACS system by a prestigious hospital like NewYork-Presbyterian generate interest and increase demand for similar systems among other hospitals and healthcare facilities in North America, driving market growth.
The Asia-Pacific region is emerging as a significant growth area for the Picture Archiving and Communication Systems (PACS) market. In recent years, there has been an increasing demand for advanced healthcare technologies, driven by factors such as population aging, rising healthcare expenditure, and government initiatives to enhance healthcare infrastructure. Companies are leveraging strategic partnerships and acquisitions to expand their presence in the regional market. For instance, in January 2022, Mitsui & Co., Ltd.'s acquisition of shares in PSP, a PACS service provider, aims to strengthen its position in the Japanese PACS market. Similarly, in October 2020, Chinese technology conglomerate Tencent's launched AI-powered medical image sharing platform AIMIS Medical Image Cloud is expected to expand its presence in the PACS market. These developments indicate that the APAC region will continue to be a key driver of growth for the global PACS market during the forecast period.
Key Highlights of the Report
The global Picture Archiving and Communication Systems (PACS) market is segmented by deployment type, end-users, imaging modalities, functionality, mode of access, Type of PACS, and region. On-premises PACS solutions are the most widely used, while hospitals and diagnostic imaging centers are the primary segments. Additionally, radiology PACS and cardiology PACS are the most commonly utilized modalities. Moreover, standalone PACS systems and web-based/cloud PACS solutions dominate the market.
One of the main factors driving the global market for Picture Archiving and Communication Systems (PACS) is the increasing adoption of digital imaging technologies in healthcare. The growing need for medical imaging and seamless integration with electronic health records (EHRs) and other healthcare IT systems fuels the demand for PACS solutions. The rising popularity of cloud-based PACS due to their scalability and cost-effectiveness is also contributing to market growth.
Nevertheless, North America is expected to have the largest share of the global Picture Archiving and Communication Systems (PACS) market due to the region's high adoption of advanced healthcare technology and the presence of key market players. Furthermore, the market is anticipated to witness the highest growth rate in the Asia-Pacific (APAC) region, driven by increasing healthcare expenditure, government initiatives to improve healthcare infrastructure, and the presence of electronics manufacturing firms.
What Are The Main Drivers Of The Global Picture Archiving and Communication Systems (PACS) Market?
The global Picture Archiving and Communication Systems (PACS) market is driven by several factors, including increasing prevalence of chronic diseases and a growing elderly population are significant factors driving the Picture Archiving and Communication System (PACS) market. Chronic diseases necessitate continuous monitoring and diagnosis, leading to a higher demand for imaging devices and healthcare cloud PACS. The elderly population requires more medical imaging and diagnostics, further fueling the demand for PACS. Additionally, the shift towards cloud-based PACS provides secure and safe data storage, reducing the risk of hardware damage and increasing the efficiency of healthcare services.
What Are The Major Challenges Faced By The Global Picture Archiving and Communication Systems (PACS) Market?
The main factors limiting the growth of Picture Archiving and Communication Systems (PACS) is the rising incidence of data breaches and compromised patient data privacy, which could limit market growth. Another challenge is the need for significant investments in infrastructure and technology to implement PACS systems, which could be a barrier for small healthcare facilities and startups.
What Are The Growth Opportunities In The Global Picture Archiving and Communication Systems (PACS) Market?
The global Picture Archiving and Communication Systems (PACS) market presents several growth opportunities, driven by the increasing adoption of digital imaging technologies, the rise of cloud-based PACS, and the growing demand for advanced imaging modalities such as magnetic resonance imaging (MRI) and positron emission tomography (PET). The integration of artificial intelligence (AI) and machine learning algorithms into PACS is also expected to drive market growth, enabling healthcare providers to analyze large amounts of imaging data and improve diagnostic accuracy.
Market Drivers
The global Picture Archiving and Communication Systems (PACS) market is driven by several factors. The following are the key drivers of the global Picture Archiving and Communication Systems (PACS) market:
Adoption of Various Strategies Among Market Players
The major companies serving the global Picture Archiving and Communication Systems (PACS) are Carestream Health, Merge Healthcare Solutions Inc, Mckesson Corp. and Ambra Health. The market players are considerably contributing to the market growth by the adoption of various strategies including mergers & acquisitions, collaborations, funding, and new product launches, to stay competitive in the market. For instance, in February 2022, Butterfly Network, a leader in point-of-care ultrasound technology, has partnered with Ambra Health, a top provider of medical image management solutions. This collaboration aims to streamline the process of integrating ultrasound data into electronic health records and other hospital systems, improving the quality and efficiency of care delivery.
Market Restraints
The global Picture Archiving and Communication Systems (PACS) market faces some challenges that may hinder its growth. These include the following:
Integration of PACS with Existing Systems
One of the main challenges facing the PACS market is the integration of PACS with existing systems, such as radiology information systems (RIS) and electronic health records (EHRs). This integration can be difficult, time-consuming, and may require a significant investment in software and training. The lack of unified standardization and archiving, as well as the need to integrate patient images with electronic medical records and health information exchange platforms, are some of the specific challenges in this regard. The integration process can also involve addressing non-standardized protocol display, interoperability, and the need for seamless management of medical images.
Opportunities
The global Picture Archiving and Communication Systems (PACS) market offers significant growth opportunities. These include the following:
Increasing Need for Storing and Sharing Medical Imaging Data
Cloud-based PACS, or picture archiving and communication system, is a modern way of storing and sharing medical imaging data. It offers several advantages, including reduced costs, increased scalability, and improved accessibility. Unlike traditional PACS, which relies on on-site hardware, cloud-based PACS is hosted off-site by a vendor. This means that the storage and features are provided by cloud-based servers, and the vendor handles the hosting and maintenance of the data. Cloud-based PACS is similar to regular PACS in that they both rely on DICOM as their underlying technology, which allows them to work with other systems just as easily as regular PACS. One of the key benefits of cloud-based PACS is its scalability, allowing healthcare providers to add resources without interruptions or a loss in the quality of service. Additionally, cloud-based PACS offers strict security measures to safeguard medical imaging data privacy and integrity, such as password-protected connections, encrypted sessions, and adherence to strict security and privacy protocols like HIPAA. For instance, in May 2023, Nandico's cloud-based SaaS PACS enabled radiologists and clinicians to view radiology scans on any device, reducing turnaround time and costs. Scans can be viewed immediately, improving patient care.
Competitive Landscape
Key Players
The global Picture Archiving and Communication Systems (PACS) market is highly competitive, with several key players. Some of the major players in the market and their market share are as follows:
- Carestream Health
- Merge Healthcare Solutions Inc
- Mckesson Corp
- Agfa-Gevaert Group
- GE Healthcare
- Siemens Healthineers
- FUJIFILM Medical Systems
- Sectra AB
- INFINITT Healthcare Co. Ltd
- Koninklijke Philips N.V.
- Others
These organizations prioritize product innovation, distribution channel expansion, and mergers and acquisitions to stay competitive.
The global Picture Archiving and Communication Systems (PACS) market's key players continually seek to stay ahead by offering new products and developments.
In April 2023, Merge Solutions received Best in KLAS 2023 awards for cardiology and hemodynamics, adding to their previous wins. Merge Cardio scores Best in KLAS for six straight years, while Merge Hemo ranks 1 for 10 years. Collaboration, partnership, and client feedback contribute to their success.
In August 2021, GE Healthcare introduced Edison True PACS, a diagnostic imaging and workflow solution aimed at addressing radiologist burnout and retirement. Available in the US, with planned rollout in other regions, it helps radiologists work efficiently and precisely while controlling capital and IT resources.
Summary of Key Findings
- The Picture Archiving and Communication Systems (PACS) market is experiencing increased demand is driven by shift towards cloud-based PACS solutions requires specialized services for migration, data security, and integration.
- The market players are considerably contributing to the market growth by the adoption of various strategies including mergers & acquisitions, collaborations, funding, and new product launches, to stay competitive in the market.
- On-premises PACS solutions are the most widely adopted, with hospitals being the primary end-users. Radiology PACS is the leading imaging modality, and standalone PACS systems dominate the market.
- The North American region is witnessing significant growth, driven by factors such as high adoption of advanced healthcare technology and the presence of key market players.
- Key players in the market include Carestream Health, Merge Healthcare Solutions Inc, Mckesson Corp, Agfa-Gevaert Group, GE Healthcare, Siemens Healthineers, and others.
Future Outlook
- Positive outlook for the global Picture Archiving and Communication Systems (PACS) market with significant growth potential in the North American region.
- Government initiatives promoting the use of natural ingredients and increasing consumer awareness of health benefits are driving market expansion.
- The market may face challenges from fluctuations in raw material prices and consumer preferences shifting towards wireless alternatives.
- Key firms must focus on product innovation, expanding market reach, and maintaining competitive pricing to stay ahead of the competition. Additionally, investing in sustainable sourcing and production practices may provide a competitive edge in the market.
How CXOs Can Benefit from the Credence Research Picture Archiving and Communication Systems (PACS) Networks Market Report
The Credence Research Picture Archiving and Communication Systems (PACS) Networks Market Report provides CXOs with a comprehensive overview of the market, including:
- Market size and growth forecast: The report provides detailed estimates of the global Picture Archiving and Communication Systems (PACS) networks market size, segmented by deployment type, end-users, imaging modalities, functionality, mode of access,Type of PACS, and region. It also includes forecasts for the market through 2032, based on key trends and drivers.
- Market segmentation: The report segments the Picture Archiving and Communication Systems (PACS) networks market by deployment type, end-users, imaging modalities, functionality, mode of access,Type of PACS, and region. The increasing demand for advanced solutions is driven. This segmentation provides CXOs with a granular understanding of the market and the opportunities in each segment.
- Competitive landscape: The report profiles the key players in the Picture Archiving and Communication Systems (PACS) networks market and provides insights into their strategies, product offerings, and financial performance. This information can help CXOs to identify and assess their competition.
- Key trends and drivers: The report identifies and analyzes the key trends and drivers that are shaping the Picture Archiving and Communication Systems (PACS) networks market. This information can help CXOs to make informed decisions about their investments and strategies.
CXOs can use the insights from the Credence Research Picture Archiving and Communication Systems (PACS) Networks Market Report to:
- Identify growth opportunities: The report can help CXOs to identify new growth opportunities in the Picture Archiving and Communication Systems (PACS) networks market. For example, the report identifies the growing demand for Picture Archiving and Communication Systems (PACS) networks from cloud computing providers and telecom companies as a key opportunity.
- Make informed investment decisions: The report can help CXOs to make informed investment decisions about Picture Archiving and Communication Systems (PACS) networks. For example, the report provides insights into the key factors to consider when evaluating Picture Archiving and Communication Systems (PACS) providers and selecting Picture Archiving and Communication Systems (PACS) solutions.
- Develop competitive strategies: The report can help CXOs to develop competitive strategies for their Picture Archiving and Communication Systems (PACS) networks businesses. For example, the report identifies the key strategies that Picture Archiving and Communication Systems (PACS) providers are using to differentiate themselves from their competitors.
- Track market developments: The report can help CXOs to track market developments and stay ahead of the curve. For example, the report provides insights into the latest trends and innovations in the Picture Archiving and Communication Systems (PACS) networks market.
Overall, the Credence Research Picture Archiving and Communication Systems (PACS) Networks Market Report is a valuable resource for CXOs who are looking to gain a deeper understanding of the market and identify opportunities for growth.
Segmentation
- By Deployment Type:
- On-Premises PACS
- Cloud-Based PACS
- By Component:
- Hardware
- Software
- Services
- By Imaging Modality:
- X-Ray PACS
- Computed Tomography (CT) PACS
- Magnetic Resonance Imaging (MRI) PACS
- Ultrasound PACS
- Nuclear Medicine PACS
- By End-User:
- Hospitals
- Diagnostic Imaging Centers
- Ambulatory Surgical Centers (ASCs)
- Research and Academic Institutes
- By Type of PACS:
- Radiology PACS
- Cardiology PACS
- Orthopedic PACS
- Ophthalmology PACS
- Dental PACS
- By Mode of Access:
- Web-Based/Cloud PACS
- Standalone/Local PACS
- By Functionality:
- Integrated PACS
- Standalone PACS
- By Region
- North America
- The U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
- North America
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Adoption of Digital Imaging Technologies
Healthcare providers are increasingly shifting from analog to digital imaging, which requires robust PACS solutions for efficient storage, retrieval, and sharing of medical images. This transition is a key factor driving the expansion of the PACS market.
Growth of Cloud-Based PACS Solutions
The scalability, flexibility, and cost-effectiveness of cloud-based PACS are leading to rapid adoption, especially among facilities seeking to reduce IT overhead and improve remote access to imaging data. This trend is accelerating market growth, particularly in emerging regions.
Integration with Electronic Health Records (EHRs)
The need for seamless integration of imaging data with EHRs and other health IT systems is pushing healthcare organizations to invest in advanced PACS platforms, enhancing workflow efficiency and clinical decision-making.
Rising Medical Imaging Volumes
Increasing prevalence of chronic diseases and an aging population are driving up the number of diagnostic imaging procedures, necessitating advanced PACS solutions to manage the growing volume and complexity of medical images.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the global Picture Archiving and Communication Systems (PACS) market?
What is the expected growth rate of the Picture Archiving and Communication Systems (PACS) market between 2024 and 2032?
Which segment is leading the market share in terms of Picture Archiving and Communication Systems (PACS) Types?
Which Functionality segment governs the demand for Picture Archiving and Communication Systems (PACS)s in the world?
Who are the major players in the global Picture Archiving and Communication Systems (PACS) market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-User
- 1.2.1 Hospitals
- 1.2.2 Diagnostic Imaging Centers
- 1.2.3 Ambulatory Surgical Centers (ASCs)
- 1.2.4 Research and Academic Institutes
- 1.3 By Component
- 1.3.1 Hardware
- 1.3.2 Software
- 1.3.3 Services
- 1.4 By Deployment Type
- 1.4.1 On-Premises PACS
- 1.4.2 Cloud-Based PACS
- 1.5 By Imaging Modality
- 1.5.1 X-Ray PACS
- 1.5.2 Computed Tomography (CT) PACS
- 1.5.3 Magnetic Resonance Imaging (MRI) PACS
- 1.5.4 Ultrasound PACS
- 1.5.5 Nuclear Medicine PACS
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 3151.2 Million → 2032: USD 5,696.6 Million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Picture Archiving and Communication Systems (PACS) Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Picture Archiving and Communication Systems (PACS) Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Picture Archiving and Communication Systems (PACS) Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Picture Archiving and Communication Systems (PACS) Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Picture Archiving and Communication Systems (PACS) Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Picture Archiving and Communication Systems (PACS) Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Picture Archiving and Communication Systems (PACS) Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Picture Archiving and Communication Systems (PACS) Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 3151.2 Million → 2032: USD 5,696.6 Million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Picture Archiving and Communication Systems (PACS) Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-User - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hospitals
- 12.3.7.2 Diagnostic Imaging Centers
- 12.3.7.3 Ambulatory Surgical Centers (ASCs)
- 12.3.7.4 Research and Academic Institutes
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Component - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Hardware
- 12.4.7.2 Software
- 12.4.7.3 Services
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Deployment Type - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 On-Premises PACS
- 12.5.7.2 Cloud-Based PACS
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Imaging Modality - Market Size and Forecast, 2023-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2023-2032
- 12.6.4 Volume Forecast, 2023-2032
- 12.6.5 Base-Year Market Share, 2023
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 X-Ray PACS
- 12.6.7.2 Computed Tomography (CT) PACS
- 12.6.7.3 Magnetic Resonance Imaging (MRI) PACS
- 12.6.7.4 Ultrasound PACS
- 12.6.7.5 Nuclear Medicine PACS
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Picture Archiving and Communication Systems (PACS) End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Picture Archiving and Communication Systems (PACS) Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Share, 2023
- 14.2 Regional Market Forecast, 2023-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Picture Archiving and Communication Systems (PACS) Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Picture Archiving and Communication Systems (PACS) Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Carestream Health
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Merge Healthcare Solutions Inc
- 18.4 McKesson Corp
- 18.5 Agfa-Gevaert Group
- 18.6 GE Healthcare
- 18.7 Siemens Healthineers
- 18.8 FUJIFILM Medical Systems
- 18.9 Sectra AB
- 18.10 INFINITT Healthcare Co. Ltd
- 18.11 Koninklijke Philips N.V.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

