
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
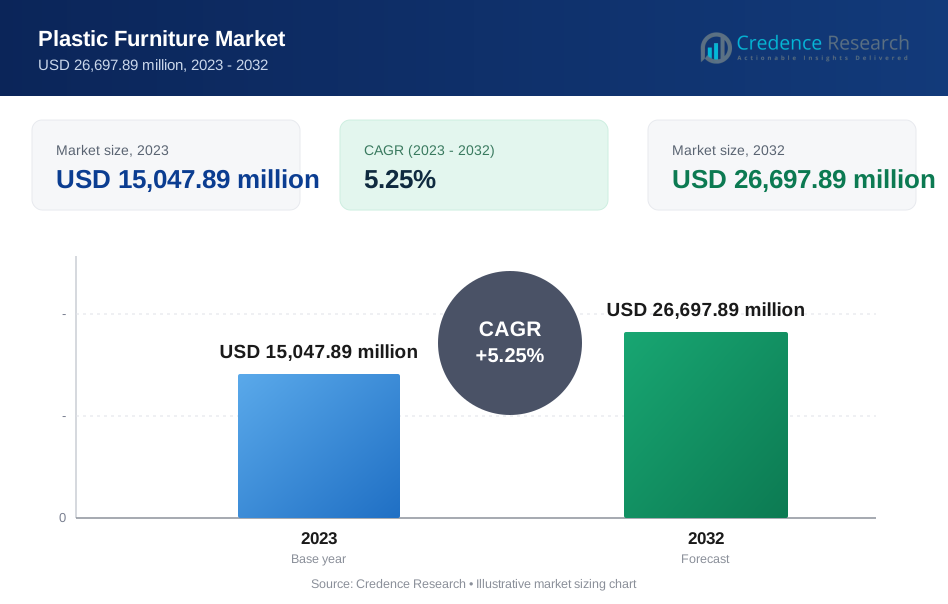
| Plastic Furniture Market Size 2023 | USD 15,047.89 million |
| Plastic Furniture Market, CAGR | 5.25% |
| Plastic Furniture Market Size 2032 | USD 26,697.89 million |
Market Overview:
The plastic furniture market is projected to grow from USD 15,047.89 million in 2023 to USD 26,697.89 million by 2032, at a compound annual growth rate (CAGR) of 5.25%. This growth is driven by several factors, including the increasing preference for lightweight, durable, and cost-effective furniture. Plastic furniture’s versatility in design and advancements in materials and manufacturing technologies have increased its appeal.
The industry’s growth is also fuelled by a focus on sustainability, with manufacturers using recycled materials, aligning with global sustainability goals. This eco-friendly approach appeals to environmentally conscious consumers, boosting plastic furniture’s demand in residential and commercial sectors.
The expanding real estate and construction sectors worldwide have also driven demand for plastic furniture. Rapid urbanization and population growth necessitate affordable and versatile furniture solutions. Plastic furniture, with its lightweight and easy maintenance, meets these needs and is often preferred by builders and designers.
The shift towards remote work and flexible office setups, accelerated by the COVID-19 pandemic, has increased the demand for ergonomic and adaptable furniture. Plastic furniture offers the required flexibility and functionality, contributing to its increasing adoption in home offices and commercial workspaces.
Emerging markets in Asia-Pacific, Latin America, and Africa present lucrative opportunities for market expansion due to rapid urbanization and infrastructure development. However, the market faces challenges such as fluctuating raw material prices, regulatory changes related to plastic usage, and competition from alternative materials. To maintain competitiveness, market players are investing in research and development, adopting sustainable practices, and exploring new market segments. Additionally, emerging markets in Asia-Pacific, Latin America, and Africa are witnessing rapid urbanization and infrastructure development, presenting lucrative opportunities for market expansion in the coming years. However, the market also faces challenges such as fluctuating raw material prices, regulatory changes related to plastic usage, and competition from alternative materials. To maintain competitiveness and capitalize on growth opportunities, market players are investing in research and development, adopting sustainable practices, and exploring new market segments.
Market Drivers:
Increased Focus on Sustainability:
The plastic furniture market is being driven by a growing emphasis on sustainability across industries. As environmental concerns continue to escalate, consumers and businesses alike are seeking alternatives to traditional materials like wood and metal. Plastic furniture offers several sustainability advantages, including recyclability, durability, and reduced environmental impact during production. Manufacturers are responding to this demand by developing innovative recycled plastic materials and eco-friendly production processes. For instance, a survey conducted by the British Furniture Confederation found that two-thirds of respondents stated that sustainability was a top three management priority. This shift towards sustainability is not only driven by consumer preferences but also regulatory pressures and corporate responsibility initiatives, further propelling the growth of the plastic furniture market.
Advancements in Material Technology:
Another key driver of the plastic furniture market is continuous advancements in material technology. Manufacturers are constantly improving the quality, strength, and aesthetic appeal of plastic furniture materials. High-performance plastics such as polypropylene, polyethylene, and polycarbonate are being used to create furniture that is lightweight, weather-resistant, and suitable for both indoor and outdoor use. These materials offer superior durability, color retention, and resistance to fading, cracking, and warping compared to traditional materials. Additionally, developments in molding techniques and design capabilities enable the creation of intricate and stylish furniture designs, attracting a broader range of consumers to the plastic furniture segment. For instance, a review on the technological and material developments in additive manufacturing using polymers highlights significant progress due to technological innovations
Changing Consumer Lifestyles and Preferences:
Shifts in consumer lifestyles and preferences are also driving the plastic furniture market. Modern consumers prioritize convenience, versatility, and affordability when choosing furniture for their homes, offices, or outdoor spaces. Plastic furniture aligns with these preferences by offering easy-to-clean surfaces, lightweight portability, and a wide range of designs to suit various décor styles. Moreover, the increasing trend of outdoor living spaces and the rise of compact urban dwellings have boosted the demand for functional and space-saving furniture solutions, where plastic furniture excels. As consumers seek value-for-money options without compromising on quality and aesthetics, plastic furniture emerges as a compelling choice in today's dynamic market landscape.
Expansion of Online Retail Channels:
The proliferation of online retail channels has significantly contributed to the growth of the plastic furniture market. E-commerce platforms offer consumers a convenient and hassle-free shopping experience, allowing them to browse a vast selection of plastic furniture options, compare prices, read reviews, and make informed purchasing decisions from the comfort of their homes. This accessibility has expanded the reach of plastic furniture manufacturers and suppliers, enabling them to target a global audience and penetrate new market segments. Furthermore, digital marketing strategies, including targeted advertising, social media promotions, and influencer collaborations, have played a pivotal role in creating awareness and driving demand for plastic furniture products among diverse consumer demographics.
Market Trends
Increased Demand for Eco-Friendly Materials:
In recent years, the plastic furniture market has witnessed a notable shift towards eco-friendly materials. Consumers are increasingly seeking products made from recycled plastics or biodegradable materials, driven by growing environmental consciousness. Manufacturers are responding by developing innovative solutions that reduce environmental impact without compromising on quality or durability.
Growth in Outdoor Furniture Segment:
The outdoor furniture segment within the plastic furniture market has experienced significant growth. This trend can be attributed to factors such as the popularity of outdoor living spaces, increased leisure activities, and the durability of plastic furniture in outdoor environments. Consumers are looking for weather-resistant, low-maintenance options, making plastic furniture a preferred choice for gardens, patios, and poolside areas. For instance, according to a survey conducted by the International Casual Furnishings Association in January 2021, nearly 6 in 10 Americans (58%) plan to buy at least one new piece of furnishing accessories for their lawn living spaces.
Emphasis on Design and Customization:
Another notable trend is the emphasis on design and customization in the plastic furniture market. Consumers are seeking unique and stylish furniture pieces that complement their aesthetic preferences and interior or exterior spaces. Manufacturers are offering a wide range of designs, colors, and finishes to cater to diverse customer tastes, enhancing the overall appeal of plastic furniture. For instance, the analysis of the plastic furniture industry, ITALICA, a furniture provider, announced the launch of Phoenix Folding Chair, a plastic furniture, in November 2023, which is lightweight and portable.
Technological Advancements and Innovation:
Technological advancements are driving innovation within the plastic furniture market. Manufacturers are leveraging advanced materials, production techniques, and design technologies to create furniture that is not only aesthetically pleasing but also functional and durable. This includes features such as UV resistance, enhanced structural integrity, and ergonomic designs, meeting the evolving needs of consumers.
Growing Popularity in Commercial and Hospitality Sectors:
The use of plastic furniture is gaining popularity in the commercial and hospitality sectors. Businesses such as restaurants, cafes, hotels, and public spaces are opting for plastic furniture due to its versatility, cost-effectiveness, and ease of maintenance. Additionally, the lightweight nature of plastic furniture makes it ideal for spaces that require frequent rearrangement or transportation.
Market Restraints and Challenges:
Environmental Concerns and Sustainability Challenges:
Plastic furniture faces significant market restraints due to growing environmental consciousness and concerns about sustainability. Consumers and regulatory bodies are increasingly prioritizing eco-friendly alternatives, leading to a shift away from traditional plastic products. The plastic furniture market must navigate these challenges by embracing sustainable practices, such as using recycled materials and developing biodegradable options.
Durability and Quality Perception:
Another challenge for the plastic furniture market is the perception of durability and quality compared to alternative materials like wood or metal. While advancements in plastic technology have improved the strength and longevity of plastic furniture, some consumers still perceive it as less durable or of lower quality. Overcoming this perception requires manufacturers to focus on product innovation, using high-quality materials, and implementing rigorous testing to ensure durability and longevity.
Price Competitiveness and Cost Factors:
Price competitiveness is a significant restraint in the plastic furniture market, especially when compared to lower-cost alternatives such as conventional wooden furniture or low-priced imports. Cost factors such as raw material prices, manufacturing expenses, and transportation costs can impact the final price of plastic furniture, making it challenging to compete in price-sensitive markets. To address this challenge, companies must optimize their production processes, explore cost-effective sourcing options, and streamline distribution channels to offer competitive pricing without compromising on quality.
Aesthetics and Design Preferences:
Consumer preferences for aesthetics and design also influence the plastic furniture market. While plastic offers versatility in terms of design possibilities, some consumers still prefer the natural look and feel of wood or the sleekness of metal furniture. Meeting diverse design preferences requires continuous innovation in product design, offering a range of styles, colors, and finishes that appeal to different customer segments.
Competition from Alternative Materials and Product Substitutes:
The plastic furniture market faces fierce competition from alternative materials and product substitutes, such as bamboo furniture, rattan furniture, and composite materials. These alternatives often tout eco-friendly credentials, durability, and unique aesthetics, posing a challenge to traditional plastic furniture. To remain competitive, plastic furniture manufacturers must differentiate their offerings by highlighting unique features, such as weather resistance, easy maintenance, and customizable designs. Building brand loyalty and emphasizing the benefits of plastic furniture over competing materials can help mitigate the impact of alternative products.
Key Players:
- IKEA
- Polywood
- Keter
- Lifetime Products
- Nilkamal Limited
- Patio Renaissance
- Trex Company
- Ashley Furniture Industries
- Home Depot
- Herman Miller
Recent Developments:
- In June 2022, Tramontina USA partnered with Voice of the Oceans on a mission toward a brighter future. Their collaboration aimed to raise awareness about the issue of ocean plastics and explore novel strategies to address this pressing environmental challenge.
Segmentation Analysis:
By Type:
Firstly, the segmentation by type categorizes plastic furniture into different product types such as chairs, tables, cabinets, and others. Each type caters to specific needs and preferences of customers, ranging from household to commercial use. For instance, chairs may include dining chairs, office chairs, and outdoor chairs, each designed with unique features and functionalities.
By End-user:
Secondly, segmentation by end-user further refines the market by considering the target consumers of plastic furniture. This can include residential, commercial, and industrial sectors. Residential end-users primarily purchase plastic furniture for home use, while commercial end-users comprise businesses, offices, hotels, and institutions that require furniture for various purposes.
By Distribution Channel:
Thirdly, the distribution channel segmentation analyzes how plastic furniture reaches the end-users. This can include online retail, brick-and-mortar stores, direct sales, and wholesale distribution channels. With the rise of e-commerce, online retail channels have gained significant traction, offering convenience and a wide range of options to consumers.
Segments:
By Type
- Kitchen Furniture
- Living and Dining Room Furniture
- Bathroom Furniture
- Outdoor Furniture
- Other Types
By End User
- Residential
- Commercial
By Distribution Channel
- Supermarkets and Hypermarkets
- Specialty Stores
- Online
- Other Distribution Channels
By Geography:
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
Regional Analysis:
Regional Analysis of the Plastic Furniture Market:
North America stands as a prominent region in the plastic furniture market, driven by factors such as increasing consumer preference for lightweight and durable furniture solutions. The market share in this region is substantial, with key players focusing on innovation and sustainable practices to capture a larger market share. Rising environmental concerns have also led to a surge in demand for eco-friendly plastic furniture, further boosting market growth in North America.
Europe commands a considerable market share in the plastic furniture industry, characterized by a strong emphasis on design aesthetics and technological advancements. The region's stringent regulations regarding plastic waste management have propelled the adoption of recycled plastic materials in furniture manufacturing. This eco-conscious approach has resonated well with consumers, driving market expansion and competition among leading players.
Asia Pacific emerges as a rapidly growing market for plastic furniture, fueled by the region's booming construction and real estate sectors. Countries like China, India, and Japan are witnessing robust demand for affordable yet stylish furniture solutions, driving manufacturers to innovate and diversify their product offerings. The market share in Asia Pacific is poised for significant growth, driven by urbanization, changing consumer lifestyles, and increasing disposable incomes.
Latin America and Middle East & Africa also play pivotal roles in the plastic furniture market, albeit with distinct market dynamics. In Latin America, rising urbanization and the shift towards modern living spaces have boosted the demand for plastic furniture, especially in countries like Brazil and Mexico. Meanwhile, in the Middle East & Africa region, infrastructure development projects and hospitality sector expansions are driving the demand for durable and weather-resistant plastic furniture solutions.
Future Outlook:
- The plastic furniture market is expected to witness significant growth in the coming years due to increasing demand for lightweight, durable, and cost-effective furniture solutions.
- Technological advancements in the manufacturing of plastic furniture, such as the use of recycled materials and innovative designs, will drive market expansion.
- The growing trend of eco-friendly and sustainable products will boost the demand for recyclable and biodegradable plastic furniture options.
- Emerging markets in Asia-Pacific, Latin America, and Africa are anticipated to contribute significantly to the growth of the plastic furniture market, driven by urbanization and rising disposable incomes.
- Increasing awareness about the benefits of plastic furniture, such as resistance to water, chemicals, and weather conditions, will further propel market growth.
- The shift towards online retail channels and e-commerce platforms will provide manufacturers with broader reach and access to a global customer base, stimulating market expansion.
- Collaborations between furniture designers, manufacturers, and material suppliers will lead to the development of innovative and stylish plastic furniture designs, catering to changing consumer preferences.
- Government initiatives promoting the use of recycled materials and sustainable practices in manufacturing will create favorable conditions for the plastic furniture market's growth.
- Rising demand for lightweight and portable furniture solutions in the hospitality, outdoor recreation, and commercial sectors will drive the adoption of plastic furniture products.
- Overall, the plastic furniture market is poised for robust growth in the foreseeable future, driven by technological advancements, sustainability trends, and expanding market opportunities worldwide.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increased Focus on Sustainability
Growing environmental concerns and regulatory pressures are pushing manufacturers to use recycled plastics and eco-friendly production processes, making plastic furniture more appealing to environmentally conscious consumers and businesses.
Advancements in Material Technology
Continuous improvements in high-performance plastics and manufacturing techniques have enhanced the durability, design versatility, and weather resistance of plastic furniture, expanding its suitability for both indoor and outdoor applications.
Changing Consumer Lifestyles and Preferences
Modern consumers seek lightweight, affordable, and easy-to-maintain furniture, and the rise of compact urban living and outdoor leisure spaces has increased demand for versatile plastic furniture solutions.
Expansion of Online Retail Channels
The growth of e-commerce platforms has made plastic furniture more accessible, allowing consumers to easily compare options and purchase products, which has broadened the market reach and accelerated adoption.
Growth in Construction and Real Estate Sectors
Rapid urbanization and infrastructure development, especially in emerging markets, are driving demand for cost-effective and portable furniture solutions, with plastic furniture meeting the needs of new residential and commercial spaces.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
How much will the plastic furniture market grow?
What’s driving this growth?
How has remote work affected the market?
What challenges does the market face?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Kitchen Furniture
- 1.2.2 Living and Dining Room Furniture
- 1.2.3 Bathroom Furniture
- 1.2.4 Outdoor Furniture
- 1.2.5 Other Types
- 1.3 By End User
- 1.3.1 Residential
- 1.3.2 Commercial
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 15,047.89 million → 2032: USD 26,697.89 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Plastic Furniture Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Plastic Furniture Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Plastic Furniture Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Plastic Furniture Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Plastic Furniture Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Plastic Furniture Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Plastic Furniture Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Plastic Furniture Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 15,047.89 million → 2032: USD 26,697.89 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Plastic Furniture Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Kitchen Furniture
- 12.3.7.2 Living and Dining Room Furniture
- 12.3.7.3 Bathroom Furniture
- 12.3.7.4 Outdoor Furniture
- 12.3.7.5 Other Types
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End User - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Residential
- 12.4.7.2 Commercial
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Plastic Furniture End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Plastic Furniture Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Share, 2023
- 14.2 Regional Market Forecast, 2023-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Plastic Furniture Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Plastic Furniture Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 IKEA
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Polywood
- 18.4 Keter
- 18.5 Lifetime Products
- 18.6 Nilkamal Limited
- 18.7 Patio Renaissance
- 18.8 Trex Company
- 18.9 Ashley Furniture Industries
- 18.10 Home Depot
- 18.11 Herman Miller
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

