
Market Overview:
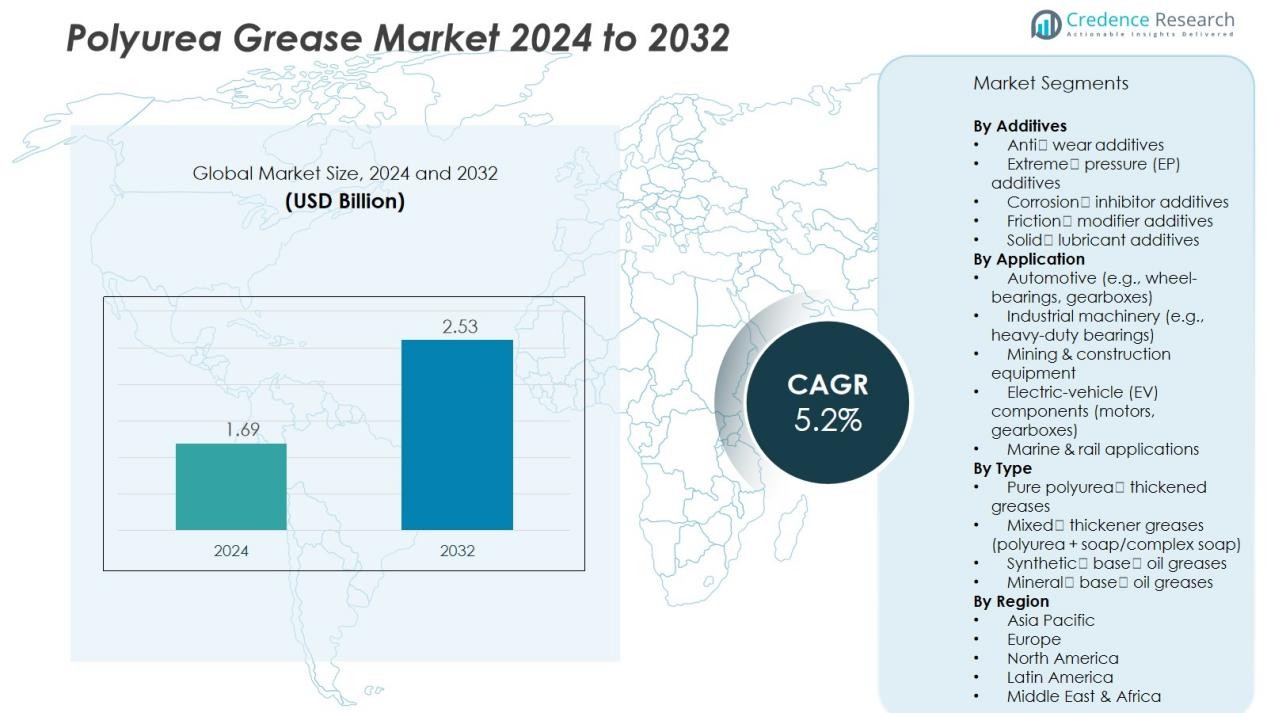
The Polyurea Grease Market size was valued at USD 1.69 billion in 2024 and is anticipated to reach USD 2.53 billion by 2032, at a CAGR of 5.2% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Polyurea Grease Market Size 2024 | USD 1.69 Billion |
| Polyurea Grease Market, CAGR | 5.2% |
| Polyurea Grease Market Size 2032 | USD 2.53 Billion |
Key drivers of the polyurea grease market include the growing need for lubricants that offer superior thermal stability, wear resistance, and water resistance in demanding environments. The automotive sector, including electric vehicles, and industrial applications, particularly in mining and heavy machinery, are expected to be significant contributors to market expansion. Additionally, the rising focus on minimizing equipment downtime, lowering maintenance costs, and meeting regulatory standards related to lubricant performance and environmental impact is propelling the adoption of polyurea-based greases.
Regionally, North America dominates the polyurea grease market, driven by a robust industrial base, strong automotive and manufacturing sectors, and stringent regulations that promote the use of advanced lubricants. The Asia-Pacific region is projected to experience the highest growth, fueled by rapid industrialization, infrastructure development, and expanding automotive and construction activities in countries like China, India, and Japan. Europe, Latin America, and the Middle East & Africa are also expected to witness moderate growth during the forecast period.
Market Insights:
- The Polyurea Grease Market was valued at USD 1.69 billion in 2024 and is expected to reach USD 2.53 billion by 2032, growing at a CAGR of 5.2% during the forecast period.
- North America holds the largest market share of approximately 40%, driven by a robust industrial base, strong automotive and manufacturing sectors, and strict environmental regulations that favor advanced lubricants like polyurea greases.
- Europe follows with a market share of around 30%, supported by its automotive manufacturing strength, focus on sustainability, and well-established industrial maintenance culture that prioritizes long-life lubricants.
- The Asia-Pacific region is the fastest-growing market, holding nearly 20% of the global share, fueled by rapid industrialization, rising automotive production, and expanding infrastructure projects in countries like China, India, and Japan.
- By segment, polyurea greases in automotive applications dominate, with a significant share in wheel bearings and gearboxes, while industrial machinery and mining applications also account for a substantial portion of the market share.
 Market Drivers:
Demand for High-Performance Lubricants
The Polyurea Grease Market is experiencing growth driven by the increasing demand for high-performance lubricants. Industries such as automotive, manufacturing, and mining require lubricants that offer superior thermal stability, wear resistance, and water resistance. Polyurea-based greases meet these requirements, making them ideal for applications in extreme conditions. This demand is particularly strong in industries dealing with high-speed machinery and harsh environments, where traditional lubricants may fail to deliver the necessary performance.
- For Instance, For industrial and some automotive applications, Shell produces polyurea (diurea) greases, such as the Shell Gadus S3 T100 series, which are designed for superior high-temperature and long-life performance.
Advancements in Automotive and Industrial Applications
The automotive sector, including the rise of electric vehicles, is a significant driver for the Polyurea Grease Market. Polyurea greases are being increasingly used in electric vehicle (EV) applications due to their superior performance in high-temperature environments and their ability to extend the life of key components. The adoption of polyurea grease in electric motors, gearboxes, and other automotive parts is expanding. Similarly, in industrial applications such as mining and construction, the shift towards advanced lubricants like polyurea is improving the longevity and efficiency of machinery.
- For Instance, SKF offers polyurea-thickened greases like SKF LGHP 2 and LGHQ 2, which are designed for electric motor applications and provide high thermal and mechanical stability, long life, and low noise properties suitable for electric vehicle powertrains.
Focus on Reducing Maintenance and Downtime Costs
A growing emphasis on reducing operational downtime and maintenance costs is fueling the adoption of polyurea grease. Polyurea-based lubricants have a longer lifespan than traditional greases, reducing the frequency of replacements and the need for machine servicing. This advantage leads to significant cost savings for businesses, especially in sectors where equipment downtime can lead to substantial losses. The increased reliability of polyurea grease enhances operational efficiency and reduces maintenance efforts, making it a preferred choice for many industries.
Stringent Regulatory Standards and Sustainability Focus
The Polyurea Grease Market is also driven by stringent regulatory standards and a growing focus on sustainability. Governments worldwide are implementing stricter environmental regulations that push industries to adopt more sustainable and effective lubricants. Polyurea greases, which offer better efficiency and lower environmental impact compared to conventional greases, are being adopted to meet these standards. Their ability to perform in various conditions while adhering to environmental guidelines makes them an attractive option for companies seeking to comply with regulations.
Market Trends:
Expansion of Preference for Polyurea Grease Over Traditional Lithium Grease
The Polyurea Grease Market reports a clear shift in end‑user preference toward polyurea‑based formulations from conventional lithium‑based greases thanks to superior thermal stability, oxidation resistance and service life. It is winning favour in sectors that involve high temperatures, heavy loads and wet conditions, such as automotive wheel‑bearings, electric motors and heavy‑duty industrial equipment. Manufacturers are offering formulations tailored for life‑lubrication scenarios where extended intervals between maintenance support cost savings and operational efficiency. This transition creates opportunity for producers willing to invest in product development and brand positioning. The move also pressures older grease technologies to evolve or cede market share in more demanding applications.
- For instance, in electric motor bearings used in industrial drives, it has been demonstrated in various case studies that adopting a polyurea grease engineered for high-temperature operation can significantly increase bearing life under continuous high-temperature service conditions, such as 100°C.
Advances in Formulation Technology and Application‑Specific Customisation
The Polyurea Grease Market is seeing innovation in formulation chemistry to meet increasingly stringent performance criteria and sector‑specific demands. Researchers and manufacturers enhance thickener systems, additive packages and base‑oil blends to achieve improved low‑temperature start‑up behaviour, enhanced water resistance or compatibility with electric vehicle components. These innovations enable use of polyurea greases in emerging applications such as e‑motors, renewable‑energy equipment and precision manufacturing systems. It also supports differentiation and premium pricing strategies across segments. The result sees companies accelerating development cycles and marketing advanced product grades for targeted niches.
- For Instance, Shell produces advanced synthetic polyurea greases, including Shell Gadus S5 T460 and Shell Stamina EP2, which are designed for long life and superior high-temperature performance compared to conventional lithium-soap greases.
Market Challenges Analysis:
High Raw-Material and Manufacturing Costs Pose Entry Barriers
The Polyurea Grease Market faces significant challenges related to raw-material and manufacturing expenses. It involves the use of specialized thickeners, additives, and base oils, which often come at a higher cost and face supply constraints. These cost pressures can limit adoption in cost-sensitive sectors or regions where users prefer more affordable conventional greases. The lack of economies of scale in some manufacturing operations further amplifies the cost disadvantage for smaller producers. Additionally, the higher upfront investment required for the development and application of polyurea greases reduces the ease of market entry, which hinders broader market expansion.
Compatibility, Awareness, and Supply Chain Stability Present Adoption Risks
The market also struggles with compatibility issues with existing lubricants, limited awareness among end users, and supply chain instability. Polyurea greases may not always perform optimally when used in systems designed for other thickener types, which can lead to hesitation among potential adopters. Many end-users are unfamiliar with the performance advantages of polyurea greases and are reluctant to make the switch without proven results. Furthermore, supply disruptions and fluctuations in the availability of petrochemical feedstocks add unpredictability to raw-material procurement and pricing. These factors combine to increase perceived risks, slowing adoption despite the clear performance benefits offered by polyurea greases.
Market Opportunities:
Growth Through Expansion in Emerging Economies and New Applications
The Polyurea Grease Market presents substantial opportunity via rapid industrialisation in emerging economies. Demand in regions such as Asia‑Pacific and Latin America is rising due to increased manufacturing, construction and infrastructure activity. Manufacturers can target these markets by offering formulations tailored for cost‑sensitive customers, boosting uptake in segments that traditionally relied on conventional greases. It also allows players to diversify geographically and reduce dependence on mature markets. By aligning product development with regional specifications and regulations, companies can gain early‑mover advantage.
Innovation in Formulation and Service‑Life Enhancement as Value Levers
There lies significant potential in the development of next‑generation formulations that deliver longer service life and superior performance under extreme conditions. The Polyurea Grease Market can benefit from greases engineered for electric‑vehicle motors, wind‑turbine bearings and heavy‑duty mining equipment, where maintenance intervals and operational reliability matter most. Providers can establish premium pricing by emphasising durability, thermal stability and water resistance. It also opens collaboration opportunities with OEMs seeking customised lubrication solutions, which strengthens value‑chain integration and creates differentiated offerings in a competitive landscape.
Market Segmentation Analysis:
By Additives
The Polyurea Grease Market divides additive usage into categories such as anti‑wear agents, extreme‑pressure (EP) additives, corrosion inhibitors, and solid lubricants. It uses anti‑wear additives to protect metal surfaces under repeated stress while EP additives enhance load‑carrying capability in heavy‑duty applications. Corrosion inhibitors help prevent rust in moist or marine environments, broadening the grease’s suitability. Solid lubricants contribute during extreme friction or high‑temperature exposure by embedding materials like graphite or molybdenum disulfide. Manufacturers tailor additive packages to match specific performance demands and differentiate products across service grades.
- For Instance, Certain specialized formulations, such as those used for high-performance polymers and industrial sealants, are designed to maintain consistency across a broad temperature range from -40 to 150 degrees Celsius, enabling stable performance in diverse environments.
By Type
The market segments by type focus on thickener systems and base‑oil chemistry. It includes pure polyurea‑thickened greases, mixed‑thickener greases (polyurea combined with soap or complex soap systems), synthetic‑base oil grades and mineral‑base oil grades. Pure polyurea types dominate high‑temperature, long‑life, high‑speed applications due to superior thermal and mechanical stability. Mixed‑thickener types serve cost‑sensitive or transitional applications where compatibility with existing systems matters. Synthetic‑base oil varieties command premium pricing while mineral‑base options address standard load/temperature regimes.
- For Instance, Lubrizol's urea-derivative thickeners have shown improved bearing life and high-temperature stability. Urea-derivative greases generally provide superior thermal resistance and oxidation stability compared to lithium greases, suitable for continuous use up to 180°C or higher in specific formulations.
By Application
The application segmentation covers automotive, industrial machinery, mining & construction, electric vehicles (EVs), and other sectors such as marine and rail. It targets the automotive sector for wheel bearings, joints and gearboxes where long service intervals reduce maintenance. It serves industrial machinery and mining for heavy‑duty bearings, conveyors and high‑temperature environments. For EVs, it addresses motor/gearbox lubricant needs unique to high‑speed silent operation. Marine and rail sectors present niche but growing demand where water‑resistance and durability matter. This segmentation enables suppliers to align product design and channel strategy with end‑user requirements.
Segmentations:
By Additives
- Anti‑wear additives
- Extreme‑pressure (EP) additives
- Corrosion‑inhibitor additives
- Friction‑modifier additives
- Solid‑lubricant additives
By Type
- Pure polyurea‑thickened greases
- Mixed‑thickener greases (polyurea + soap/complex soap)
- Synthetic‑base‑oil greases
- Mineral‑base‑oil greases
By Application
- Automotive (e.g., wheel‑bearings, gearboxes)
- Industrial machinery (e.g., heavy‑duty bearings)
- Mining & construction equipment
- Electric‑vehicle (EV) components (motors, gearboxes)
- Marine & rail applications
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America - Market share close to 40%
North America holds the largest share of the market and leads in adoption of high‑performance polyurea greases. It benefits from a mature industrial base, strong automotive sector and stringent environmental regulations that drive demand for advanced lubricants. Manufacturers in the region invest heavily in research and development to tailor polyurea greases for heavy machinery, EVs and manufacturing plants. It also features a strong supply‑chain infrastructure and presence of major global players, which support product availability and innovation. The region’s end‑users increasingly prioritise maintenance reduction and equipment efficiency, favouring polyurea grease solutions. Continued replacement of conventional greases with polyurea‑based variants strengthens market growth in this geography.
Europe - Market share around 30%
Europe captures a significant portion of the market thanks to its strong automotive manufacturing and strict regulatory environment. Germany, France and the UK lead demand for high‑spec lubrication products in industrial and automotive applications. It also has a well‑established industrial maintenance culture that favours long‑life lubricants such as polyurea greases. The region’s focus on sustainability and clean‑technology adoption encourages the shift from traditional greases to more efficient alternatives. Suppliers align product features with European emissions, durability and performance standards to gain acceptance. Investment in localized manufacturing and distribution ensures that the regional market remains competitive and responsive to end‑user needs.
Asia‑Pacific & Middle East / Africa - APAC share near 20%, MEA & Latin America smaller but growing
Asia‑Pacific commands a growing share of the market due to rapid industrialisation, rising automotive production and infrastructure expansion in countries like China and India. It offers considerable opportunity for polyurea greases in mining, construction equipment and EV applications. It also faces challenges such as cost sensitivity and compatibility issues in legacy systems, but growth is strong. The Middle East and Africa region, along with Latin America, includes smaller shares but progress in petrochemicals, oil & gas and mining sectors creates demand for durable lubricants. Suppliers targeting MEA and Latin America customise offerings for harsh‑environment conditions and water‑resistance requirements. Strategic partnerships with local distributors and infrastructure investments help enhance reach and penetration in these emerging regions.
Key Player Analysis:
- Martin Lubricants
- Chevron
- Imperator
- BECHEM
- HUSK-ITT Corporation
- Lubricant Consult GmbH
- Canoil Canada Ltd.
- Schaeffer Manufacturing Co
Competitive Analysis:
The Polyurea Grease Market features a competitive landscape with prominent players such as Martin Lubricants, Chevron, Imperator, BECHEM, HUSK‑ITT Corporation, Lubricant Consult GmbH, Canoil Canada Ltd. and Schaeffer Manufacturing Co. Each company leverages R&D, proprietary thickener technology and additive packages to establish differentiation and secure market positions. Martin Lubricants emphasises contract manufacturing and custom polyurea formulations. BECHEM develops high‑spec polyurea greases for automotive and industrial segments, offering low‑noise, thermal‑stable solutions. Companies such as Chevron and Imperator deploy global supply chains and scale, while smaller specialist firms like HUSK‑ITT and Lubricant Consult focus on niche applications and targeted service‑life extension greases. It remains critical for players to enhance application support, broaden geographic reach and manage raw‑material cost pressures to sustain their competitive edge.
Recent Developments:
- In August 2025, BECHEM acquired CLC Lubricants, a US-based producer specializing in industrial oils and metalworking fluids, expanding its operational footprint in North America and establishing BECHEM’s first wholly owned production facility in the United States.
- In October 2025, Chevron expanded its partnership with Arkestro by rolling out AI-driven predictive procurement software across more business units to enhance supplier management and procurement efficiency.
Report Coverage:
The research report offers an in-depth analysis based on Additives, Type, Application and Region. It details leading Market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current Market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven Market expansion in recent years. The report also explores Market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on Market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the Market.
Future Outlook:
- The Polyurea Grease Market will expand into emerging economies where industrialisation and infrastructure build‑out increase demand for high‑performance lubricants.
- Companies will grow offerings that target electric‑vehicle motors and gearboxes, since it presents a major application area for advanced greases with high thermal and oxidation resistance.
- Firms will invest in formulation innovation to deliver greases that support longer re‑lubrication intervals, greater wear protection and improved reliability in heavy‑duty and mining equipment.
- Suppliers will emphasise customisation of additive packages and base‑oil blends to differentiate products for specific sectors including marine, rail and renewable‑energy equipment.
- The industry will shift toward sustainable, eco‑friendly polyurea greases with biodegradable or bio‑based components to meet stricter environmental regulations and customer preferences.
- Manufacturers will expand regionally by building local production, distribution and technical support in high‑growth zones to improve service levels and market penetration.
- Strategic partnerships and collaborations with OEMs will increase, enabling grease makers to integrate lubrication solutions early in equipment design and provide value‑added services.
- Digitalisation of maintenance practices will boost demand for smart greases and condition‑monitoring capabilities, allowing users to optimise lubricant life and reduce downtime.
- The market will face pressure to reduce cost per unit through scale and process improvement, enabling polyurea greases to move beyond premium segments into mainstream applications.
- Competitive intensity will rise, pushing companies to build stronger brand value, expand service portfolios and enter adjacent segments such as bearing systems and system lubrication services.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Polyurea Grease Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate (CAGR) is the Polyurea Grease Market projected to grow between 2024 and 2032?
Which Polyurea Grease Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Polyurea Grease Market?
Who are the leading companies in the Polyurea Grease Market?
Which region commanded the largest share of the Polyurea Grease Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1.69 billion → 2032: USD 2.53 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Polyurea Grease Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Polyurea Grease Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Polyurea Grease Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Polyurea Grease Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Polyurea Grease Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Polyurea Grease Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Polyurea Grease Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Polyurea Grease Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1.69 billion → 2032: USD 2.53 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Polyurea Grease Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Polyurea Grease Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Polyurea Grease Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Polyurea Grease Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

