
Market Overview
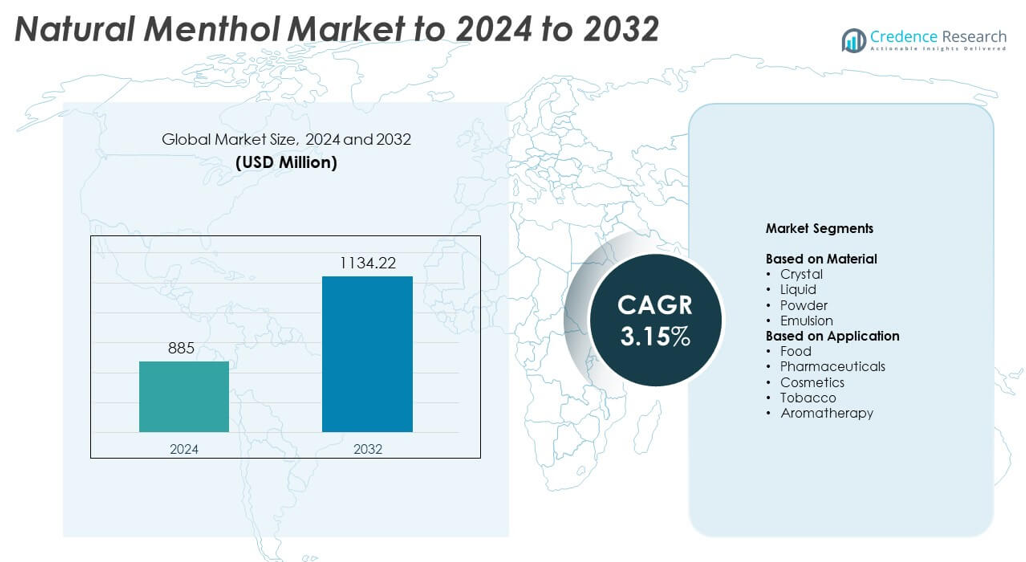
Natural Menthol Market size was valued USD 885 million in 2024 and is anticipated to reach USD 1134.22 million by 2032, at a CAGR of 3.15% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Natural Menthol Market Size 2024 | USD 885 million |
| Natural Menthol Market, CAGR | 3.15% |
| Natural Menthol Market Size 2032 | USD 1134.22 million |
The Natural Menthol Market features key players such as Takasago International Corporation, Silverline Chemicals Ltd., Symrise AG, Agson Global Pvt. Ltd., Fengle Perfume Co., Ltd., KM Chemicals, Bhagat Aromatics Ltd., Arora Aromatics Pvt. Ltd., BASF SE, and Nectar Lifesciences Ltd. These companies compete through high-purity production, strong supply capabilities, and expanding applications in pharmaceuticals, cosmetics, and food products. North America leads the global market with about 32% share in 2024, driven by strong OTC drug demand and advanced personal care manufacturing. Asia Pacific follows closely with roughly 29% share, supported by large-scale menthol extraction, strong peppermint cultivation, and rising consumer demand across regional industries.
Market Insights
- The Natural Menthol Market was valued at USD 885 million in 2024 and is projected to reach USD 1134.22 million by 2032, growing at a CAGR of 3.15% during the forecast period. • Rising demand from pharmaceuticals acts as the main driver, as menthol is widely used in lozenges, balms, inhalants, and topical pain-relief products, supported by strong OTC drug consumption across major economies. • Market trends focus on clean-label ingredients, higher adoption in cosmetic cooling formulations, and rapid growth in aromatherapy and wellness products using natural cooling agents. • Competition intensifies as leading companies expand high-purity extraction, strengthen global sourcing networks, and increase supply stability while facing cost pressure from synthetic menthol alternatives. • North America leads with 32% share due to strong pharmaceutical demand, followed by Asia Pacific at 29% supported by large-scale production; the crystal material segment dominates with about 58% share across global applications.
Market Segmentation Analysis:
By Material
The crystal category leads the material segment with about 58% share in 2024. Crystal menthol dominates because manufacturers use it widely in pharmaceuticals, oral care, and high-grade flavor blends. Strong purity, stable aroma release, and easy solubility support broad adoption across regulated sectors. Demand rises as crystal menthol meets strict quality standards for cough syrups, lozenges, and topical analgesics. Liquid and powder forms grow in food and cosmetic use, but they remain secondary due to lower concentration and limited suitability for medical applications. Emulsion formats expand slowly in personal care and aromatherapy blends.
- For instance, Takasago has the capacity to manufacture L-menthol via an asymmetric synthesis pathway at a rate of 3,000 tonnes per year.
By Application
Pharmaceuticals hold the dominant application share at roughly 39% in 2024. This segment leads because menthol supports analgesic, cooling, and decongestant effects in over-the-counter drugs. Strong uptake in lozenges, inhalants, balms, and topical creams drives consistent demand. The food category grows through use in confectionery and beverages, while cosmetics expand with rising mint-based skincare lines. Tobacco applications remain stable due to regulated flavor inclusion, and aromatherapy sees steady interest from wellness products. Pharmaceuticals maintain leadership due to strict quality needs that match natural menthol’s high purity profile.
- For instance, Warner Lambert Co. holds 144 menthol-related patents for over-the-counter medicinal and analgesic formulations.
Key Growth Drivers
Rising Pharmaceutical Demand
Pharmaceutical companies use natural menthol in cough syrups, lozenges, and pain-relief creams. Strong cooling action and high purity levels make menthol a preferred choice across regulated drug formats. Growth increases as respiratory illnesses, cold-related cases, and self-medication habits rise. Global demand for OTC remedies strengthens long-term use of natural menthol. The pharmaceutical sector continues to anchor market expansion due to strict quality needs aligned with natural menthol’s chemical stability and safety profile.
- For instance, Procter & Gamble holds 583 menthol-related patents across pharmaceutical, personal-care, and hygiene applications.
Expansion in Cosmetics and Personal Care
Cosmetic brands adopt natural menthol for skincare, oral care, and haircare lines. Cooling effects, mint fragrance, and soothing properties enhance consumer appeal across mass and premium products. Growth rises with demand for natural ingredients and clean-label formulations. Menthol’s role in irritation relief and freshness benefits supports wider use in moisturizers, cleansers, and shampoos. Personal grooming trends also raise demand for mint-based creams and gels. This shift creates strong momentum for the personal care industry.
- For instance, Kao Corp holds 192 menthol-related patents focused on cosmetics, haircare, and personal-care products.
Growth in Food and Flavor Applications
Food producers use natural menthol in confectionery, chewing gum, and beverages. The flavor market grows as brands expand mint profiles across sugar-free and functional products. Rising demand for natural flavoring ingredients boosts adoption over synthetic blends. Menthol’s stable sensory impact supports consistent taste output in large-scale production. Changing consumer preferences toward fresh and aromatic flavors further strengthen segment growth. Major producers rely on natural menthol to enhance brand differentiation within the food and beverage industry.
Key Trends and Opportunities
Shift Toward Natural and Clean-Label Ingredients
Global consumers prefer plant-based ingredients across food, cosmetics, and wellness sectors. Natural menthol benefits from this shift due to its botanical sourcing and safety profile. Brands reformulate products to replace synthetic menthol, creating new opportunities for premium lines. Clean-label trends expand use in oral care, topical balms, and functional foods. Regulatory support for natural ingredients further strengthens long-term growth. This trend positions natural menthol as a core ingredient in next-generation formulations.
- For instance, Reckitt’s Moov Cool menthol cold-therapy range in India was developed after a pain survey of over 4,000 respondents(specifically, the "Reckitt Pain India DCG Demand Survey" conducted in December 2021) and is sold in multiple menthol-based SKUs, including 10 g and 20 g gels plus 15 g and 35 g sprays that start cooling pain in approximately 15 seconds.
Innovation in Aromatherapy and Wellness Products
Aromatherapy gains traction through stress-relief, relaxation, and home fragrance demand. Natural menthol delivers strong cooling and respiratory-ease effects that support new product launches. Growth rises in diffusers, essential-oil blends, and wellness balms. Wellness brands use menthol to expand calming formulations and functional inhalers. Rising consumer interest in personal care rituals opens room for premium aromatherapy ranges. The wellness sector creates steady opportunity for high-purity natural menthol producers.
- For instance, Young Living specifies that producing a single 15 ml bottle of Peppermint essential oil for aromatherapy requires steam distillation of about 1 pound of peppermint leaves and flowering tops.
Expansion of Menthol-Infused Functional Products
Brands integrate menthol into sports recovery gels, herbal patches, toothpastes, and cold-relief strips. Functional product categories grow as consumers seek targeted benefits such as cooling, soothing, and pain relief. Food and beverage brands explore menthol in energy mints and refreshing drinks. Evolving lifestyle trends push demand for multi-use products with quick action and natural profiles. This expansion broadens menthol’s reach across diverse consumer segments.
Key Challenges
Supply Limitations and Crop Sensitivity
Natural menthol relies on mint crops that face weather risk, low yield phases, and disease exposure. Supply variability raises raw material prices and squeezes margins for producers. Seasonal fluctuations disrupt steady output, challenging companies that depend on consistent availability. Farmers require stable climatic conditions for high-quality peppermint harvests. These factors create uncertainty for long-term supply planning and export commitments.
Competition from Synthetic Menthol
Synthetic menthol offers stable pricing, large-scale output, and wide industrial use. Many manufacturers prefer synthetic versions for cost control, reducing growth for natural menthol in some sectors. High purity grades of synthetic menthol intensify competition in pharmaceuticals and personal care. Price gaps between natural and synthetic grades also discourage mass-market adoption. This challenge pressures natural menthol producers to improve efficiency and secure premium-focused demand.
Regional Analysis
North America
North America holds about 32% share in the Natural Menthol Market in 2024. Demand rises as pharmaceutical companies increase use of menthol in cough remedies, lozenges, and topical analgesics. Strong consumption of mint-based oral care and cosmetic products also supports growth. The United States leads due to advanced OTC drug manufacturing and steady demand for natural flavoring ingredients. Expanding clean-label trends and higher adoption in personal wellness items boost long-term use. The region maintains steady growth through strong retail distribution and high product standard requirements.
Europe
Europe accounts for nearly 27% share of the Natural Menthol Market in 2024. Adoption remains strong across pharmaceuticals, confectionery, and personal care products regulated under strict quality frameworks. Germany, the United Kingdom, and France lead consumption due to demand for natural cooling agents in lozenges and skincare lines. Growth also rises from expanding mint-based confectionery and sugar-free products. The region benefits from established flavor houses and advanced cosmetic manufacturing. Clean-label preferences and rising interest in aromatherapy strengthen natural menthol’s position across European industries.
Asia Pacific
Asia Pacific leads several end-use sectors and holds about 29% share in 2024. India and China dominate production due to large peppermint cultivation and established menthol extraction facilities. Demand grows across pharmaceuticals, cosmetics, and confectionery as regional consumers prefer stronger mint flavors and herbal formulations. Expanding OTC drug demand and rising use in topical balms boost consumption. Growth in personal care products with cooling effects also enhances product uptake. The region maintains strong supply capabilities and remains the largest global manufacturing hub for natural menthol.
Latin America
Latin America holds close to 6% share of the Natural Menthol Market in 2024. Brazil and Mexico lead consumption due to growing demand in confectionery, oral care, and topical pain-relief products. Increasing interest in herbal and mint-based wellness items supports higher adoption across retail channels. Pharmaceutical usage rises as menthol-based balms and inhalants gain popularity for respiratory relief. Cosmetic brands in the region also incorporate mint fragrances in skincare products. Local production is limited, so imports remain important for meeting industry needs.
Middle East and Africa
The Middle East and Africa account for about 6% share in 2024. Demand grows gradually as pharmaceutical and personal care sectors expand across Gulf countries and South Africa. Use in topical creams, cough remedies, and oral care products strengthens market presence. Growth in aromatherapy and relaxation products also increases interest in natural menthol. Limited local mint cultivation encourages reliance on imports from Asia. Rising consumer preference for natural cooling agents supports broader application across wellness, cosmetics, and OTC drug categories.
Market Segmentations:
By Material
- Crystal
- Liquid
- Powder
- Emulsion
By Application
- Food
- Pharmaceuticals
- Cosmetics
- Tobacco
- Aromatherapy
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Natural Menthol Market is shaped by leading companies such as Takasago International Corporation, Silverline Chemicals Ltd., Symrise AG, Agson Global Pvt. Ltd., Fengle Perfume Co., Ltd., KM Chemicals, Bhagat Aromatics Ltd., Arora Aromatics Pvt. Ltd., BASF SE, and Nectar Lifesciences Ltd. These companies focus on expanding high-purity menthol production, improving extraction efficiency, and strengthening their global distribution networks. Market competition intensifies as producers enhance crop sourcing, invest in sustainability programs, and adopt advanced crystallization technologies to ensure consistent quality. Firms also expand into pharmaceuticals, personal care, and flavor segments to secure broader market coverage. Partnerships with fragrance houses, OTC drug manufacturers, and food brands support long-term revenue stability. Many players pursue backward integration to manage raw material volatility and reduce dependency on external suppliers. Continuous innovation in cooling formulations, sensory enhancement applications, and natural ingredient portfolios remains central to achieving competitive differentiation across global markets.
Key Player Analysis
- Takasago International Corporation
- Silverline Chemicals Ltd.
- Symrise AG
- Agson Global Pvt. Ltd.
- Fengle Perfume Co., Ltd.
- KM Chemicals
- Bhagat Aromatics Ltd.
- Arora Aromatics Pvt. Ltd.
- BASF SE
- Nectar Lifesciences Ltd
Recent Developments
- In 2025, BASF launched L-Menthol FCC with a reduced Product Carbon Footprint (rPCF), its first product aimed at reducing Scope 3 carbon emissions for customers.
- In 2025, Symrise received Unilever’s Partner to Win Award for transforming India’s mint supply chain for oral-care ingredients, reinforcing its role in responsible menthol supply.
- In 2025, Nectar Lifesciences Limited (NecLife) announced the sale of its menthol and mint derivatives business to Ceph Lifesciences Private Limited.
Report Coverage
The research report offers an in-depth analysis based on Material, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand will rise as pharmaceutical firms expand menthol-based cough and pain-relief products.
- Personal care brands will increase use of natural menthol in cooling and soothing skincare lines.
- Growth will strengthen as clean-label trends shift companies toward natural mint ingredients.
- Food and beverage producers will adopt menthol for new mint-focused confectionery and gum products.
- Aromatherapy and wellness markets will use more menthol in inhalers, oils, and relaxation products.
- Producers will improve extraction efficiency to reduce cost gaps with synthetic menthol.
- Supply chains will stabilize through better peppermint crop management and farmer support programs.
- Regulatory focus on natural ingredients will encourage broader use across oral and topical formats.
- Emerging markets will adopt menthol faster as OTC drug consumption and cosmetic use increase.
- Companies will expand premium product lines centered on high-purity natural menthol.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Paint Mixing market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Paint Mixing market projected to grow between 2025 and 2032?
Which Paint Mixing market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Paint Mixing market?
Who are the leading companies in the Paint Mixing market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 6.15 Billion → 2032: USD 8.42 Billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Natural Menthol Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Natural Menthol Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Natural Menthol Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Natural Menthol Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Natural Menthol Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Natural Menthol Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Natural Menthol Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Natural Menthol Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 6.15 Billion → 2032: USD 8.42 Billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Natural Menthol Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Natural Menthol Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Natural Menthol Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Natural Menthol Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

