
Portable Oxygen Concentrator Market Overview:
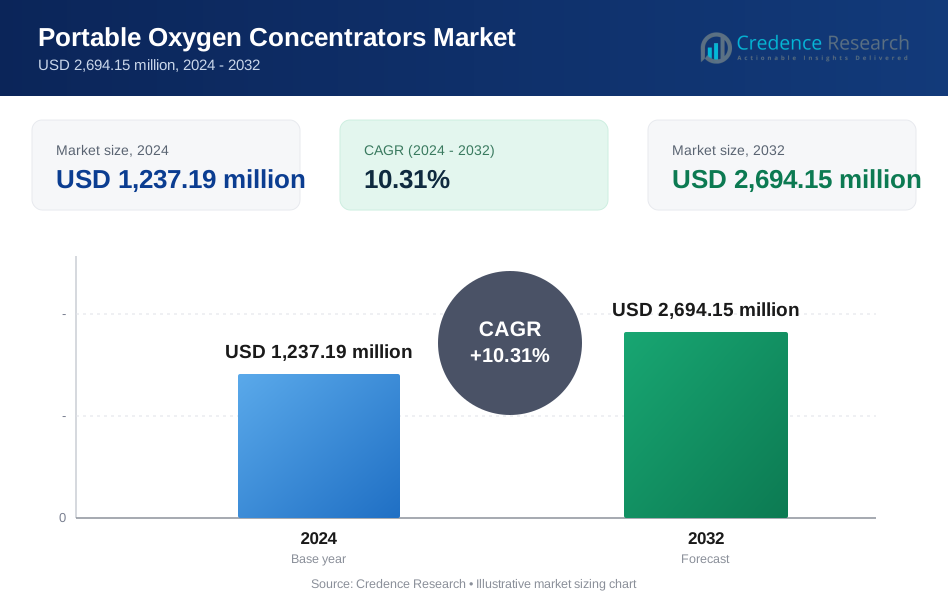
The Portable Oxygen Concentrators market size was valued at USD 890.00 million in 2018, reached USD 1,237.19 million in 2024, and is anticipated to reach USD 2,694.15 million by 2032, growing at a CAGR of 10.31% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Portable Oxygen Concentrator Market Size 2024 | USD 1,237.19 million |
| Portable Oxygen Concentrator Market, CAGR | 10.31% |
| Portable Oxygen Concentrator Market Size 2032 | USD 2,694.15 million |
Key players in the portable oxygen concentrators market include Inogen Inc., CAIRE Inc., Philips Respironics, ResMed, and Invacare Corporation. These companies lead through strong product innovation, global reach, and focus on lightweight, high-efficiency devices tailored for home and travel use. Inogen holds a prominent position due to its extensive direct-to-consumer model and advanced pulse flow technology. Philips Respironics and ResMed benefit from diversified respiratory care portfolios and smart connectivity features. North America dominates the market with a 37.8% share in 2024, driven by high healthcare spending, favorable reimbursement, and a large aging population. Asia Pacific, with 26.8% share, is the fastest-growing region due to rising disease burden and improved healthcare access.

Portable Oxygen Concentrator Market Insights
- The portable oxygen concentrators market was valued at USD 1,237.19 million in 2024 and is projected to reach USD 2,694.15 million by 2032, growing at a CAGR of 10.31%.
- Rising prevalence of COPD, asthma, and other chronic respiratory disorders is driving steady demand for portable oxygen concentrators.
- Miniaturization, longer battery life, and smart connectivity are key trends shaping product innovation and consumer preference.
- Top players such as Inogen Inc., CAIRE Inc., Philips Respironics, and ResMed dominate through global distribution, R&D investments, and advanced product offerings.
- High device cost limits access in developing regions; North America leads with a 37.8% share, followed by Asia Pacific at 26.8%, while the portable segment accounts for over 70% of total product demand.
Portable Oxygen Concentrator Market Segmentation Analysis:
By Product Type
The portable segment dominates the market, accounting for over 70% of the revenue share. Portability, ease of use, and battery-powered operation drive its widespread adoption across homecare and travel use. Patients with chronic respiratory conditions prefer lightweight models for mobility. Compact form factors and rechargeable battery support encourage regular use during daily activities. In contrast, the fixed segment sees limited growth due to its stationary nature and restricted usage settings. The rising elderly population and demand for at-home oxygen therapy further boost portable concentrator sales globally.
- For instance, Inogen manufactures the Inogen One G5 portable concentrator weighing 2.2 kilograms with a maximum battery life of up to 6.5 hours on a single charge.
By Technology:
Pulse flow concentrators hold the leading position, contributing more than 60% of market revenue. These devices release oxygen only during inhalation, conserving power and increasing battery life. Their compact size and energy efficiency make them suitable for active users. On the other hand, continuous flow units are preferred for patients requiring steady oxygen delivery but are bulkier and less energy-efficient. Pulse flow models remain favored due to advancements in sensor technology and dual-mode functionality in newer devices supporting both flow types.
- For instance, Philips Respironics developed pulse flow oxygen concentrators, such as the SimplyGo and SimplyGo Mini, using breath-detection sensors that deliver an oxygen bolus (dose) during the initial phase of inhalation.
By Indication:
Chronic Obstructive Pulmonary Disease (COPD) is the dominant indication, capturing over 50% of the market share. COPD patients often require long-term oxygen therapy, driving demand for reliable concentrators. Asthma and sleep apnea represent smaller segments but still show steady demand due to intermittent oxygen needs during attacks or sleep. The others category includes conditions like pulmonary fibrosis and cystic fibrosis. With rising COPD prevalence, especially among aging populations and smokers, the segment continues to drive strong growth in the portable oxygen concentrators market.
Portable Oxygen Concentrator Market Key Growth Drivers
Rising Prevalence of Respiratory Disorders
The increasing incidence of chronic respiratory diseases such as COPD, asthma, and sleep apnea is a primary growth driver. According to WHO, over 390 million people globally suffer from COPD and asthma combined. This surge in patient volume drives long-term oxygen therapy needs, especially among aging populations. Portable oxygen concentrators offer a non-invasive, convenient, and safer alternative to traditional oxygen cylinders. Their ease of use enables home-based treatment and mobility for patients. As awareness of early diagnosis and home treatment options rises, healthcare providers are prescribing these devices more often, boosting demand.
- For instance, Inogen reported that its portable oxygen concentrators have been prescribed to more than 1 million respiratory patients worldwide.
Expanding Geriatric Population Worldwide
Global aging trends directly influence market growth, as older adults are more prone to respiratory ailments. According to the United Nations, the population aged 65 and above is projected to reach 1.5 billion by 2050. Seniors often require continuous or intermittent oxygen therapy due to declining lung capacity or chronic conditions. Portable oxygen concentrators meet their needs by providing lightweight, quiet, and user-friendly oxygen delivery systems. Demand is particularly strong in developed countries with advanced homecare systems and healthcare insurance coverage. Aging demographics continue to fuel the expansion of the global portable oxygen concentrators market.
- For instance, Philips Respironics historically supplied home oxygen therapy devices to tens of thousands of facilities and providers globally, as of 2025, the company has stopped manufacturing and selling new oxygen concentrators in the United States and other major markets.
Growing Preference for Home-Based Healthcare
Rising healthcare costs and hospital overcrowding have accelerated the shift toward home-based care. Patients and providers increasingly prefer portable oxygen concentrators for use outside hospital settings. These devices reduce hospital readmission rates and support independence for users with chronic conditions. Government initiatives and insurance reimbursements further encourage home oxygen therapy adoption. Technological advancements have improved device reliability, battery life, and compactness, aligning with patient needs. Homecare solutions also ease the burden on healthcare infrastructure while improving patient outcomes. This growing preference plays a crucial role in expanding the market footprint of portable oxygen concentrators.
Portable Oxygen Concentrator Market Key Trends & Opportunities
Integration of Smart Features and Remote Monitoring
Manufacturers are incorporating smart features such as Bluetooth connectivity, mobile apps, and remote diagnostics. These innovations enable real-time monitoring of device performance and oxygen usage. Patients and caregivers can track therapy effectiveness, battery status, and maintenance schedules through connected platforms. Healthcare providers also benefit from remote access to patient data, enabling better clinical decisions and proactive interventions. The trend supports personalized care and device optimization, enhancing overall treatment adherence. As telemedicine and digital health adoption rise, portable oxygen concentrators with IoT capabilities are poised for higher demand and market penetration.
- For instance, Inogen integrated Bluetooth connectivity into its portable oxygen concentrators, enabling data transfer to mobile applications that record oxygen delivery sessions, battery cycles, and device alerts.
Product Miniaturization and Enhanced Battery Performance
Technological advancements are driving the development of ultra-lightweight and compact models with extended battery life. Patients increasingly seek devices that support mobility without compromising oxygen output. Recent innovations include dual-flow concentrators, high-efficiency lithium-ion batteries, and ergonomic designs that reduce strain during long-term use. Airlines and travel authorities are also relaxing regulations for FAA-approved models, expanding their appeal for travelers. These improvements open opportunities in emerging markets where infrastructure limits access to traditional oxygen therapy. Continued R&D focused on user-friendly, energy-efficient designs creates competitive differentiation and captures a wider user base.

Portable Oxygen Concentrator Market Key Challenges
High Device Cost and Limited Affordability in Developing Regions
Portable oxygen concentrators are expensive due to advanced technology and strict regulatory requirements. Entry-level models may cost upwards of USD 1,500, with premium models exceeding USD 3,000. In low- and middle-income countries, affordability remains a major barrier. Limited health insurance coverage and lack of public reimbursement programs restrict access. Hospitals and homecare providers in developing regions often prefer cheaper, less portable alternatives. While refurbished or rental units are growing, widespread adoption in cost-sensitive markets remains limited. Bridging the affordability gap through subsidies or tiered pricing models is necessary to unlock untapped demand.
Regulatory Barriers and Product Approval Delays
Gaining regulatory clearance for medical devices involves lengthy procedures, especially in multiple jurisdictions. Each market has distinct safety, efficacy, and labeling standards. This slows product launches and global expansion for manufacturers. Compliance with certifications such as FDA (U.S.), CE Mark (Europe), and CDSCO (India) requires significant documentation and clinical evidence. Post-market surveillance and product recalls also impact brand reputation. Startups and new entrants face additional barriers due to high upfront costs and limited regulatory expertise. Navigating evolving regulations while ensuring fast time-to-market remains a persistent challenge across the industry.
Portable Oxygen Concentrator Market Regional Analysis
North America
North America led the global portable oxygen concentrators market in 2024 with a market size of USD 467.65 million, rising from USD 340.34 million in 2018. It is projected to reach USD 1,017.05 million by 2032, growing at a CAGR of 10.3%. The region accounted for the largest share, approximately 37.8% of the global market in 2024. High healthcare spending, early technology adoption, and the strong presence of leading manufacturers drive regional growth. An aging population and the rising prevalence of COPD and sleep apnea also support sustained demand for advanced oxygen therapy solutions.
Europe
Europe held the second-largest share in 2024, valued at USD 291.70 million, up from USD 218.94 million in 2018, and is forecasted to reach USD 597.44 million by 2032. It is growing at a CAGR of 9.5% and accounted for about 23.6% of the global market in 2024. Increasing geriatric population and supportive government healthcare policies boost regional adoption. The presence of well-established homecare services and reimbursement frameworks further strengthens market expansion across Germany, France, and the UK. Europe's strict regulatory compliance ensures high device quality and supports consistent patient outcomes.
Asia Pacific
Asia Pacific is the fastest-growing region with a CAGR of 11.6%. The market grew from USD 228.55 million in 2018 to USD 331.13 million in 2024 and is expected to reach USD 792.35 million by 2032. The region contributed approximately 26.8% of the global market in 2024. Rising air pollution, smoking rates, and a growing elderly population drive respiratory disorder cases across China, India, and Japan. Increased healthcare investments, expanding medical infrastructure, and growing awareness of homecare devices further support market growth. Global players are entering this region with localized offerings to capture the expanding demand.
Latin America
Latin America's portable oxygen concentrators market reached USD 74.71 million in 2024, up from USD 54.29 million in 2018, and is projected to reach USD 150.52 million by 2032, expanding at a CAGR of 9.3%. The region accounted for around 6% of the global market share in 2024. Brazil and Mexico dominate due to improving healthcare access and increased incidence of respiratory illnesses. Adoption of home-based oxygen therapy is rising, driven by lower hospital bed availability and high out-of-pocket costs. However, affordability and limited insurance coverage continue to pose moderate barriers to faster adoption.
Middle East
The Middle East market stood at USD 31.66 million in 2024, increasing from USD 24.92 million in 2018 and projected to hit USD 59.56 million by 2032, growing at a CAGR of 8.3%. It contributed about 2.6% to the global market in 2024. The prevalence of asthma and COPD is rising due to environmental factors such as sandstorms and smoking. GCC countries like Saudi Arabia and the UAE invest in advanced healthcare technologies and promote homecare options. However, market expansion remains moderate due to uneven device accessibility and reliance on hospital-based oxygen systems.
Africa
Africa’s market size grew from USD 22.96 million in 2018 to USD 40.34 million in 2024 and is expected to reach USD 77.24 million by 2032, expanding at a CAGR of 8.2%. The region represented around 3.3% of the global market share in 2024. Demand is driven by the increasing burden of untreated respiratory diseases and limited hospital infrastructure. South Africa, Nigeria, and Egypt lead regional adoption due to urbanization and improved healthcare access. However, affordability and lack of reimbursement mechanisms restrict large-scale use. Public health programs and NGO involvement may accelerate access to portable oxygen concentrators.
Portable Oxygen Concentrator Market Segmentations:
By Product Type:
- Portable
- Fixed
By Technology:
- Continuous Flow
- Pulse Flow
By Indication:
- Chronic Obstructive Pulmonary Disease (COPD)
- Asthma
- Sleep Apnea
- Others
By Application:
- Homecare
- Travel
- Hospital
- Others
By Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa

Portable Oxygen Concentrator Market Competitive Landscape
The competitive landscape of the portable oxygen concentrators market is characterized by the presence of global and regional players offering technologically advanced and user-centric devices. Leading companies such as Inogen Inc., CAIRE Inc., Philips Respironics, and ResMed dominate with strong product portfolios, international distribution networks, and robust R&D investments. These firms focus on miniaturization, extended battery life, and smart connectivity to gain a competitive edge. Mergers, acquisitions, and partnerships are common strategies to expand market presence and enhance innovation pipelines. For instance, Chart Industries' acquisition of CAIRE has strengthened its respiratory care portfolio. Emerging players from China and India, such as Besco Medical and Nidek Medical, offer cost-effective alternatives and expand reach in price-sensitive markets. Competition also intensifies through rental services and direct-to-consumer online sales channels. As demand for homecare and portable solutions rises, companies continue to invest in differentiated offerings and geographic expansion to secure long-term market positioning.
Key Player Analysis
- AirSep Corporation
- Besco Medical Co., LTD (China)
- CAIRE Inc. (US)
- Chart Industries, Inc. (US)
- Drive DeVilbiss Healthcare (US)
- Foshan Keyhub Electronic Industries Co. Ltd. (Guangdong)
- GCE Group (Sweden)
- Inogen, Inc. (US)
- Inova Labs, Inc.
- Invacare Corporation (US)
- Koninklijke Philips N.V (Netherlands)
- Nidek Medical (India)
- O2 CONCEPTS LLC. (US)
- Oxus America, Inc. (Oxus)
- Philips Respironics (US)
- Precision Medical, Inc. (US)
- ResMed (US)
- Smith's Medical, Inc. (US)
- Zadro Health Solutions (US)
Recent Developments
- In October 2024, Inogen launched the Rove 4 portable concentrator delivering up to 840 ml/min in a sub-3-pound form factor.
- In August 2024, FDA issued warning letters to Shenzhen Moyeah and LEEL Tech for distributing unapproved respiratory devices.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Technology, Indication, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will witness sustained growth driven by rising respiratory disease incidence.
- Portable models will continue to dominate due to increasing demand for mobility and convenience.
- Homecare segment adoption will rise as healthcare systems promote outpatient treatment.
- Asia Pacific will emerge as a key growth region with improving healthcare infrastructure.
- Technological innovation will focus on longer battery life and dual-mode flow systems.
- Integration of IoT and remote monitoring features will enhance patient adherence.
- Competitive pricing and financing options will expand device access in developing regions.
- Strategic partnerships and acquisitions will shape global market expansion.
- Aging population will boost long-term oxygen therapy needs across developed countries.
- Direct-to-consumer sales and online distribution channels will gain more market traction.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence of Chronic Respiratory Diseases
The increasing incidence of COPD, asthma, and sleep apnea is driving demand for portable oxygen concentrators, as these conditions often require long-term oxygen therapy and support for patient mobility.
Expanding Geriatric Population
Aging populations worldwide are more susceptible to chronic respiratory conditions, leading to higher adoption of portable oxygen concentrators for home-based and ambulatory care.
Shift Toward Home-Based Healthcare
Healthcare systems and patients are increasingly favoring homecare solutions to reduce hospital stays and costs, boosting demand for portable oxygen concentrators that enable outpatient and at-home treatment.
Technological Advancements in Device Miniaturization and Connectivity
Innovations such as lighter devices, longer battery life, and integration of smart features like Bluetooth and remote monitoring are making portable oxygen concentrators more attractive and accessible to a broader patient base.
Improved Healthcare Access in Emerging Markets
Rising healthcare investments, expanding infrastructure, and greater awareness of respiratory care in regions like Asia Pacific are accelerating the adoption of portable oxygen concentrators.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Portable Oxygen Concentrators market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Portable Oxygen Concentrators market projected to grow between 2024 and 2032?
Which Portable Oxygen Concentrators market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Portable Oxygen Concentrators market?
Who are the leading companies in the Portable Oxygen Concentrators market?
Which region commanded the largest share of the Portable Oxygen Concentrators market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Indication
- 1.2.1 Chronic Obstructive Pulmonary Disease (COPD)
- 1.2.2 Asthma
- 1.2.3 Sleep Apnea
- 1.2.4 Others
- 1.3 By Technology
- 1.3.1 Pulse Flow
- 1.3.2 Continuous Flow
- 1.4 By Application
- 1.4.1 Homecare
- 1.4.2 Travel
- 1.4.3 Hospital
- 1.4.4 Others
- 1.5 By Product Type
- 1.5.1 Portable
- 1.5.2 Fixed
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,237.19 million → 2032: USD 2,694.15 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Portable Oxygen Concentrators Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Portable Oxygen Concentrators Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Portable Oxygen Concentrators Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Portable Oxygen Concentrators Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Portable Oxygen Concentrators Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Portable Oxygen Concentrators Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Portable Oxygen Concentrators Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Portable Oxygen Concentrators Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,237.19 million → 2032: USD 2,694.15 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Portable Oxygen Concentrators Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Indication - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Chronic Obstructive Pulmonary Disease (COPD)
- 12.3.7.2 Asthma
- 12.3.7.3 Sleep Apnea
- 12.3.7.4 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Pulse Flow
- 12.4.7.2 Continuous Flow
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Homecare
- 12.5.7.2 Travel
- 12.5.7.3 Hospital
- 12.5.7.4 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Product Type - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Portable
- 12.6.7.2 Fixed
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Portable Oxygen Concentrators End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Portable Oxygen Concentrators Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Portable Oxygen Concentrators Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Portable Oxygen Concentrators Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Inogen Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 CAIRE Inc.
- 18.4 Philips Respironics
- 18.5 ResMed
- 18.6 Invacare Corporation
- 18.7 Drive DeVilbiss Healthcare
- 18.8 Chart Industries
- 18.9 Nidek Medical
- 18.10 Besco Medical
- 18.11 GCE Group
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

