
Market Overview
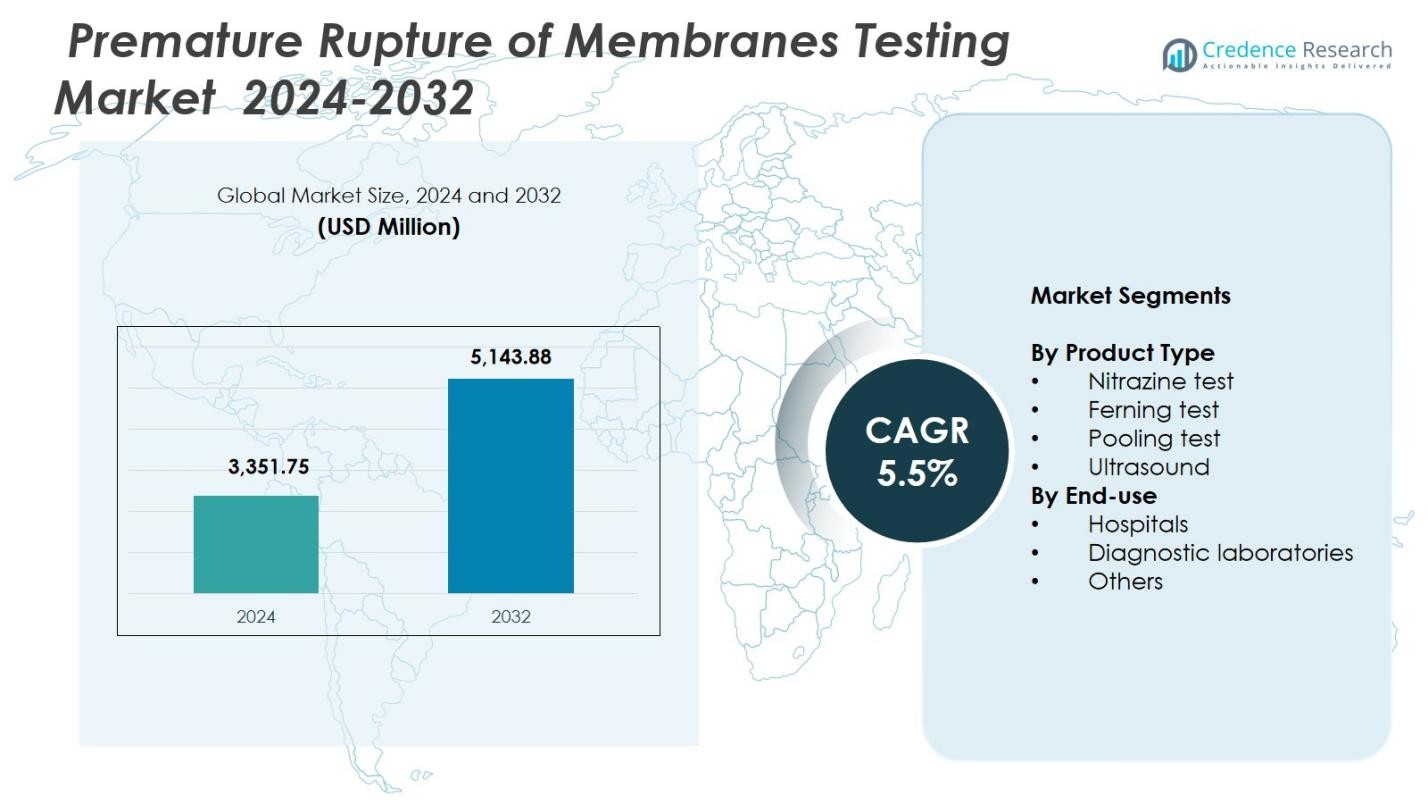
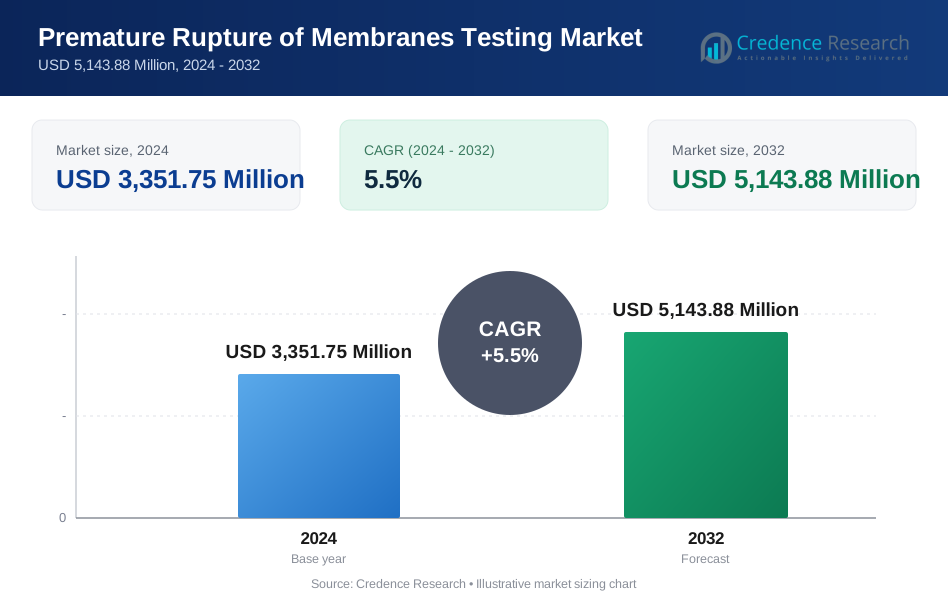
Premature Rupture of Membranes Testing Market size was valued at USD 3,351.75 Million in 2024 and is anticipated to reach USD 5,143.88 Million by 2032, at a CAGR of 5.5% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Premature Rupture of Membranes Testing Market Size 2024 | USD 3,351.75 Million |
| Premature Rupture of Membranes Testing Market, CAGR | 5.5% |
| Premature Rupture of Membranes Testing Market Size 2032 | USD 5,143.88 Million |
Premature Rupture of Membranes Testing Market features leading players such as Clinical Innovations LLC, Hologic Inc., Medix Biochemica, NX Prenatal Inc., Sera Prognostics Inc., Abbott Laboratories, The Cooper Companies Inc., QIAGEN, Biosynex, and IQ Products, all driving advancements in PROM diagnostics through biomarker innovation, rapid point-of-care solutions, and expanded clinical accessibility. These companies focus on enhancing test accuracy and supporting standardized obstetric workflows across hospitals and laboratories. Regionally, North America led the market with a 39.8% share in 2024, followed by Europe at 29.4%, owing to strong maternal health infrastructure, high adoption of advanced diagnostic assays, and increased emphasis on early detection of PROM-related complications.
Market Insights
- Premature Rupture of Membranes Testing Market was valued at USD 3,351.75 Million in 2024 and will reach USD 5,143.88 Million by 2032, growing at a CAGR of 5.5%.
- The market grows as rising preterm birth rates and increased focus on maternal–fetal health drive strong demand for accurate PROM diagnostic tools across hospitals and laboratories.
- A major trend is the shift toward rapid, biomarker-based and point-of-care PROM tests, supported by digital integration and improved diagnostic consistency across clinical settings.
- Key players including Clinical Innovations LLC, Hologic Inc., Abbott Laboratories, Medix Biochemica, and NX Prenatal Inc. strengthen their positions through product innovation and expanded distribution networks; nitrazine testing led product adoption with a 38.6% share in 2024
- North America led with a 39.8% share in 2024, followed by Europe at 29.4% and Asia-Pacific at 21.7%, supported by growing healthcare modernization and broader adoption of PROM diagnostic solutions.
 Market Segmentation Analysis:
By Product Type
The Premature Rupture of Membrsanes Testing Market shows strong adoption across multiple diagnostic methods, with the nitrazine test dominating the segment with a 38.6% share in 2024. Its leadership stems from rapid result delivery, low cost, and widespread clinical acceptance in both primary and advanced maternity care settings. The ferning test and pooling test continue to serve as complementary methods, while ultrasound grows steadily due to its non-invasive nature and improved diagnostic accuracy. Increasing emphasis on early PROM detection further supports uptake across all test types, reinforcing demand for reliable and scalable diagnostic tools.
- For instance, the ROM Plus test (Laborie) uses a monoclonal/polyclonal antibody approach to simultaneously detect alpha-fetoprotein and IGFBP-1, with analytical validation showing 100% positive visual results at IGFBP-1 concentrations up to 400,000 ng/mL and AFP up to 200,000 ng/mL, supporting rapid point-of-care decision-making.
By End-Use
Within the end-use landscape, hospitals held the largest share at 57.4% in 2024, driven by high patient inflow, advanced obstetric care capabilities, and routine PROM screening during emergency and antenatal evaluations. Diagnostic laboratories accounted for a significant share due to the increasing shift toward confirmatory testing and access to specialized personnel. Other settings, including maternity clinics and birthing centers, show consistent growth as point-of-care PROM tests become more accessible. Rising awareness of preterm birth risks and the need for accurate membrane-rupture differentiation continue to strengthen hospital and laboratory testing demand.
- For instance, maternity clinics and birthing centers benefit from rapid immunoassay kits such as Actim PROM (detecting IGFBP-1), which has shown sensitivity above 90% in published evaluations, enabling decentralized point-of-care assessment for timely referral and intervention.
Key Growth Drivers
Rising Incidence of Preterm Birth and PROM-Related Complications
The increasing global incidence of preterm birth and pregnancy-related complications is a major driver for the Premature Rupture of Membranes Testing Market. PROM remains a leading cause of neonatal morbidity, requiring accurate and timely diagnosis to reduce risks such as infections, fetal distress, and adverse perinatal outcomes. As healthcare systems prioritize maternal and fetal health, demand for reliable diagnostic tools strengthens. Hospitals and maternity centers integrate PROM testing into routine obstetric assessments, fueling consistent market expansion across developed and developing regions.
- For instance, QIAGEN's AmniSure ROM test identifies PAMG-1 protein marker in vaginal discharge using a sterile swab and solvent vial, providing results in minutes without gestational age restrictions.
Growing Adoption of Rapid and Point-of-Care Diagnostic Solutions
The shift toward rapid and point-of-care testing has significantly accelerated market growth, enabling clinicians to diagnose PROM with greater accuracy and reduced turnaround time. Traditional methods such as nitrazine and ferning tests are increasingly supplemented by advanced biochemical assays that improve detection sensitivity. Point-of-care kits support immediate decision-making in emergency and rural healthcare settings, minimizing delays in managing high-risk pregnancies. Rising awareness of improved patient outcomes associated with early diagnosis further boosts adoption of portable and user-friendly PROM testing solutions.
- For instance, Abbott's Actim PROM test delivers results in 5 minutes using a one-step dipstick on a vaginal swab sample, even in the presence of blood, semen, or vaginal discharge. This bedside tool detects IGFBP-1 from amniotic fluid reliably across all gestational ages.
Advancements in Diagnostic Technologies and Biomarker Research
Innovation in biomarker-based testing enhances diagnostic precision in PROM, driving healthcare providers to shift toward more reliable and standardized tools. Companies are investing in assays that detect specific amniotic fluid proteins, improving differentiation between true membrane rupture and false positives. These advancements reduce reliance on subjective methods and promote more consistent clinical decision-making. Growing R&D initiatives, regulatory approvals for advanced PROM kits, and integration of automated laboratory technologies collectively strengthen the market’s technological landscape and long-term growth trajectory.
Key Trends & Opportunities
Expansion of Digital and Connected Diagnostic Platforms
A key trend shaping the market is the integration of digital tools and connectivity into PROM testing workflows. Digitally enabled diagnostic devices enhance accuracy through standardized interpretation, data recording, and remote clinician consultation. Integration with electronic health records improves continuity of care and supports real-time monitoring in high-risk pregnancies. This trend opens opportunities for manufacturers to develop smart PROM testing systems, particularly for telemedicine-driven maternal care programs in remote and underserved regions where access to specialized obstetric expertise is limited.
- For instance, Hologic's Actim PROM test provides rapid bedside detection of premature rupture of fetal membranes in 5 minutes, even with blood or interfering substances present, aiding timely decisions in clinical settings.
Increasing Market Potential in Emerging Healthcare Economies
Growing investments in maternal healthcare infrastructure across Asia-Pacific, Latin America, and Africa create significant opportunities for PROM testing expansion. Rising awareness of perinatal risks and improvements in diagnostic accessibility support broader adoption of both basic and advanced PROM tests. Governments and NGOs are strengthening antenatal programs, encouraging routine membrane integrity assessments. As healthcare facilities upgrade diagnostic capabilities, demand for cost-effective test kits and rapid screening tools increases, enabling companies to expand their reach and establish strong market presence in high-growth regions.
- For instance, Novocuff secured $26 million in Series A funding in July 2024 to advance its preterm birth prevention device targeting PPROM, with plans for global market introduction including low- and middle-income countries in Africa and Asia-Pacific.
Key Challenges
High Rate of False Positives and Diagnostic Inconsistency in Traditional Tests
Despite widespread use, traditional PROM diagnostic methods such as nitrazine and ferning tests face limitations due to contamination, user interpretation variability, and lower specificity. These inconsistencies can lead to false positives, unnecessary interventions, or mismanagement of pregnancy complications. Providers increasingly seek reliable alternatives, yet accessibility to advanced biomarker-based tests remains restricted in many regions due to cost or infrastructure barriers. This diagnostic gap continues to challenge uniform adoption of accurate PROM testing protocols globally.
Limited Access to Advanced Diagnostics in Low-Resource Settings
Although improved technologies enhance PROM detection accuracy, many low- and middle-income regions lack adequate laboratory infrastructure, trained personnel, and financial resources to implement advanced diagnostic solutions. Reliance on basic, less reliable tests persists, creating disparities in maternal and neonatal care outcomes. High procurement costs, insufficient reimbursement policies, and weak supply chains further hinder market penetration. Addressing these challenges requires expanded point-of-care manufacturing, subsidized test availability, and capacity-building initiatives to improve diagnostic equity across global healthcare systems.
Regional Analysis
North America
North America dominated the Premature Rupture of Membranes Testing Market with a 39.8% share in 2024, driven by advanced maternal healthcare infrastructure, high adoption of biomarker-based PROM diagnostics, and strong presence of leading manufacturers. Hospitals and diagnostic laboratories increasingly rely on standardized testing methods to manage rising preterm birth rates. Favorable reimbursement policies and continual technological innovations further strengthen regional growth. The U.S. leads the market due to high testing volumes and rapid integration of point-of-care solutions, while Canada benefits from expanding prenatal screening programs and improved access to specialized obstetric care.
Europe
Europe accounted for a 29.4% share in 2024, supported by strong clinical guidelines for PROM management, widespread use of advanced diagnostic assays, and substantial investment in maternal health programs. Countries such as Germany, the U.K., and France prioritize early detection of pregnancy complications, promoting adoption of accurate and rapid PROM tests. The region benefits from robust laboratory networks and rising preference for standardized biomarker-based methods. Increasing regulatory approvals and collaborations between research institutions and diagnostic companies further enhance the development and utilization of modern PROM testing solutions across European healthcare systems.
Asia-Pacific
Asia-Pacific held a 21.7% share in 2024, emerging as one of the fastest-growing regions due to rising preterm birth prevalence, expanding healthcare infrastructure, and increasing awareness of maternal complications. Countries such as China, India, and Japan are witnessing higher demand for accessible and cost-effective PROM testing solutions. Government initiatives aimed at strengthening prenatal care, along with expanding private maternity hospitals, support broader adoption of rapid diagnostic kits. Growing penetration of point-of-care devices and enhanced laboratory capabilities further contribute to market expansion, positioning Asia-Pacific as a major growth engine for PROM diagnostics.
Latin America
Latin America captured a 5.6% share in 2024, driven by improving healthcare access, growing adoption of emergency obstetric care, and rising emphasis on reducing maternal and neonatal morbidity. Brazil and Mexico lead the region due to expanding public health programs and increasing investment in diagnostic technologies. While resource limitations persist, demand for rapid and affordable PROM tests is rising, particularly in urban healthcare facilities. Efforts to strengthen maternal health education and enhance diagnostic capabilities across hospitals and clinics continue to support steady regional growth and improved PROM detection outcomes.
Middle East & Africa
The Middle East & Africa region accounted for a 3.5% share in 2024, influenced by gradual improvements in maternal healthcare systems and increasing focus on early detection of pregnancy complications. Gulf countries demonstrate higher adoption levels due to improved hospital infrastructure and greater access to advanced diagnostics, while many African nations rely predominantly on basic PROM testing methods. International health initiatives and investments in maternal and neonatal programs support incremental growth. Expanding availability of point-of-care testing devices and workforce training efforts are helping the region overcome diagnostic gaps and enhance PROM management standards.
Market Segmentations:
By Product Type
- Nitrazine test
- Ferning test
- Pooling test
- Ultrasound
By End-use
- Hospitals
- Diagnostic laboratories
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Premature Rupture of Membranes Testing Market features key players such as Clinical Innovations LLC, Hologic Inc., Medix Biochemica, NX Prenatal Inc., Sera Prognostics Inc., Abbott Laboratories, The Cooper Companies Inc., QIAGEN, Biosynex, and IQ Products, all contributing to advancements in PROM diagnostics. These companies focus on enhancing test accuracy, expanding biomarker research, and developing rapid point-of-care solutions to meet rising clinical demand. Strategic initiatives such as product launches, regulatory approvals, and collaborations with maternal health institutions strengthen their market presence. Leading manufacturers prioritize innovation in biochemical assays and integrated digital diagnostic platforms, supporting more reliable and standardized PROM detection. Market participants also expand their global distribution networks to increase access to PROM testing across hospitals, diagnostic laboratories, and maternity clinics. Growing investment in R&D and the adoption of more sensitive diagnostic technologies continue to intensify competition while improving clinical outcomes for high-risk pregnancies.
Key Player Analysis
- Clinical Innovations LLC
- Hologic Inc.
- Medix Biochemica
- NX Prenatal Inc.
- Sera Prognostics Inc.
- Abbott Laboratories
- The Cooper Companies Inc.
- QIAGEN
- Biosynex
- IQ Products
Recent Developments
- In July 2024, Novocuff secured $26 million in Series A funding to develop a device aimed at preventing preterm births caused by preterm premature rupture of membranes (PPROM) and cervical shortening.
- In January 2023, QIAGEN partnered with Helix for development and commercialization of companion diagnostics for several hereditary diseases. Through this partnership, Helix Laboratory Platform will create companion diagnoses in the United States while QIAGEN will utilize the QIASeq Human Exome Kits in the rest of the globe for the diagnosis of a variety diseases.
- In June 2022, Medix Biochemica acquired Bioresource Technology Inc. a prominent player in critical raw materials for IVD quality control products production. This acquisition broadened the company’s offerings in the in-vitro diagnostics business.
Report Coverage
The research report offers an in-depth analysis based on Product Type, End Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will expand steadily as maternal health awareness and early diagnosis of pregnancy complications continue to rise.
- Adoption of advanced biomarker-based tests will increase as healthcare providers seek higher diagnostic accuracy.
- Point-of-care PROM testing will gain wider traction across hospitals, clinics, and emergency care settings.
- Digital integration and automated result interpretation will enhance reliability and reduce clinical variability.
- Emerging economies will experience strong growth due to improved healthcare infrastructure and prenatal screening initiatives.
- Companies will invest more in developing rapid, non-invasive, and cost-effective PROM diagnostic solutions.
- Collaborations between diagnostic firms and maternal health research institutions will accelerate innovation.
- Reimbursement improvements and clinical guideline updates will support broader use of standardized PROM tests.
- Portable and user-friendly PROM testing kits will see rising adoption in rural and resource-limited areas.
- Market competition will intensify as new entrants introduce advanced assays and expand global distribution networks.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Premature Rupture of Membranes Testing Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Premature Rupture of Membranes Testing Market projected to grow between 2025 and 2032?
Which Premature Rupture of Membranes Testing Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Premature Rupture of Membranes Testing Market?
Who are the leading companies in the Premature Rupture of Membranes Testing Market?
Which region commanded the largest share of the Premature Rupture of Membranes Testing Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Premature Rupture of Membranes Testing Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Premature Rupture of Membranes Testing Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 3,351.75 Million → 2032: USD 5,143.88 Million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Premature Rupture of Membranes Testing Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Premature Rupture of Membranes Testing Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Premature Rupture of Membranes Testing Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Premature Rupture of Membranes Testing Market Drivers
- 3.3 Premature Rupture of Membranes Testing Market Restraints & Challenges
- 3.4 Premature Rupture of Membranes Testing Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Premature Rupture of Membranes Testing Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Premature Rupture of Membranes Testing Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Premature Rupture of Membranes Testing category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Premature Rupture of Membranes Testing Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Premature Rupture of Membranes Testing Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Premature Rupture of Membranes Testing market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Premature Rupture of Membranes Testing Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Premature Rupture of Membranes Testing Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Premature Rupture of Membranes Testing Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Premature Rupture of Membranes Testing (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Premature Rupture of Membranes Testing Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Premature Rupture of Membranes Testing Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Premature Rupture of Membranes Testing Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Premature Rupture of Membranes Testing Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Premature Rupture of Membranes Testing Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Premature Rupture of Membranes Testing Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Premature Rupture of Membranes Testing Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Premature Rupture of Membranes Testing Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Premature Rupture of Membranes Testing Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
