
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Prescription Delivery Services Market Size 2024 | USD 215.4 Million |
| Prescription Delivery Services Market, CAGR | 5.5% |
| Prescription Delivery Services Market Size 2032 | USD 330.57 Million |
Market Overview:
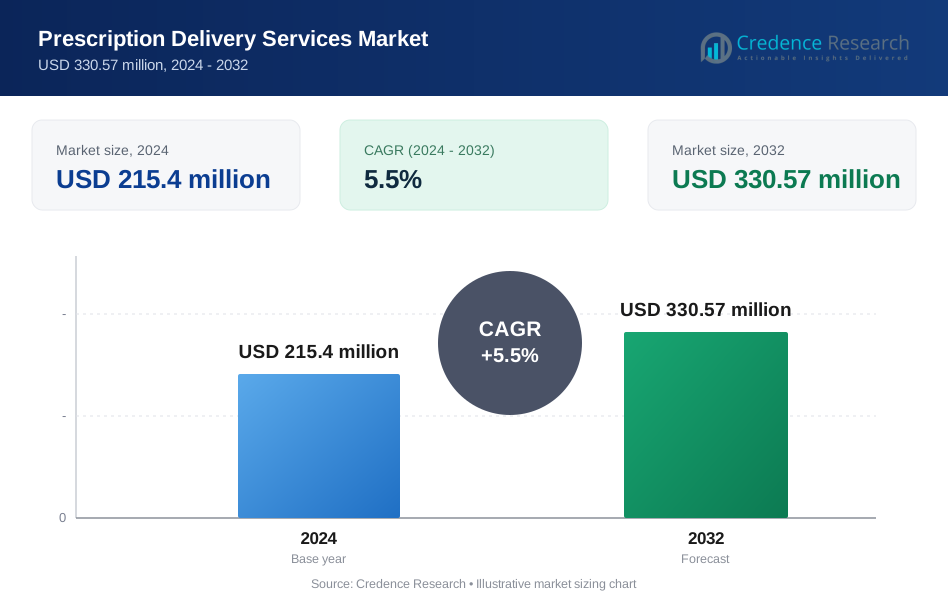
The Prescription Delivery Services Market is projected to grow from USD 215.4 million in 2024 to an estimated USD 330.57 million by 2032, with a compound annual growth rate (CAGR) of 5.5% from 2024 to 2032.
The demand for prescription delivery services is being propelled by the increasing prevalence of chronic diseases such as diabetes, cardiovascular conditions, and hypertension, which require regular medication. The growing geriatric population, which often faces mobility challenges, further contributes to the demand for home delivery of prescriptions. The widespread adoption of telemedicine has also created a need for seamless integration between online consultations and medication delivery, enhancing patient convenience. Additionally, advancements in logistics and distribution networks, including same-day delivery options, are boosting consumer confidence in these services. The COVID-19 pandemic accelerated the adoption of e-commerce in healthcare, with consumers prioritizing contactless and safe delivery options for medications, setting a lasting trend for the market.
North America holds the largest share of the Prescription Delivery Services market, driven by high healthcare expenditure, advanced digital infrastructure, and widespread adoption of telehealth solutions. The United States, in particular, leads the region with significant investments in healthcare e-commerce and logistics. Europe follows closely, with countries like Germany and the United Kingdom witnessing growth due to an aging population and increasing chronic disease prevalence. Meanwhile, the Asia-Pacific region is experiencing the fastest growth, fueled by expanding internet penetration, growing adoption of digital healthcare platforms, and increasing disposable incomes in countries like China and India. Emerging markets in Latin America and the Middle East & Africa also present untapped potential as healthcare systems modernize and consumer demand for convenience rises.
Market Insights:
- The market is projected to grow from USD 215.4 million in 2024 to USD 330.57 million by 2032, reflecting a growing demand for convenient medication delivery solutions.
- Chronic diseases such as diabetes, cardiovascular disorders, and hypertension are driving the need for reliable prescription delivery services to ensure consistent treatment adherence.
- The growing geriatric population, particularly in developed regions, is fueling demand as elderly individuals seek convenient alternatives to in-person pharmacy visits.
- The COVID-19 pandemic significantly accelerated the adoption of contactless prescription delivery, establishing a lasting consumer preference for e-commerce in healthcare.
- Advances in digital healthcare platforms, such as telemedicine and online pharmacies, are creating seamless integration between consultations and medication delivery.
- North America leads the market with 40% share, driven by advanced healthcare infrastructure and widespread telehealth adoption, while Asia-Pacific is the fastest-growing region.
- Challenges such as regulatory complexities, high operational costs, and limited consumer awareness in rural areas remain key barriers to market penetration.
Market Drivers:
Growing Prevalence of Chronic Diseases
The rising prevalence of chronic diseases such as diabetes, cardiovascular disorders, and respiratory conditions is significantly driving the growth of the Prescription Delivery Services market. These conditions require consistent medication management, prompting patients to seek reliable and convenient delivery services to ensure adherence to treatment regimens. For instance, a report by the American Diabetes Association indicated that in 2022, over 37 million Americans had diabetes, with nearly 90% requiring regular medication. The increasing incidence of such diseases across all age groups underscores the need for streamlined medication delivery systems. Additionally, the rise in multi-drug prescriptions among patients with comorbidities has further bolstered the demand for these services.
Increasing Adoption of Digital Health Solutions
The integration of digital technology in healthcare has revolutionized how patients access medications. The widespread adoption of telemedicine platforms has created a seamless link between online consultations and prescription delivery services. Patients can now consult with healthcare professionals remotely and have their medications delivered directly to their homes. For example, the Ayushman Bharat Digital Mission in India has integrated over 110 digital health services, significantly enhancing user convenience and driving market growth. Furthermore, advancements in mobile applications and online pharmacy platforms have simplified the ordering process, enhancing user convenience and driving market growth. Real-time tracking and automated reminders offered by these platforms are additional features that improve user experience and medication compliance.
Rising Geriatric Population and Mobility Challenges
The growing elderly population, particularly in developed and rapidly aging economies, is a critical driver for the market. Older adults often face mobility issues and depend on consistent access to medications for managing chronic conditions. Prescription delivery services provide a convenient solution for this demographic, eliminating the need to visit physical pharmacies. For instance, PillPack by Amazon Pharmacy offers pre-sorted medications delivered directly to seniors' homes, simplifying medication management and ensuring timely deliveries. Additionally, caregivers and family members increasingly rely on these services to ensure timely medication deliveries, which has further contributed to the market's expansion.
Impact of the COVID-19 Pandemic
The COVID-19 pandemic accelerated the adoption of prescription delivery services, creating a lasting shift in consumer behavior. With social distancing measures and a heightened focus on contactless services, patients prioritized home delivery of medications. The pandemic also underscored the importance of resilient supply chains and last-mile logistics, prompting companies to invest in improving delivery speed and reliability. For example, the use of drone-based delivery systems by companies like Zipline has improved delivery speed and reliability, ensuring timely access to medications during the pandemic. These developments, combined with heightened consumer awareness about the convenience of online healthcare services, have established a strong foundation for sustained market growth in the post-pandemic era.
Market Trends:
Integration of Artificial Intelligence and Machine Learning
The incorporation of artificial intelligence (AI) and machine learning (ML) is transforming the Prescription Delivery Services market. AI-driven tools optimize delivery routes, forecast demand patterns, and streamline inventory management, enabling faster and more cost-efficient operations. Personalized features, such as automated medication reminders and refill alerts, enhance customer engagement and adherence to treatment plans. For instance, Capsule, a digital pharmacy, uses AI to manage inventory and predict demand, ensuring timely delivery of medications. This trend underscores the industry’s move towards a more technology-driven, patient-centric approach.
Rise of Subscription-Based Models
Subscription-based delivery models are emerging as a popular choice for consumers, particularly those managing chronic illnesses. These services ensure timely medication refills without the hassle of reordering, improving adherence and customer loyalty. Companies offering flexible subscription plans that allow for customized delivery frequencies and combinations of medications are distinguishing themselves in a competitive landscape. For example, ExactCare Pharmacy provides a subscription service that delivers medications pre-sorted by dose and time, ensuring patients take the right medication at the right time. The growing success of this model reflects a broader trend of aligning services with consumer preferences for convenience and reliability.
Advancements in Last-Mile Delivery Solutions
Last-mile delivery innovations are significantly shaping market dynamics. Companies are adopting advanced logistics technologies, including drones, autonomous vehicles, and micro-fulfillment centers, to enhance delivery speed and accessibility. Partnerships with local pharmacies and third-party logistics providers are also expanding operational reach. For instance, CVS has implemented free one-day or two-day delivery on prescriptions and eligible purchases with no minimum order requirement through their CarePass program, which has exceeded initial customer expectations in pilot markets. These advancements are addressing challenges related to urban congestion and remote area access, ensuring faster and more reliable service for consumers.
Focus on Sustainable Delivery Practices
Sustainability is becoming a core focus in the Prescription Delivery Services market, with companies adopting environmentally friendly practices. The use of electric vehicles, reusable packaging, and carbon offset programs is on the rise, driven by increasing consumer demand for green initiatives. For example, Walgreens Boots Alliance has committed to reducing its carbon footprint by using electric delivery vehicles and implementing sustainable packaging solutions. Regulatory support and incentives for eco-friendly logistics further encourage this shift. Companies integrating sustainability into their operations are gaining a competitive edge and strengthening their market presence.
Market Challenges Analysis:
Regulatory and Compliance Barriers
The Prescription Delivery Services market faces significant challenges related to complex regulatory frameworks and compliance requirements. Variations in pharmaceutical laws and drug delivery regulations across regions create operational hurdles for companies looking to expand their geographical reach. Compliance with stringent standards for prescription validation, secure medication handling, and patient data privacy adds to the operational complexity. These regulatory constraints can slow market growth, particularly for new entrants and smaller players without the resources to navigate such barriers effectively.
High Operational Costs and Logistics Challenges
Managing logistics for prescription deliveries involves substantial costs, including last-mile delivery, inventory management, and cold chain storage for temperature-sensitive medications. The need for specialized vehicles, trained personnel, and advanced tracking systems further escalates expenses. Additionally, ensuring timely delivery in remote or underserved areas remains a challenge, as infrastructure limitations can lead to delays and increased operational costs. Balancing efficiency and affordability while maintaining service quality poses a critical challenge for market participants.
Limited Awareness and Trust Among Consumers
Despite the growing adoption of online services, a segment of consumers remains hesitant to use prescription delivery services due to concerns about medication authenticity and delivery reliability. Lack of awareness about the availability and benefits of these services in rural and semi-urban areas further restricts market penetration. Building consumer trust through transparent operations, secure packaging, and consistent service quality is essential for overcoming this challenge.
Technological and Data Security Issues
While technology plays a vital role in driving market growth, it also introduces vulnerabilities related to data breaches and cybersecurity threats. Prescription delivery platforms handle sensitive patient information, making them prime targets for cyberattacks. Ensuring robust data protection measures and complying with privacy regulations, such as HIPAA, adds to the operational burden for companies. Addressing these challenges is crucial for sustaining consumer confidence and market growth.
Market Opportunities:
The Prescription Delivery Services market presents significant growth opportunities driven by evolving consumer preferences and advancements in healthcare technology. The increasing adoption of telemedicine and digital health platforms has created a seamless connection between online consultations and prescription deliveries, enhancing patient convenience. This trend, coupled with the growing prevalence of chronic diseases requiring consistent medication, underscores the need for reliable delivery services. Subscription-based models, offering personalized and recurring deliveries, provide companies an opportunity to improve customer retention and tap into the expanding market for chronic disease management. The rising demand for temperature-controlled delivery solutions for specialized medications, such as biologics and vaccines, further amplifies growth prospects in this sector.
Emerging markets, particularly in Asia-Pacific, Latin America, and the Middle East, offer immense potential for market expansion. Increasing internet penetration, growing disposable incomes, and rapid urbanization are driving the adoption of digital healthcare solutions in these regions. Furthermore, underserved rural and semi-urban areas present an untapped opportunity for companies to expand their reach by addressing infrastructure challenges and raising awareness about the benefits of prescription delivery services. The integration of sustainable practices, such as electric vehicles and eco-friendly packaging, also opens avenues for businesses to differentiate themselves while aligning with global sustainability goals. Companies that invest in innovative technologies, localized delivery networks, and customer-centric solutions are well-positioned to capitalize on these emerging opportunities and secure a competitive edge in the market.
Market Segmentation Analysis:
The Prescription Delivery Services market is segmented by service type, distribution channel, delivery technology, and region, catering to a diverse range of consumer needs and operational frameworks.
By Service Type, prescription drugs dominate the market due to the increasing prevalence of chronic diseases requiring consistent medication management. Wellness supplements and diagnostic kits are also gaining traction as health-conscious consumers prioritize preventive care and home-based health monitoring. Over-the-counter (OTC) drugs remain a significant segment, driven by the rising demand for convenience and accessibility.
By Distribution Channel, retail pharmacies and drug stores lead the market, leveraging their established networks and consumer trust. Healthcare institutions and clinics are significant contributors, particularly for specialized prescriptions and urgent delivery requirements. The integration of e-commerce platforms with traditional pharmacies has further enhanced accessibility and consumer convenience.
By Delivery Technology, physical delivery remains the most widely used method due to its reliability and scalability. However, drone-based delivery is emerging as an innovative solution for improving delivery efficiency, particularly in remote and underserved areas. In-mail delivery is also popular for recurring prescriptions, while other methods are gaining attention as companies explore new technologies to optimize operations.
Segmentation:
By Service Type:
- Prescription Drugs
- Wellness Supplement
- Diagnostic Kits
- OC Drugs
By Distribution Channel:
- Pharmacy Store
- Retail Pharmacy
- Drug Stores
- Healthcare Institutions
- Clinics
By Delivery Technology:
- In-mail Based
- Drone Based
- Physical Delivery
- Others
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America dominates the Prescription Delivery Services market, accounting for approximately 40% of the global market share. This leadership is driven by advanced healthcare infrastructure, high consumer awareness, and widespread adoption of digital health solutions. The United States is a key contributor, supported by significant investments in telemedicine and e-pharmacy platforms, which streamline prescription delivery services. Approximately 70% of U.S. households have adopted online healthcare services, reflecting the convenience of digital solutions. The prevalence of chronic diseases such as diabetes and hypertension, affecting over 60% of the adult population, further fuels demand for home delivery of medications. In Canada, the government’s push for greater access to virtual healthcare and pharmaceutical delivery services is helping meet the needs of its aging population, which constitutes nearly 18% of its residents.
Europe
Europe holds the second-largest share in the market, contributing approximately 30% to the global revenue. Countries such as Germany, France, and the United Kingdom lead the region, driven by an aging population and increasing demand for convenient healthcare solutions. In Germany, where over 20% of the population is aged 65 or older, recurring medication delivery has become a vital service. France has seen a 15% annual increase in online pharmacy adoption, driven by regulatory support for e-prescriptions. In the UK, over 50% of healthcare consumers report preferring online services for routine medication needs, highlighting a shift toward digital health integration.
Asia-Pacific
The Asia-Pacific region is the fastest-growing market, projected to hold a 20% share by 2032. Rapid urbanization, increasing disposable incomes, and growing internet penetration are key drivers of growth. In China, online pharmacy users exceeded 250 million in 2023, demonstrating a significant shift in consumer behavior. India’s e-pharmacy sector has grown by over 20% annually, with urban households leading adoption due to convenience and cost savings. Japan and South Korea also exhibit strong demand for prescription delivery services, with over 25% of their aging populations relying on regular medication delivery through integrated digital platforms.
Latin America, Middle East, and Africa
Latin America, the Middle East, and Africa collectively account for the remaining 10% of the market share, showing steady growth potential. In Latin America, Brazil and Mexico lead adoption due to increasing urbanization, with 40% of urban residents using online health platforms. In the Middle East, countries like the UAE and Saudi Arabia are heavily investing in telemedicine and prescription delivery infrastructure to modernize healthcare systems. In Africa, the growing penetration of mobile connectivity, which reached 70% in 2023, presents untapped opportunities for companies to expand into rural and underserved areas, enabling gradual market expansion.
Key Player Analysis:
- Alto Pharmacy
- Amazon Pharmacy
- Capsule Corporation
- CVS Health Corporation
- Express Scripts Holding Company
- GoodRx Holdings Inc.
- Kroger Co. (Kroger Pharmacy)
- Medly Pharmacy
- Nimble Pharmacy
- OptumRx Inc.
- PillPack LLC
- Rite Aid Corporation
- Truepill Inc.
- Walgreens Boots Alliance Inc.
- Walmart Inc. (Walmart Pharmacy)
Competitive Analysis:
The Prescription Delivery Services market is characterized by intense competition among established players and emerging startups. Key players such as CVS Health, Walgreens Boots Alliance, and Amazon Pharmacy dominate the market with extensive logistics networks, advanced digital platforms, and strong brand recognition. These companies leverage their established presence to provide reliable and scalable delivery solutions, catering to diverse customer needs. For instance, Amazon Pharmacy uses advanced logistics, including daily forecasts to accurately project prescription volumes and demand, achieving better forecasting accuracy than the industry standard. Startups and regional players are increasingly entering the market, focusing on niche segments and innovative solutions such as same-day delivery and subscription-based services. Partnerships with telemedicine providers and local pharmacies are common strategies to expand reach and improve service efficiency. Additionally, investments in technology-driven logistics, including route optimization and real-time tracking, are redefining customer experience. The competitive landscape is further shaped by increasing emphasis on sustainability, with players adopting green delivery practices to gain a competitive edge. The dynamic nature of the market encourages constant innovation to maintain relevance and growth.
Recent Developments:
- In 2023, Michigan Medicine and Zipline collaborated to introduce drone-based delivery of medications using electric drones, benefiting residents in Washtenaw County, United States.
- In 2023, Amazon initiated its drone delivery service for prescription drugs, with College Station, United States, being the first location to access the new service.
- In October 2024, Amazon Pharmacy unveiled plans to expand same-day medication delivery to 20 additional U.S. cities by 2025. This initiative aims to provide same-day delivery to 45% of the U.S. population, targeting cities like Boston, Dallas, Minneapolis, Philadelphia, and San Diego. Modular pharmacies integrated within Amazon Same-Day Delivery sites will address specific community needs.
- In June 2023, CVS Health advanced sustainability efforts by entering renewable energy agreements with Direct Energy and Constellation. The partnerships will power over 547 locations across Texas and Michigan using renewable energy sources, generating over 100,000 megawatt hours of carbon-free electricity annually.
- In January 2023, Hitachi ABB Power Grids introduced a prefabricated containerized gas-insulated substation for Linde in Singapore. This innovation built upon their earlier development of a world-first 400 kV modular mobile substation system, which reduced power restoration time from 18 months to just seven days.
Market Concentration & Characteristics:
The Prescription Delivery Services market exhibits a moderately fragmented structure, with a mix of global leaders and regional players competing for market share. Established companies like CVS Health, Walgreens Boots Alliance, and Amazon Pharmacy hold a significant portion of the market, driven by their extensive logistics infrastructure, advanced digital platforms, and strong consumer trust. However, smaller regional players and emerging startups are carving niches by offering tailored services, such as same-day deliveries and subscription-based models. The market is characterized by rapid technological integration, with AI-driven logistics, real-time tracking, and secure digital platforms becoming standard features. Consumer preferences for convenience, coupled with the growing adoption of telemedicine, are reshaping the industry's dynamics. Additionally, increasing regulatory emphasis on patient data security and medication authenticity is shaping operational standards. The market’s focus on sustainability and eco-friendly practices further highlights its evolving characteristics to meet modern consumer and environmental demands.
Report Coverage:
The research report offers an in-depth analysis based on By Service Type, By Distribution Channel and By Delivery Technology. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Expansion of telemedicine platforms will drive seamless integration with prescription delivery services, enhancing user convenience.
- Increasing adoption of subscription-based models will boost customer retention and support recurring revenue streams.
- Technological advancements, such as AI-driven logistics and autonomous delivery systems, will optimize operations and reduce costs.
- Growing demand for temperature-controlled solutions will expand opportunities in delivering biologics and specialty medications.
- Emerging markets in Asia-Pacific, Latin America, and Africa will witness accelerated growth due to rising internet penetration and urbanization.
- Partnerships between delivery providers and healthcare institutions will enhance service reliability and broaden consumer access.
- The focus on sustainability will lead to the adoption of green logistics, including electric vehicles and eco-friendly packaging.
- Regulatory developments supporting e-prescriptions and digital health adoption will strengthen market growth.
- Increasing awareness and trust among consumers will drive higher adoption in rural and semi-urban areas.
- Investments in personalized delivery services will create value for diverse consumer segments, including chronic disease patients and the elderly.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Prescription Delivery Services market?
What factors are driving the growth of the market?
Which region holds the largest share in the market?
What challenges does the market face?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 215.4 million → 2032: USD 330.57 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Prescription Delivery Services Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Prescription Delivery Services Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Prescription Delivery Services Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Prescription Delivery Services Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Prescription Delivery Services Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Prescription Delivery Services Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Prescription Delivery Services Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Prescription Delivery Services Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 215.4 million → 2032: USD 330.57 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Prescription Delivery Services Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Prescription Delivery Services Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Prescription Delivery Services Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Energy Efficiency and Resource Management
- 14.7 Sustainability, Recycling and Circularity
- 14.8 Technology Roadmap, 2024-2032
- 14.9 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Prescription Delivery Services Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Financial Performance and Investment
- 17.2.6 Market Share and Competitive Position
- 17.2.7 Technology and Innovation Capabilities
- 17.2.8 Strategic Alliances or Partnerships
- 17.2.9 Recent Developments
- 17.2.10 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
