
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Produced Water Treatment Market Size 2023 | USD 8258.2 Million |
| Produced Water Treatment Market, CAGR | 8.30% |
| Produced Water Treatment Market Size 2032 | USD 16925.4 Million |
Market Insights
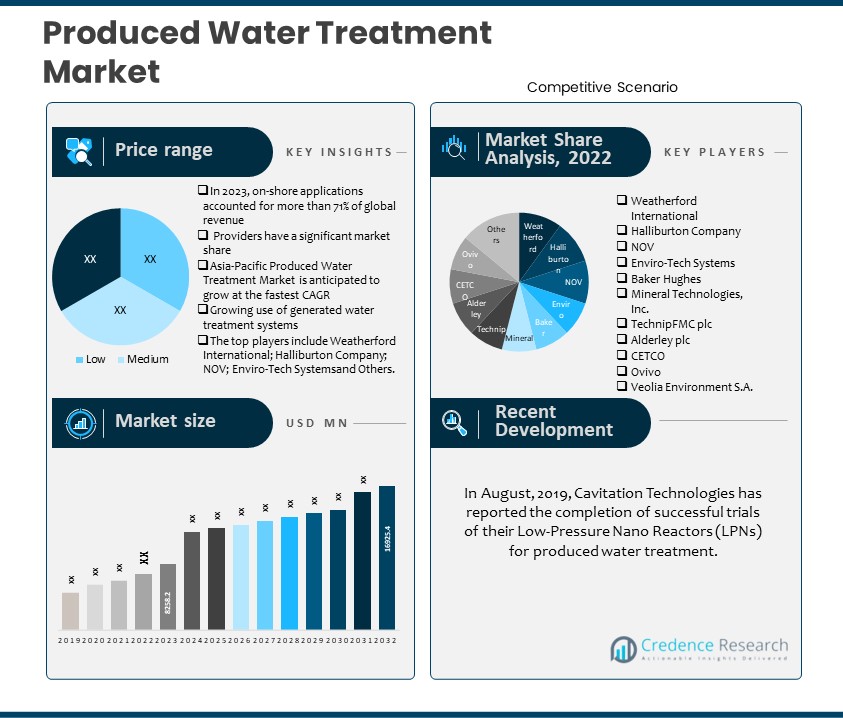
- The global demand for Produced Water Treatment was valued at USD 8258.2 Million in 2023 and is expected to reach USD 16925.4 Million in 2032, growing at a CAGR of 8.30% between 2024 and 2032.
- The physical treatment category had the biggest revenue share in 2023, while the chemical treatment segment is predicted to grow rapidly.
- In 2023, the on-shore application category contributed more than 71% of worldwide revenue, while the offshore application sector is expected to increase at a high CAGR throughout the projection period.
- The oil and gas industry is predicted to have the greatest revenue share of the market, and Water Reuse and Recycling give an important contribution to the Produced Water Treatment Market.
- The Equipment Providers area has a substantial stake, while Chemical Suppliers are another big market group.
- North America dominated the market in 2023, accounting for 42.8% of total revenue, and the Asia-Pacific Produced Water Treatment Market is projected to grow at the fastest CAGR between 2023 and 2032.
- The rising issue of freshwater scarcity promotes market expansion.
- Developing Clean Energy Alternatives to Oil and Gas impedes industry growth
Executive Summary
Market Definition
The concentrated and complex mixture of organic and inorganic components, together with the biggest amount of by-product generated during oil and gas recovery processes, is known as produced water. Over the course of the well's lifetime, the volume of water generated by the wells increases exponentially for dependable energy sources like oil and inversely for unusual energy sources like coal, bead methane gas, and so on. For injection purposes, this water needs to be recycled or treated. There are numerous technologies available for this kind of treatment, such as thermal and membrane filtration technologies, which raises the need for produced water treatment systems.
Market Overview
The global Produced Water Treatment Market has witnessed steady growth in recent years and is expected to grow at a CAGR of 8.30% between 2024 and 2032. The market was valued at USD 8258.2 million in 2023 and is expected to reach USD 16925.4 million in 2032.
The energy sector and stricter environmental rules are the primary drivers of this market's growth. Produced water volumes are expected to increase to about 340 billion containers by the end of 2023, up from more than 202 billion in 2023. 70% of these containers were disposed of, with the remainder re-injected into offshore oil fields. This has been a crucial contributor to the development of increased volumes of generated water in 2023. Furthermore, the rising oil-to-water ratio is likely to maintain demand for efficient produced water treatment systems. In addition, increased unconventional production levels in the oil and gas industry will continue to drive demand for generated water treatment systems.
On the other hand, government policies have shifted to reduce investments in existing technologies while increasing attempts to combat advanced technologies, enhancing demand for produced water treatment systems during the projection period.
Segmentation By Treatment Technology
- The physical treatment segment had the highest revenue share in 2023. Physical treatment technologies like membrane filtration, electrocoagulation, and flotation have advanced technologically, increasing treatment efficiency and dependability and driving adoption even further.
- The chemical treatment segment is expected to increase significantly between 2024 and 2032. Chemical treatments are versatile in targeting a wide range of contaminants, including oil, grease, heavy metals, and organic molecules, making them essential for solving complicated water composition concerns.
Segmentation By Application
- In 2023, the on-shore application category generated more than 71% of global revenue. Produced water is a waste stream generated during onshore oil and gas exploration and production when water is extracted from the reservoir alongside the oil/gas.
- The offshore application sector is predicted to grow at a healthy CAGR over the projection period. Offshore produced water can be re-injected into reservoirs, dumped into the sea after proper treatment, or transported onshore for appropriate treatment and disposal.
Segmentation by End-Use Industry
- The oil and gas industry category is expected to have the largest revenue share of the market throughout the forecast period. The oil and gas segment's revenue increase can be ascribed to the largest demand for produced water treatment in the oil and gas industry, which is caused by the massive amount of produced water generated during extraction.
- Water Reuse and Recycling provide a vital contribution to the Produced Water Treatment Market.
Segmentation By Technology Provider
- The Equipment Providers section has a considerable shareholding. These companies provide the necessary equipment and methods for effectively treating produced water, such as filtration systems, separators, and other treatment technologies.
- Chemical suppliers are another significant market category. Chemicals are frequently employed in the treatment process to improve the efficiency of water treatment systems, remove impurities, and ensure that treated water meets regulatory requirements.
Segmentation by Region
- North America dominated the market in 2023, accounting for 42.8% of total revenue.
- The Asia-Pacific Produced Water Treatment Market is estimated to develop at the quickest CAGR between 2023 and 2032
- The rest of the world, including Latin America, the Middle East, and Africa, supplies the remaining demand for Produced Water Treatment.
North America dominated the market, accounting for 42.8% in 2023. The strong presence of crude oil reserves in the United States and Canada is predicted to enhance demand for water management services. Specifically, the region's thriving oil and gas industry, mainly in the United States and Canada, produces significant amounts of generated water as a byproduct of the extraction process. This excess of produced water demands efficient treatment technologies in order to meet severe environmental standards and compliance. Furthermore, growing worries about water scarcity and contamination highlight the significance of purifying produced water before disposal or reuse.
Furthermore, the Asia-Pacific Produced Water Treatment Market is estimated to develop at the quickest CAGR between 2023 and 2032. This is owing to the increased creation of new technology through innovation, as well as onshore and offshore exploration. Furthermore, China's Produced Water Treatment market had the highest market share, while India's Produced Water Treatment market was the fastest-growing in the Asia-Pacific region.
Key Highlights of the Report
Treatment Technology, Application, End-Use Industry, Source, and Region segments of the global Produced Water Treatment Market. The offshore application market is expected to expand at a solid CAGR, with the physical therapy category having the largest revenue share in 2023. Additionally, the Equipment Providers segment holds a sizeable portion of the market, and Chemical Suppliers constitute another sizable market group and North America, leading the market growth.
Rising global oil and gas production, water scarcity, resource management, and technological advancements are the market's primary drivers. Furthermore, high salinity and TDS (Total Dissolved Solids), the presence of hydrocarbons, and cost constraints are the main restraints of the market.
North America dominated the market in 2023, with 42.8%. The high concentration of crude oil deposits in the United States and Canada is expected to increase demand for water management services. Specifically, the region's expanding oil and gas industry, primarily in the United States and Canada, generates large amounts of produced water as a byproduct of the extraction process. Furthermore, the Asia-Pacific Produced Water Treatment Market is expected to grow at the fastest rate between 2023 and 2032. This is due to the growing development of new technology through innovation, as well as onshore and offshore exploration.
What Are The Main Drivers Of The Global Produced Water Treatment Market?
Rising global oil and gas production, water scarcity and resource management, and technological advancements are key market drivers.
What Are The Major Challenges Faced By The Global Produced Water Treatment Market?
The market's main limits are high salinity and TDS (total dissolved solids), the presence of hydrocarbons, and cost constraints.
What Are The Growth Opportunities In The Global Produced Water Treatment Market?
The market's significant opportunities include increasing demand for advanced technologies, a focus on sustainability and water reuse, and digitalization and automation
Market Drivers
Several factors drive the global Produced Water Treatment Market. The following are the key drivers of the global Produced Water Treatment Market:
Growing Issue Of Freshwater Scarcity
Fresh water supply varies greatly around the globe. Due to a significant scarcity of fresh water, it is necessary to use available water resources wisely. Produced water offers an alternate way to recycle water and use it as fresh water for a variety of applications.
The produced water can be used for various purposes, including cleaning, agriculture, wildlife, and industry. As the global water deficit grows, so does the demand for water treatment, which is likely to fuel the expansion of the worldwide water treatment market.
Market Restraints
The global Produced Water Treatment Market faces some challenges that may hinder its growth. These include the following:
Developing Clean Energy Alternatives To Oil And Gas
The decreasing reliance on oil and gas is likely to limit market growth throughout the projection period. Dependence on oil and gas leads to increased carbon emissions into the environment. Alternative energy solutions for oil and gas are emerging, which are predicted to reduce extraction of oil and gas, resulting in a decrease in the volume of produced water production.
Various governments and groups throughout the world are working to reduce carbon emissions. Renewable energy alternatives such as electric vehicles, solar energy, and other clean energy sources are emerging, which is expected to reduce demand for oil and gas, hence limiting demand for generated water treatment from oil and gas producers.
Opportunities
The global Produced Water Treatment Market offers significant growth opportunities. These include the following:
Development Of Advanced Water Treatment Techniques
The development of innovative procedures for treating generated water is projected to open up profitable potential for key industry players. The world's energy needs are increasing as a result of its growing population and reliance on energy goods. As the primary energy suppliers, oil and gas corporations must continually deliver higher outputs, resulting in increased extraction of produced water.
The oil and gas industry, energy sector, and others generate a huge amount of generated water as waste. Innovative techniques such as dissolved air floatation (DAF) are becoming popular in the treatment of produced water.
DAF is a well-known alternative clarifying method for treating industrial wastewater containing lighter particles like color-causing organics or algae. Several significant participants in the oil and gas business are focusing on using DAF and other new water treatment methods to improve outcomes.
Competitive Landscape
Key Players
The global Produced Water Treatment Market is highly competitive, with several key players. Some of the major players in the market and their market share are as follows:
- Weatherford International
- Halliburton Company
- NOV
- Enviro-Tech Systems
- Baker Hughes
- Mineral Technologies, Inc.
- TechnipFMC plc
- Alderley plc
- CETCO
- Ovivo
- Veolia Environment S.A.
- Schlumberger Limited
- Cannon Artes S.p.A.
These organizations prioritize product innovation, End-Use Industry expansion, and mergers and acquisitions to stay competitive.
The global Produced Water Treatment Market's key players continually seek to stay ahead by offering new products and developments.
In February, 2021, The Egyptian Ministry of Petroleum and Schlumberger have announced the debut of the Egypt Upstream Gateway, an innovative digital platform that will provide access to Egypt's subsurface data.
In March, 2022, Cavitation Technologies and SD Partners have formed a cooperation to promote sustainable water treatment to new businesses. CTi will collaborate with Sustainable Development Partners to market novel applications of its unique technology in produced water treatment using low-pressure nanoreactors (LPN).
In May 2019, The US Department of Energy's (DOE) Office of Fossil Energy has announced up to $5 million in government funding for cost-shared research and development (R&D) projects under financing opportunity announcement (FOA) DE-FOA-0002004, Low Cost, Efficient Treatment Technologies for Produced Water.
Summary of Key Findings
- Development of Advanced Water Treatment Techniques
- The market is segmented by Treatment Technology: Application, End-Use Industry, Source, and region.
- In 2023, the physical treatment segment had the biggest revenue share.
- The Equipment Providers area has a significant stake
- North America is leading in market growth; the market is highly competitive, with key players including Weatherford International; Halliburton Company; NOV; Enviro-Tech Systems and Others.
Future Outlook
- Increased emphasis on water reuse and recycling.
- Advances in technology in treatment processes.
- Increasing environmental rules and compliance requirements.
- The expansion of the oil and gas industry is driving market growth.
- Growing use of generated water treatment systems.
How CXOs Can Benefit from the Credence Research Produced Water Treatment Market Report
The Credence Research Produced Water Treatment Market Report provides CXOs with a comprehensive overview of the market, including:
- Market size and growth forecast: The report provides detailed estimates of the global Produced Water Treatment Market size, segmented By Treatment Technology, Application, End-Use Industry, Technology Provider, and region. It also includes forecasts for the market through 2032 based on key trends and drivers.
- Market segmentation: The report segments the Produced Water Treatment Market By Treatment Technology, Application, End-Use Industry, Technology Provider, and Region. This segmentation provides CXOs with a granular understanding of the market and the opportunities in each segment.
- Competitive Landscape: The report profiles the key players in the Produced Water Treatment Market and provides insights into their strategies, product offerings, and financial performance. This information can help CXOs to identify and assess their competition.
- Key trends and drivers: The report identifies and analyzes the key trends and drivers shaping the Produced Water Treatment Market. This information can help CXOs make informed decisions about their investments and strategies.
CXOs can use the insights from the Credence Research Produced Water Treatment Market Report to:
- Identify growth opportunities: The report can help CXOs identify new growth opportunities in the Produced Water Treatment Market. By analyzing the data and trends in the report, they can make informed decisions about where to invest and expand their business.
- Make informed investment decisions: The report can help CXOs make informed investment decisions about Produced Water Treatment. For example, it may provide useful insights into market trends, customer preferences, the competitive landscape, and growth prospects in the mobile accessories business..
- Develop competitive strategies: The report can help CXOs develop competitive strategies for their Produced Water Treatment businesses. For example, by analyzing market trends, client preferences, and the competitive environment mentioned in the report, CXOs can fine-tune their strategies, differentiate their offers, and effectively position their firms in the marketplace.
- Track market developments: The report can help CXOs monitor market developments and stay ahead of the curve. For example, it provides insights into the latest trends and innovations in the Produced Water Treatment Market.
Overall, the Credence Research Produced Water Treatment Market Report is a valuable source for CXOs who are looking to gain a deeper understanding of the market and identify opportunities for growth.
Segmentation
- By Treatment Technology:
- Physical Treatment
- Chemical Treatment
- Biological Treatment
- Membrane Treatment
- Electrocoagulation
- Advanced Oxidation Processes (AOPs)
- By Application:
- Onshore Produced Water Treatment
- Offshore Produced Water Treatment
- Enhanced Oil Recovery (EOR) Water Treatment
- Oil Sands Produced Water Treatment
- Coal Bed Methane (CBM) Produced Water Treatment
- By End-Use Industry:
- Oil and Gas Industry
- Water Reuse and Recycling
- Environmental Remediation
- Municipal and Industrial Wastewater Treatment
- Desalination
- By Technology Provider:
- Equipment Providers
- Chemical Suppliers
- Engineering, Procurement, and Construction (EPC) Contractors
- Consulting and Service Providers
- Technology Developers
- By Region
- North America
- The U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
- North America

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Issue of Freshwater Scarcity
Increasing global water scarcity is compelling industries, especially oil and gas, to adopt produced water treatment solutions to recycle and reuse water, reducing dependence on limited freshwater resources.
Expansion of Oil and Gas Production
Rising oil and gas exploration and production activities, particularly in North America and Asia Pacific, are generating larger volumes of produced water, thereby driving demand for advanced treatment technologies.
Stricter Environmental Regulations
Governments worldwide are enforcing more stringent discharge and reuse standards for produced water, pushing oil and gas operators to invest in efficient treatment systems to ensure compliance and avoid penalties.
Technological Advancements in Treatment Methods
Innovations such as membrane filtration, electrocoagulation, and advanced oxidation processes are improving the efficiency and cost-effectiveness of produced water treatment, encouraging broader adoption across the industry.
Focus on Water Reuse and Sustainability
There is a growing emphasis on sustainable water management practices, with companies seeking to minimize environmental impact by reusing treated produced water for industrial, agricultural, or reinjection purposes.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the global Produced Water Treatment Market?
What is the expected growth rate of the Produced Water Treatment Market between 2024 and 2032?
Which segment is leading the market share in terms of Application?
Which Treatment Technology segment governs the demand for Produced Water Treatment in the world?
Who are the major players in the global Produced Water Treatment Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Application
- 1.2.1 Onshore Produced Water Treatment
- 1.2.2 Offshore Produced Water Treatment
- 1.2.3 Enhanced Oil Recovery (EOR) Water Treatment
- 1.2.4 Oil Sands Produced Water Treatment
- 1.2.5 Coal Bed Methane (CBM) Produced Water Treatment
- 1.3 By End-Use Industry
- 1.3.1 Oil and Gas Industry
- 1.3.2 Water Reuse and Recycling
- 1.3.3 Environmental Remediation
- 1.3.4 Municipal and Industrial Wastewater Treatment
- 1.3.5 Desalination
- 1.4 By Technology Provider
- 1.4.1 Equipment Providers
- 1.4.2 Chemical Suppliers
- 1.4.3 Engineering, Procurement, and Construction (EPC) Contractors
- 1.4.4 Consulting and Service Providers
- 1.4.5 Technology Developers
- 1.5 By Treatment Technology
- 1.5.1 Physical Treatment
- 1.5.2 Chemical Treatment
- 1.5.3 Biological Treatment
- 1.5.4 Membrane Treatment
- 1.5.5 Electrocoagulation
- 1.5.6 Advanced Oxidation Processes (AOPs)
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 8258.2 Million → 2032: USD 16,925.4 Million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Produced Water Treatment Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Produced Water Treatment Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Produced Water Treatment Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Produced Water Treatment Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Produced Water Treatment Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Produced Water Treatment Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Produced Water Treatment Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Produced Water Treatment Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 8258.2 Million → 2032: USD 16,925.4 Million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Produced Water Treatment Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Application - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Onshore Produced Water Treatment
- 12.3.7.2 Offshore Produced Water Treatment
- 12.3.7.3 Enhanced Oil Recovery (EOR) Water Treatment
- 12.3.7.4 Oil Sands Produced Water Treatment
- 12.3.7.5 Coal Bed Methane (CBM) Produced Water Treatment
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End-Use Industry - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Oil and Gas Industry
- 12.4.7.2 Water Reuse and Recycling
- 12.4.7.3 Environmental Remediation
- 12.4.7.4 Municipal and Industrial Wastewater Treatment
- 12.4.7.5 Desalination
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Technology Provider - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Equipment Providers
- 12.5.7.2 Chemical Suppliers
- 12.5.7.3 Engineering, Procurement, and Construction (EPC) Contractors
- 12.5.7.4 Consulting and Service Providers
- 12.5.7.5 Technology Developers
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Treatment Technology - Market Size and Forecast, 2023-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2023-2032
- 12.6.4 Volume Forecast, 2023-2032
- 12.6.5 Base-Year Market Share, 2023
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Physical Treatment
- 12.6.7.2 Chemical Treatment
- 12.6.7.3 Biological Treatment
- 12.6.7.4 Membrane Treatment
- 12.6.7.5 Electrocoagulation
- 12.6.7.6 Advanced Oxidation Processes (AOPs)
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Produced Water Treatment End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Produced Water Treatment Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Share, 2023
- 14.2 Regional Market Forecast, 2023-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Produced Water Treatment Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Produced Water Treatment Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Weatherford International
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Halliburton Company
- 18.4 NOV
- 18.5 Enviro-Tech Systems
- 18.6 Baker Hughes
- 18.7 TechnipFMC plc
- 18.8 Veolia Environment S.A.
- 18.9 Schlumberger Limited
- 18.10 Ovivo
- 18.11 CETCO
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

