
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
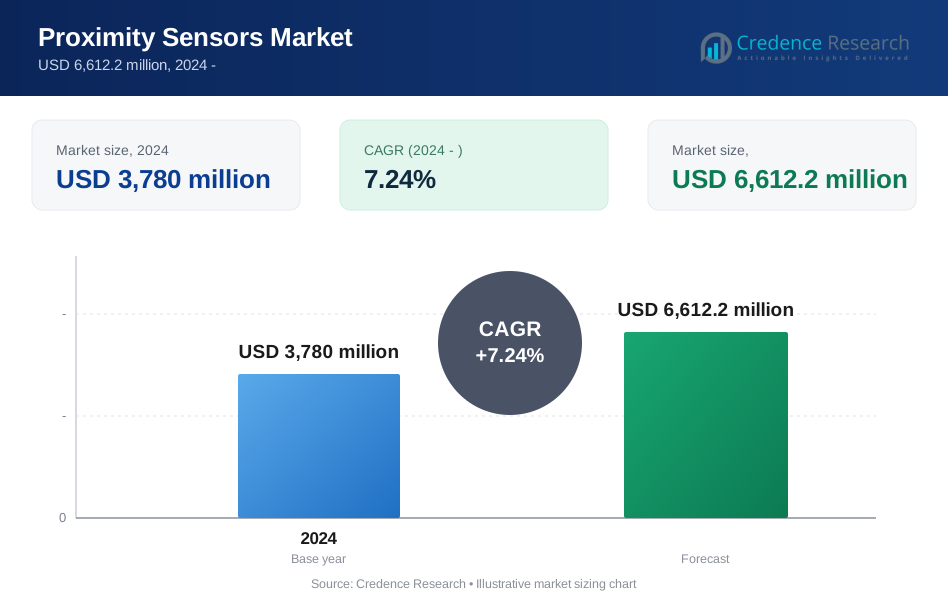
| Proximity Sensors Market Size 2024 | USD 3,780 million |
| Proximity Sensors Market, CAGR | 7.24% |
| Proximity Sensors Market Size 2032 | USD 6,612.2 million |
Market Overview:
The Proximity Sensors Market is projected to grow from USD 3,780 million in 2024 to approximately USD 6,612.2 million by 2032, with a CAGR of 7.24% over the forecast period. Proximity sensors, which detect the presence or absence of objects without physical contact, are critical components in various industries, including automotive, consumer electronics, industrial manufacturing, and healthcare. These sensors enhance automation, safety, and operational efficiency, fueling their widespread adoption. Growth is driven by increasing demand for automation in manufacturing, the expanding automotive sector with advancements in driver-assistance systems, and the proliferation of consumer devices that rely on proximity detection for intuitive interfaces.
Key drivers for growth in the proximity sensors market include the rise in industrial automation, as manufacturers seek solutions to improve productivity and reduce operational downtime. The automotive industry also significantly contributes to demand, with proximity sensors being integral to advanced driver-assistance systems (ADAS) and autonomous driving technologies. Additionally, the adoption of proximity sensors in smartphones and consumer electronics, which enable features like gesture recognition and touchless operation, supports market expansion. The increasing focus on safety and energy efficiency across sectors further boosts the adoption of proximity sensors, as these devices help streamline processes and conserve energy.
Regionally, Asia-Pacific holds the largest share of the Proximity Sensors Market, driven by rapid industrialization, growth in automotive production, and high demand for consumer electronics in countries like China, Japan, and South Korea. North America follows, with robust demand in the automotive and aerospace industries, particularly in the United States, where automation and safety standards drive sensor adoption. Europe also represents a significant market, led by Germany and France, as automation in manufacturing and the growth of the electric vehicle sector boost demand. Meanwhile, Latin America, the Middle East, and Africa are emerging markets, where rising investments in industrial automation and infrastructure are expected to drive future demand for proximity sensors.
Market Drivers:
Rising Demand for Industrial Automation:
The increasing adoption of automation across manufacturing industries is a primary driver of the Proximity Sensors Market. As industries strive to enhance productivity and reduce downtime, proximity sensors are widely used for detecting object presence, positioning, and machine alignment. For instance, a 2023 survey by the U.S. Department of Commerce reported that over 70% of manufacturing firms implemented proximity sensors as part of automation initiatives to improve efficiency. This trend toward automated systems aligns with manufacturers’ goals to streamline operations and achieve high levels of accuracy.
Expansion of Advanced Driver-Assistance Systems (ADAS) in Automotive:
Proximity sensors play a crucial role in the automotive industry, particularly in advanced driver-assistance systems (ADAS) for features like parking assistance, blind-spot detection, and collision avoidance. As the automotive industry continues to move toward semi-autonomous and fully autonomous vehicles, the integration of high-precision proximity sensors becomes increasingly essential. For instance, Bosch, a major automotive supplier, launched a new line of proximity sensors specifically designed to enhance safety in ADAS, underscoring the critical role these sensors play in the automotive sector.
Growth in Consumer Electronics Adoption:
The rise of smart devices and wearable technology has fueled demand for proximity sensors in consumer electronics. Smartphones, tablets, and wearables use these sensors for features like gesture control, face recognition, and touchless operation. For instance, Apple’s iPhone models include proximity sensors that detect when the phone is near the user’s ear, adjusting the display accordingly. This widespread use of proximity sensors enhances user experience, reduces power consumption, and contributes to the growth of this technology in the consumer electronics sector.
Emphasis on Energy Efficiency and Safety Standards:
Growing attention to safety and energy efficiency across various sectors is also driving the adoption of proximity sensors. These sensors support energy-saving practices by detecting idle equipment and powering down machinery when not in use, helping companies meet regulatory standards and sustainability goals. For example, the European Union’s stringent energy standards for industrial equipment encourage manufacturers to adopt proximity sensors to monitor and control energy consumption, supporting eco-friendly practices. This focus on sustainable and safe operations is strengthening the demand for proximity sensors in multiple industries.
Market Trends:
Increasing Integration of IoT and Connectivity:
A significant trend in the Proximity Sensors Market is the integration of Internet of Things (IoT) technology, enabling sensors to connect seamlessly with larger networks and facilitate real-time data sharing. This connectivity allows for predictive maintenance, remote monitoring, and data-driven insights, enhancing productivity across industries. For instance, in 2023, Siemens introduced a line of IoT-enabled proximity sensors for manufacturing applications, allowing operators to monitor sensor performance and equipment status remotely. This integration supports the broader adoption of smart factories and Industry 4.0 initiatives.
Miniaturization and Enhanced Sensitivity:
Miniaturization of proximity sensors, along with advances in sensitivity, is making these sensors more versatile for applications in compact and high-precision devices. This trend is especially prominent in the consumer electronics and automotive sectors, where smaller, more sensitive sensors enable sleek designs and advanced features. For example, Sony’s 2022 release of ultra-compact proximity sensors for smartphones and wearables highlights the demand for high-performance sensors that occupy minimal space. Miniaturized sensors improve device functionality without compromising design, contributing to their growing use in modern electronics.
Rising Adoption of Touchless and Gesture-Based Interfaces:
As touchless technology becomes more desirable, particularly in consumer electronics and automotive interiors, proximity sensors are increasingly being used to support gesture-based interfaces. These interfaces allow users to control devices without physical contact, enhancing convenience and hygiene. For instance, Samsung introduced a proximity-sensing feature in its home appliances, enabling users to operate devices with hand gestures. This trend toward touchless controls is expected to expand, driven by user demand for hands-free interaction in various settings, from household appliances to vehicle infotainment systems.
Growing Focus on Environmental and Safety Compliance:
Environmental and safety compliance are driving demand for proximity sensors that meet high regulatory standards. In industries like manufacturing, construction, and transportation, proximity sensors help ensure safe distances between machines and operators, reducing accident risks. Additionally, sensors with energy-efficient features align with global sustainability goals. For example, the European Commission’s updated safety regulations in 2023 emphasized the use of advanced sensing technologies to minimize workplace hazards. As companies prioritize safe and sustainable practices, proximity sensors that support these initiatives are becoming essential components across industries.
Market Challenges Analysis:
High Costs and Complex Implementation:
One of the main challenges in the Proximity Sensors Market is the high initial cost and complexity involved in implementing advanced sensor systems. Modern proximity sensors, especially those with IoT capabilities and enhanced sensitivity, require significant investment, which can be prohibitive for small and medium-sized enterprises (SMEs). Additionally, the U.S. Department of Commerce has reported that integrating these sensors with existing infrastructure often demands customized solutions and technical expertise, further driving up costs and complicating implementation for many businesses.
Sensitivity to Environmental Interference:
Proximity sensors are prone to interference from environmental factors such as extreme temperatures, dust, and humidity, which can impact their accuracy and reliability. In industrial settings, for example, sensors exposed to high heat or moisture may require frequent calibration or replacement, adding to maintenance costs. The National Institute of Standards and Technology (NIST) in the United States highlights that sensor accuracy can be affected by electromagnetic interference, a challenge in sectors like manufacturing where electronic equipment is densely packed. This sensitivity can limit the use of proximity sensors in harsh environments, posing a restraint on market growth.
Limited Compatibility with Legacy Systems:
Many industries still rely on legacy systems that are incompatible with modern proximity sensor technologies, especially those equipped with IoT and real-time data monitoring features. Integrating proximity sensors with outdated systems often requires additional hardware or software updates, which can be costly and technically challenging. For example, the European Commission’s Digital Transformation Initiative has noted that industries with extensive legacy infrastructure face significant obstacles when implementing new technologies, including proximity sensors. This compatibility issue can slow down adoption, particularly in traditional sectors resistant to upgrading existing systems.
Regulatory and Compliance Challenges:
Proximity sensors used in safety-critical industries such as automotive and healthcare are subject to strict regulatory standards, requiring rigorous testing and certification. Meeting these standards can be resource-intensive for manufacturers, as compliance processes mandated by authorities like the U.S. Food and Drug Administration (FDA) for medical devices or the National Highway Traffic Safety Administration (NHTSA) for automotive applications can delay product launches. This regulatory burden can limit the pace at which new sensor technologies reach the market, impacting innovation and competitiveness within the proximity sensors industry.
Market Segmentation Analysis:
By Type
The Proximity Sensors Market is segmented by type into inductive, capacitive, ultrasonic, photoelectric, and magnetic proximity sensors. Inductive sensors hold a significant share due to their effectiveness in detecting metallic objects, making them ideal for manufacturing and automotive applications. Capacitive sensors, with their versatility in detecting various materials, are widely used in packaging and logistics. Ultrasonic sensors, known for their high accuracy, are growing in demand for applications requiring non-contact measurement, particularly in healthcare and robotics.
By Technology
By technology, the market is categorized into contact and non-contact proximity sensors. Non-contact sensors, such as photoelectric and ultrasonic types, dominate the market as they provide greater durability and longevity by minimizing wear and tear. The integration of IoT capabilities in non-contact sensors is also driving their adoption across industries seeking automated monitoring solutions. Contact sensors, while limited to specific uses, remain relevant in applications where durability is less critical.
By End User
End users of proximity sensors include industries such as automotive, consumer electronics, manufacturing, aerospace, and healthcare. The automotive sector is a major contributor, utilizing proximity sensors in advanced driver-assistance systems (ADAS) and automated parking solutions. Consumer electronics also represent a significant segment, with sensors enhancing user interaction in devices like smartphones and tablets. Manufacturing and aerospace sectors rely on proximity sensors to improve operational efficiency and safety, while healthcare benefits from applications in diagnostics and patient monitoring, underscoring the broad utility of proximity sensors across multiple domains.
Segmentations:
By Technology
- Inductive
- Capacitive
- Photoelectric
- Magnetic
By End-user Industry
- Aerospace & Defence
- Automotive
- Industrial
- Consumer Electronics
- Food & Beverage
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
Asia-Pacific
Asia-Pacific holds the largest share of the Proximity Sensors Market, accounting for approximately 35% of the global market. This region's dominance is driven by rapid industrialization, particularly in China, Japan, and South Korea, where proximity sensors are increasingly adopted across manufacturing, automotive, and electronics sectors. China, with its extensive manufacturing base, is a key contributor, using proximity sensors to enhance automation and efficiency. Japan leads in consumer electronics, where proximity sensors are widely integrated into devices for gesture control and touchless interaction. Additionally, the rise of electric vehicles and advanced driver-assistance systems (ADAS) in the region fuels demand, positioning Asia-Pacific as a significant market for advanced sensor technology.
North America
North America represents approximately 30% of the global Proximity Sensors Market share, with demand largely driven by the automotive and aerospace industries. The United States leads the region due to its high adoption of automation in manufacturing and stringent safety standards in automotive applications. Proximity sensors are widely used in ADAS, supporting the trend toward autonomous driving and enhancing driver safety. The aerospace industry in North America also relies on proximity sensors for aircraft maintenance and safety operations, contributing to the demand. Additionally, the presence of prominent sensor manufacturers and increased focus on IoT and Industry 4.0 initiatives in the U.S. are supporting the region’s strong position in the global market.
Europe
Europe holds around 20% of the global Proximity Sensors Market share, driven by the region’s focus on industrial automation and stringent safety regulations. Germany, France, and the United Kingdom lead the market in Europe, where proximity sensors are widely adopted in manufacturing, automotive, and consumer electronics. Germany, as a leader in automotive manufacturing, integrates proximity sensors for enhanced safety and efficiency in both production processes and vehicle systems. The European Union’s regulatory emphasis on workplace safety and energy efficiency also supports the adoption of proximity sensors in industrial applications. Additionally, the region’s push toward electric vehicles and advanced automation solutions fuels demand for high-precision sensing technology.
Latin America, Middle East, and Africa
LAMEA accounts for approximately 15% of the global market share, with rising demand as industries adopt automation technologies and improve infrastructure. In Latin America, Brazil and Mexico drive the market, particularly in automotive and manufacturing sectors where proximity sensors support operational efficiency and worker safety. The Middle East, led by Saudi Arabia and the UAE, experiences growing demand in oil and gas and construction, where proximity sensors are essential for monitoring equipment and ensuring safety. Africa, though a smaller market, shows growth potential as digitalization and automation efforts increase across industries. Investments in smart infrastructure and industrial automation in these regions position LAMEA as a promising market for proximity sensors.
Key Player Analysis:
- Omron Corporation
- Honeywell International Inc.
- Rockwell Automation, Inc.
- Schneider Electric SE
- Panasonic Corporation
- Sick AG
- Texas Instruments Inc.
- IFM Electronic GmbH
- STMicroelectronics N.V.
- Broadcom Inc.
Competitive Analysis:
The Proximity Sensors Market is highly competitive, led by established players like Omron, Honeywell, and Rockwell Automation, who leverage strong R&D capabilities and broad product portfolios to address diverse industry needs. These leaders focus on innovation, particularly in IoT-enabled and miniaturized sensor technologies, to meet rising demands for real-time data integration and compact design in automotive, consumer electronics, and industrial automation applications. Companies like Sick AG and IFM Electronic GmbH emphasize specialized sensing solutions tailored to safety and precision, strengthening their presence in key sectors. Newer entrants and regional competitors add to market dynamics by providing cost-effective solutions, especially in emerging markets with growing automation needs. Strategic partnerships and acquisitions are common, as companies seek to expand technology capabilities and global reach. Overall, competition in this market pushes continuous advancements in sensor performance, durability, and connectivity, meeting evolving expectations for efficiency and safety across applications.
Recent Developments:
- Omron launched its advanced industrial automation solutions in 2024, which include proximity sensors integrated with IoT capabilities. This line supports predictive maintenance and enables manufacturers to monitor sensor performance in real time, enhancing efficiency in production lines across industries.
- Rockwell Automation partnered with Ericsson in 2023 to introduce 5G-enabled proximity sensors for industrial applications, allowing real-time data collection over secure networks. This collaboration aims to improve flexibility and efficiency in manufacturing processes by leveraging 5G for seamless, high-speed communication.
- Honeywell released a new series of self-diagnostic proximity sensors in 2022 designed for the aerospace industry. These sensors help reduce maintenance costs by eliminating false readings, providing greater reliability and operational efficiency in aircraft systems.
- Schneider Electric introduced energy-efficient proximity sensors in 2023, focusing on sustainable design and improved power management. These sensors are geared towards the manufacturing sector, where energy savings are increasingly prioritized as part of broader sustainability goals.
Market Concentration & Characteristics:
The Proximity Sensors Market is moderately concentrated, led by key players such as Omron, Honeywell, Rockwell Automation, and Schneider Electric, who dominate due to their strong R&D capabilities, advanced product portfolios, and extensive global reach. These established companies focus on developing high-performance sensors that integrate IoT and smart connectivity, catering to the rising demand for automation and real-time data monitoring across industries. High entry barriers, including the need for technological expertise, regulatory compliance, and significant investment in product development, limit new entrants, favoring established players. The market is characterized by continuous innovation, with an emphasis on miniaturization, energy efficiency, and enhanced durability. Additionally, collaborations between sensor manufacturers and technology firms are becoming common, enabling comprehensive solutions that meet diverse industry needs. This competitive landscape encourages advancements in sensor reliability, precision, and compatibility with digital platforms, driving the market’s evolution in an increasingly automated world.
Report Coverage:
The research report offers an in-depth analysis based on Technology, End-user Industry, and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand for IoT-enabled proximity sensors will grow as industries increasingly prioritize real-time data and automation.
- The automotive sector will drive innovation, especially with sensors tailored for ADAS and autonomous vehicle applications.
- Miniaturization of sensors will become essential, particularly in consumer electronics, where space is limited.
- Increased adoption in industrial automation will expand the use of proximity sensors for predictive maintenance and operational efficiency.
- Energy-efficient designs will gain traction, aligning with global sustainability goals across various sectors.
- The aerospace industry will increasingly utilize advanced proximity sensors to improve safety and reduce maintenance costs.
- Integration of 5G technology in proximity sensors will enable faster, more reliable data transmission, supporting complex industrial applications.
- Growth in smart home and building automation will elevate demand for proximity sensors in home appliances and security systems.
- Emerging markets in Asia-Pacific and Latin America will experience rapid adoption as automation infrastructure advances.
- Partnerships between sensor manufacturers and technology firms will accelerate innovation, enhancing the capabilities and versatility of proximity sensors across applications.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Proximity Sensors market?
What factors are driving the growth of the Proximity Sensors market?
What are some challenges faced by the Proximity Sensors market?
Who are the major players in the Proximity Sensors market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Proximity Sensors Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Proximity Sensors Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (the forecast period) (2024: USD 3,780 million → forecast year: USD 6,612.2 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Proximity Sensors Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Proximity Sensors Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Proximity Sensors Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Proximity Sensors Market Drivers
- 3.3 Proximity Sensors Market Restraints & Challenges
- 3.4 Proximity Sensors Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Proximity Sensors Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Proximity Sensors Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Proximity Sensors category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Proximity Sensors Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Proximity Sensors Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Proximity Sensors market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Proximity Sensors Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Proximity Sensors Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Proximity Sensors Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Proximity Sensors (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Proximity Sensors Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Proximity Sensors Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Proximity Sensors Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Proximity Sensors Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Proximity Sensors Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Proximity Sensors Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Proximity Sensors Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Proximity Sensors Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Proximity Sensors Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
