
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Ready to Move in Homes Market Size 2024 | USD 622,340 million |
| Ready to Move in Homes Market, CAGR | 7% |
| Ready to Move in Homes Market Size 2032 | USD 1,069,295.98 million |
Market Overview:
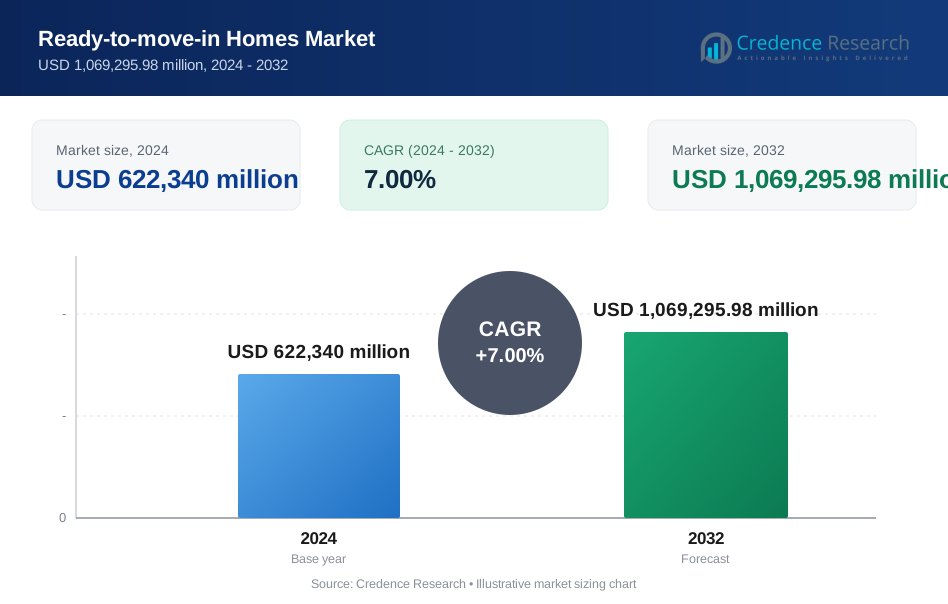
The Ready to Move in Homes Market is poised for significant growth, with its market size projected to increase from USD 622,340 million in 2024 to approximately USD 1,069,295.98 million by 2032, reflecting a compound annual growth rate (CAGR) of 7%. This expansion is driven by the rising preference among homebuyers for ready-to-occupy properties, which offer immediate availability, reduced construction-related uncertainties, and lower financial risks. The market's rapid growth highlights the demand for convenience and speed in residential real estate transactions, particularly as more buyers seek hassle-free solutions to housing needs.
Key market drivers include the increasing demand for properties that eliminate the lengthy construction process, cater to rapid urbanization, and meet the rising demand for housing in metropolitan areas. Changing consumer lifestyles, coupled with the desire for minimal waiting times and turnkey solutions, are fueling demand for ready-to-move-in homes. Additionally, economic stability, attractive financing options, and government initiatives promoting affordable housing are supporting market growth. Real estate developers are increasingly focusing on quality assurance and transparency, which further enhances buyer confidence and strengthens market adoption.
Regionally, the Asia-Pacific region holds a significant share of the Ready to Move in Homes Market, driven by rapid urbanization, high population density, and strong demand in countries such as China and India. North America also represents a substantial market, fueled by robust housing demand, favorable economic conditions, and the presence of established real estate developers. Europe continues to see steady growth, particularly in urban centers where ready-to-move-in properties cater to the demand for convenience and immediate occupancy. Latin America, the Middle East, and Africa are witnessing gradual market expansion due to modernization initiatives, rising urbanization, and increasing awareness of the benefits of ready-to-move-in homes.
Market Drivers:
Rising Urbanization and Population Growth:
The rapid pace of urbanization and population growth is a key driver for the Ready to Move in Homes Market. Increasing migration to urban centers has led to heightened demand for housing solutions that offer convenience and immediate occupancy. According to the United Nations, by 2022, over 56% of the global population resided in urban areas, with projections indicating this figure will surpass 60% by 2030. This demographic shift has spurred demand for ready-to-move-in homes, as they cater to the urgent housing needs of urban populations, eliminating lengthy construction periods.
Convenience and Time Efficiency:
Modern homebuyers increasingly prioritize convenience, seeking properties that minimize waiting times and construction delays. Ready-to-move-in homes provide a turnkey solution, allowing buyers to bypass the typical delays associated with construction. For instance, a 2023 survey by the National Association of Realtors (NAR) in the United States found that 65% of respondents preferred ready-to-move-in homes due to their immediate availability and lower risk of unexpected costs. This demand for convenience has prompted developers to offer high-quality, pre-built housing options that appeal to buyers seeking swift occupancy.
Increased Focus on Quality Assurance:
Ready-to-move-in homes offer greater transparency and quality assurance compared to under-construction properties. Buyers can inspect the property before purchase, ensuring it meets their expectations and adheres to regulatory standards. For example, in 2022, the Real Estate Regulatory Authority (RERA) in India reported a 20% increase in consumer preference for ready-to-move-in properties due to enhanced trust in construction quality and compliance with building codes. This assurance has strengthened market confidence and driven increased adoption.
Favorable Financing Options and Government Initiatives:
Attractive financing options and supportive government policies have bolstered demand for ready-to-move-in homes. Governments worldwide have introduced schemes and incentives to make housing more affordable and accessible. In 2023, the U.S. Department of Housing and Urban Development (HUD) highlighted increased access to low-interest loans and mortgage support programs, which significantly boosted homeownership rates. These incentives enable buyers to acquire properties more readily, driving market growth for move-in-ready homes.
Market Trends:
Growth in Demand for Turnkey Solutions:
The demand for turnkey housing solutions is on the rise, driven by buyers' preference for ready-to-move-in properties that eliminate the uncertainties of the construction process. This trend is particularly evident among first-time homebuyers and professionals relocating for work. According to a 2023 report from the U.S. Census Bureau, 70% of home purchases in metropolitan areas involved ready-to-move-in properties. Real estate developers are capitalizing on this demand by offering homes with modern amenities, minimal maintenance requirements, and seamless move-in experiences.
Emphasis on Sustainable and Smart Homes:
Sustainability and smart technology integration have become defining trends in the ready-to-move-in homes market. Developers are incorporating eco-friendly features such as energy-efficient lighting, water conservation systems, and green building materials to cater to environmentally conscious buyers. In 2022, a survey conducted by the European Commission found that 40% of homebuyers preferred homes equipped with sustainable features. Additionally, smart home automation systems are increasingly being offered as part of ready-to-move-in packages, enhancing convenience, security, and energy management for homeowners.
Increasing Preference for Gated Communities:
Gated communities offering ready-to-move-in homes have gained popularity due to their enhanced security, amenities, and community-focused living. These communities often include parks, gyms, and other shared facilities, creating a self-contained environment that appeals to families and individuals alike. For example, in 2023, a study by India's Housing Ministry revealed that 60% of homebuyers in urban centers preferred homes within gated communities due to perceived safety and quality of life benefits.
Rise in Online Real Estate Platforms:
The growth of online real estate platforms has made it easier for buyers to explore, compare, and purchase ready-to-move-in homes. Virtual tours, detailed property listings, and online transactions have streamlined the homebuying process. For instance, In 2022, Zillow reported a 30% increase in online property viewings for ready-to-move-in homes compared to traditional listings. This shift toward digital solutions has enhanced market accessibility and transparency, further driving buyer interest in ready properties.
Market Challenges Analysis:
High Initial Costs and Affordability Issues:
One of the primary restraints in the Ready to Move in Homes Market is the high initial cost of these properties compared to under-construction homes. Ready-to-move-in homes often come with a premium price tag due to their immediate availability and finished condition, which can be a barrier for cost-sensitive buyers, particularly first-time homebuyers. The U.S. Department of Housing and Urban Development (HUD) has highlighted that affordability remains a key challenge, especially in high-demand metropolitan areas where home prices have continued to rise. This limits the accessibility of ready-to-move-in homes for a broader segment of potential buyers.
Limited Supply and High Demand Dynamics:
The market faces challenges related to limited supply and high demand, which often leads to increased competition among buyers and rising property prices. Real estate developers may find it difficult to maintain a consistent inventory of ready-to-move-in homes due to lengthy construction and regulatory approval processes. For example, the National Housing Federation (NHF) in the United Kingdom has noted that housing supply constraints have intensified in urban areas, resulting in heightened competition and limited options for buyers seeking ready-to-move-in properties.
Regulatory Hurdles and Compliance Issues:
Navigating complex regulatory requirements and compliance standards poses a significant challenge for developers in the ready-to-move-in homes market. Obtaining building permits, adhering to zoning laws, and meeting safety and environmental regulations can delay project completion and increase costs. Regulatory authorities such as the Real Estate Regulatory Authority (RERA) in India emphasize the importance of compliance to ensure consumer protection, but the administrative burden can slow down project delivery, affecting the availability and affordability of ready-to-move-in properties.
Economic Volatility and Market Risks:
Economic fluctuations and market risks, such as changes in interest rates, inflation, and economic downturns, can negatively impact buyer purchasing power and market stability. The International Monetary Fund (IMF) has noted that economic uncertainty can deter investments in real estate, including ready-to-move-in homes, as buyers and developers adopt a more cautious approach to large financial commitments.
Market Segmentation Analysis:
By Type
The Ready to Move in Homes Market is segmented by type into apartments and independent houses. The apartment segment holds a significant market share, driven by strong demand in urban areas where space constraints and high population density favor multi-unit dwellings. Apartments offer a range of amenities, enhanced security, and community living, making them a preferred choice for families, professionals, and retirees. Independent houses, on the other hand, cater to buyers seeking privacy, personalized space, and the freedom to make custom modifications. This segment remains popular in suburban and rural areas, where land availability is less constrained.
By Technology
Segmentation by technology includes conventional construction methods and modern construction technologies, such as prefabrication and modular construction. Modern construction technologies are gaining traction due to their ability to reduce construction timelines, minimize waste, and improve quality. Prefabricated and modular ready-to-move-in homes offer high precision and consistent quality, meeting the growing demand for efficient housing solutions in rapidly developing regions.
By End User
End-user segmentation encompasses first-time homebuyers, investors, and families. First-time homebuyers represent a substantial market share, driven by the convenience and reduced risks associated with ready-to-move-in properties. Investors are increasingly attracted to these properties due to their potential for immediate rental income and minimal holding costs. Families often prioritize ready-to-move-in homes for their convenience, security, and ability to meet immediate housing needs without the uncertainty of construction delays.
Segmentations:
By Type
- Affordable Homes
- Luxury Homes
- Super-Luxury Homes
By Unit Size
- 1,000 Sq. Ft- 2,000 Sq. Ft
- 2,000 Sq. Ft- 3,000 Sq. Ft
- 3,000 Sq. Ft and above
By End User
- Residential Buyer
- Corporate/Commercial Buyer
By Region
- North America
-
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
Asia-Pacific
The Asia-Pacific region holds a significant share of the Ready to Move in Homes Market, accounting for approximately 40% of the global market. This dominance is driven by rapid urbanization, population growth, and rising demand for housing in major countries like China, India, and Japan. In China, strong government support for urban housing development and a focus on modern infrastructure have fueled demand for ready-to-move-in homes. India’s increasing middle-class population and government initiatives such as “Housing for All” have further accelerated market growth. The rising preference for convenience, coupled with favorable financing options and tax incentives, strengthens the adoption of ready-to-move-in homes in the region.
North America
North America represents around 25% of the global market share, driven by strong demand for housing solutions that cater to immediate occupancy. The United States leads the region due to favorable economic conditions, stable housing demand, and a robust real estate market. Ready-to-move-in properties are popular among first-time homebuyers, families, and individuals relocating for work. Canada also contributes to regional growth, with an emphasis on modern, high-quality homes that appeal to buyers seeking convenience and a seamless homebuying experience. The rise of online real estate platforms and virtual property tours further supports market expansion in North America.
Europe
Europe holds approximately 20% of the market share, with strong demand for ready-to-move-in homes in urban centers. Countries such as the United Kingdom, Germany, and France lead in adopting these properties due to their focus on reducing construction-related uncertainties and providing high-quality housing. The region’s aging population and preference for turnkey housing solutions that minimize maintenance have further driven market demand. The European Union’s emphasis on sustainability and energy efficiency in residential properties also aligns with the rising popularity of modern, ready-to-move-in homes.
Latin America and Middle East & Africa
Latin America and the Middle East & Africa together account for around 15% of the market share. In Latin America, countries such as Brazil and Mexico are witnessing growing demand for ready-to-move-in homes, driven by modernization initiatives and increasing urbanization. The Middle East & Africa region is experiencing steady growth, supported by economic diversification efforts, rising population, and a focus on urban infrastructure development. The demand for high-quality, ready-to-occupy properties in these regions reflects a growing awareness of the convenience and long-term value offered by such homes.
Key Player Analysis:
- R. Horton
- Lennar Corporation
- PulteGroup, Inc.
- NVR, Inc.
- Toll Brothers, Inc.
- KB Home
- Taylor Morrison Home Corporation
- Meritage Homes Corporation
- LGI Homes, Inc.
- Beazer Homes USA, Inc.
Competitive Analysis:
The Ready to Move in Homes Market is highly competitive, characterized by the presence of established homebuilders and regional developers who focus on delivering quality, convenience, and immediate occupancy. Key players such as D.R. Horton, Lennar Corporation, and PulteGroup dominate the market by offering a wide range of ready-to-move-in properties that cater to varying buyer preferences, including single-family homes, townhouses, and luxury residences. These industry leaders emphasize modern amenities, energy efficiency, and customizable options to differentiate their offerings. Smaller and regional developers contribute to market diversity by tailoring properties to local market demands and maintaining competitive pricing. Strategic partnerships with financial institutions, attractive financing options, and value-added services further shape market competition, driving growth and enhancing buyer experience. The emphasis on quality assurance, transparency, and timely delivery continues to be key factors in maintaining a competitive edge within this dynamic market.
Recent Developments:
- In 2023, D.R. Horton expanded its portfolio by acquiring a significant land parcel in Texas, aiming to develop a new community of ready-to-move-in homes to meet the growing demand in the region.
- In 2022, Lennar introduced a series of smart homes equipped with advanced automation systems, enhancing the appeal of their ready-to-move-in offerings by integrating modern technology for improved energy efficiency and security.
- In 2024, PulteGroup launched a new line of eco-friendly ready-to-move-in homes featuring sustainable materials and energy-efficient designs, catering to environmentally conscious buyers seeking immediate occupancy.
- In 2023, KB Home announced a partnership with a leading solar technology company to equip their ready-to-move-in homes with solar panels, providing buyers with sustainable energy solutions and reducing long-term utility costs.
Market Concentration & Characteristics:
The Ready to Move in Homes Market is moderately concentrated, with a mix of large, established homebuilders and regional developers competing to capture market share by offering high-quality, turnkey housing solutions. Major players such as D.R. Horton, Lennar Corporation, and PulteGroup lead the market through their extensive portfolios, innovative home designs, and focus on customer satisfaction. These companies emphasize the integration of modern amenities, energy-efficient features, and smart home technology to differentiate their offerings and meet evolving consumer expectations. Regional and niche developers contribute to market diversity by catering to localized demand and providing competitive pricing options. The market is characterized by a strong emphasis on quality assurance, transparency, and immediate availability, making it particularly appealing to first-time homebuyers, families, and investors seeking convenience and low-risk housing solutions. Competitive differentiation is driven by timely delivery, customizable options, and the ability to adapt to regional trends and consumer needs.
Report Coverage:
The research report offers an in-depth analysis based on Type, Unit Size, End User, and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand for ready-to-move-in homes will continue to rise as consumers prioritize convenience, eliminating construction delays and reducing uncertainties.
- Increased adoption of smart home technology and energy-efficient features will enhance market appeal and drive buyer interest.
- Urbanization and migration trends will boost demand for turnkey housing solutions in major metropolitan areas globally.
- Real estate developers will increasingly focus on offering eco-friendly and sustainable ready-to-move-in homes to cater to environmentally conscious buyers.
- Rising interest rates and economic volatility may pose affordability challenges, prompting market players to introduce flexible financing options.
- Online real estate platforms and virtual tours will further simplify the homebuying process, increasing market transparency and accessibility.
- Gated communities and properties with extensive amenities will gain popularity due to their security, community living, and lifestyle benefits.
- Government initiatives and subsidies promoting homeownership will support market expansion in various regions.
- Regional and local developers will play a key role in tailoring ready-to-move-in offerings to meet diverse consumer needs and preferences.
- Advances in construction technologies, such as modular and prefabrication methods, will enhance the availability and quality of ready-to-move-in homes.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Ready to Move in Homes Market?
What factors are driving the growth of the Ready to Move in Homes Market?
What are some challenges faced by the Ready to Move in Homes Market?
Who are the major players in the Ready to Move in Homes Market?
Which segment is leading the market share?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 622,340 million → 2032: USD 1,069,295.98 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Ready-to-move-in Homes Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Ready-to-move-in Homes Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Ready-to-move-in Homes Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Ready-to-move-in Homes Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Ready-to-move-in Homes Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Ready-to-move-in Homes Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Ready-to-move-in Homes Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Ready-to-move-in Homes Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 622,340 million → 2032: USD 1,069,295.98 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Ready-to-move-in Homes Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Ready-to-move-in Homes Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Ready-to-move-in Homes Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Ready-to-move-in Homes Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
